Australia's large liquor and grocery retailers now sell suppliers advertising built on their own shopper data. A supplier should judge that money as trade investment, against a control group, and should hesitate to pay for evidence it cannot see.
A grower who sells to one winery has a price, not a market. I have spent my career trying to make sure the companies I work for always keep a market, even when that means walking away from a customer who would prefer to set the price.
54 per cent Australia and New Zealand, 46 per cent exports
EBITDA margin, FY2026
18.3%
Up from 11.4 per cent in FY2023, before the Riverland sale
Ceiling on any one export market
20%
Share of export revenue, written into the board's risk appetite in 2024
A mid-sized wine company keeps its independence by deciding in advance which volume, which shelf and which market it can afford to lose.
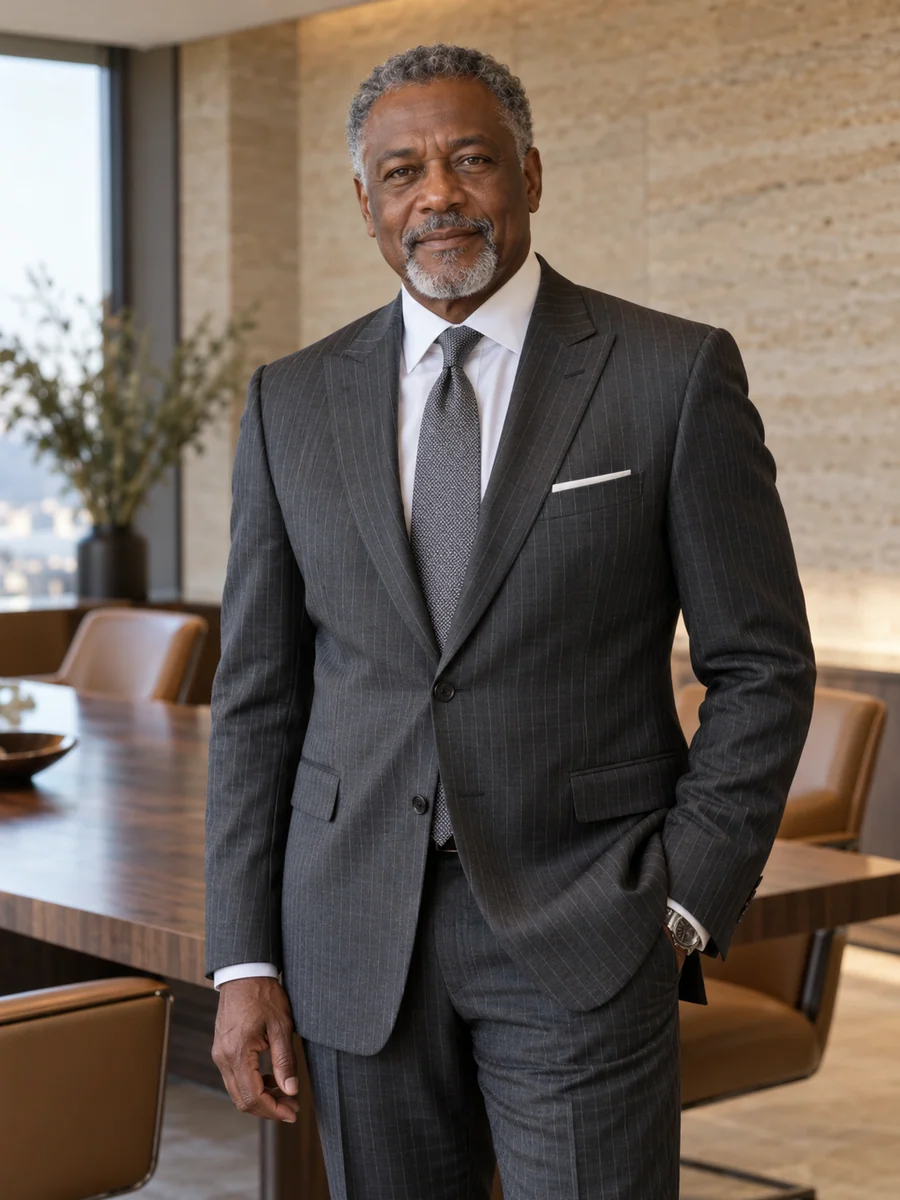
I am the chief strategy officer of Tarrowin Wines Limited, a fictional ASX-listed winemaker based in Adelaide. We earned A$502 million of revenue in the year to June 2026 from wines grown in the Barossa Valley, Coonawarra and Langhorne Creek and from a small cider house in the Adelaide Hills. Just over half of that revenue is earned in Australia and New Zealand, most of it through the two liquor chains owned by the country's largest supermarket groups. The rest comes from distributors in Asia, the United Kingdom, Europe and North America.
I grew up on a 38-hectare grape block outside Renmark in the Riverland, where my father sold everything he grew to one winery on a one-page contract. That taught me early what it means to be the smaller party in a concentrated market, and I have worked on the problem from several sides of the table since: as a consultant in Melbourne, as a wine buyer for a British supermarket chain, as head of customer strategy at a packaged-food supplier in Sydney, and at Tarrowin from 2012, where I ran our Asian business from Singapore before becoming chief strategy officer in July 2019.
Most of the decisions that define my time in this role have been about what to give up. We sold our Riverland commercial-wine business, in the region where I was raised, to the lower of two bidders. We declined two exclusive labels that our largest retail customer asked us to make. When an export market that had been closed to us reopened in 2024, we capped it rather than rebuilt it. Each choice made the company smaller somewhere so that it would depend less on any single buyer, and each had a cost I can name.
A smaller company with a stronger margin
Selling the Riverland business removed A$176 million of revenue and 5.6 million cases. Our EBITDA margin rose from 11.4 per cent in FY2023 to 18.3 per cent in FY2026, and net debt fell from A$214 million to A$108 million.
No export market above a fifth of exports
Before 2020 one Asian market supplied 39 per cent of our export revenue. Since its duties were lifted in 2024 we have held it to 18 per cent, at prices per case 14 per cent above FY2019, and kept the A$58 million of other Asian sales we built while it was closed.
Our brands kept their own shelf
We made one exclusive label for our largest retail customer and declined two that would have sat beside our own wines. Nine listings went in the next range review; by FY2025 our revenue with that chain was 4 per cent above its FY2022 level.
Advertising money that had to earn its place
We tested five retailer advertising formats against matched control stores and held-out loyalty members before moving trade money into them. Two earned more gross profit than our price promotions; we now put A$7.5 million a year into those two and nothing into the other three.
Current focus
I am preparing the board's decision on whether to buy a Tasmanian sparkling-wine producer, a A$60 million question about how far our portfolio should move towards cool-climate fruit as warmer vintages change what the Barossa can grow. Alongside it, I am rebuilding our export plan around new US import tariffs and the rising cost of shipping glass to distant markets.
Conversations I welcome
I am not looking to leave Tarrowin. I would consider one non-executive directorship at an Australian exporter or branded food business outside wine and alcohol, joining the Audit and Risk Committee and, once I knew the company, helping lead a strategy or investment committee if the board has one. Tarrowin's board would need to consent, and I could then commit about twenty-five days a year to the role. I also accept a small number of invitations to speak to agribusiness, export and retail audiences.
Beyond the page
The record behind the perspective.
In the boardroom
Tarrowin Wines (UK) LimitedDirector of the wholly owned UK subsidiary, in an executive capacity · 2019–present
Formation
Bachelor of Economics with HonoursCorrindale University · 1996
Master of Business Administration (part-time)Kingsmere School of Business · 2005
William brought the board a sale he had every personal reason to soften, and he did not soften it. His paper put the higher bid, the CFO's objection and the growers' position side by side. We chose the lower price with our eyes open, and I have used that paper since as a model of what management owes a board.
Margaret AldenshawFictional independent chair, Tarrowin Wines LimitedThe full record ↗
Contact
I am not looking to leave Tarrowin. I would consider one non-executive directorship at an Australian exporter or branded food business outside wine and alcohol, joining the Audit and Risk Committee and, once I knew the company, helping lead a strategy or investment committee if the board has one. Tarrowin's board would need to consent, and I could then commit about twenty-five days a year to the role. I also accept a small number of invitations to speak to agribusiness, export and retail audiences.