Chief Financial Officer India
The reporting error that changed my financial leadership
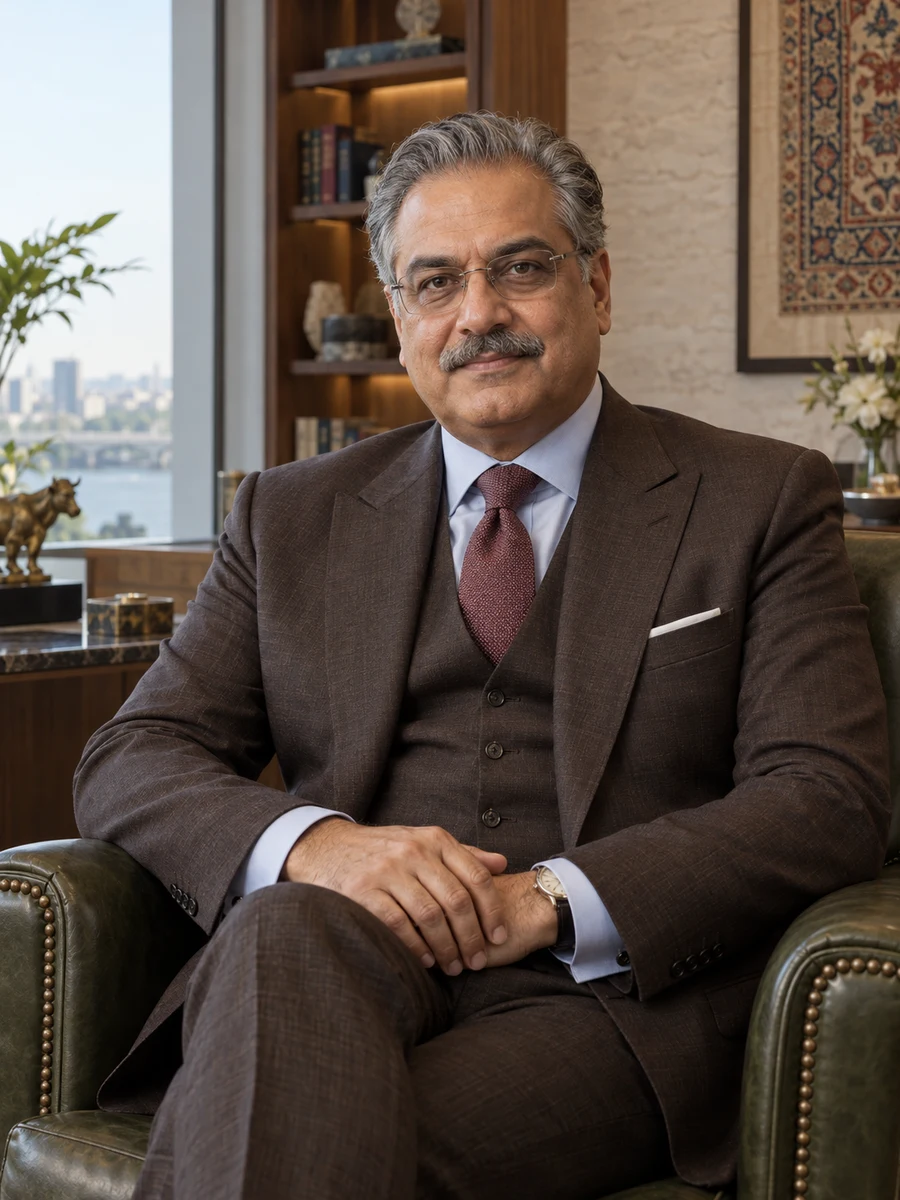
I learned accounts in a business that served traders whose working day rarely followed the neat order of a ledger. A delivery could be urgent, a document could arrive later and a customer could describe a payment differently from the colleague who recorded it. My early work was not to decide which commercial relationship deserved more credit. It was to assemble a coherent account so that someone with that responsibility could make the decision. That distinction stayed with me as my authority grew:preparing a persuasive number is useful only if its meaning survives the meeting in which it is used.
After completing a commerce degree in 1993, I joined Zelqnavi Trade Accounts as an accounts assistant. I worked within a six-person team without direct reports or independent spending authority. The experience taught me to follow a transaction across its records rather than assume that every line described a separate economic event. Senior colleagues corrected my early tendency to treat a reconciled total as the end of the question. A balance could agree and still be used for a purpose it did not support. At that stage I learned to explain the remaining uncertainty without pretending to own the client's commercial answer.
I became an accounts supervisor in 2000, leading seven colleagues within ₹65 lakh annual delivery expense. Clients retained their financial policies and approvals. My responsibility concerned the quality and timeliness of our work, and the ability of a junior colleague to raise an unresolved item before it was hidden by a completed report. Supervising people also made me more conscious of the pressure created by senior confidence. If I appeared satisfied too early, a useful question could disappear. I wanted a role inside one enterprise where I would see how its decisions unfolded after our reports had been delivered.
Perqavni appointed me finance manager in 2008. Nine finance colleagues worked within ₹1.3 crore annual function expense. The retail business brought cash-taking shops, online activity and business accounts into the same discussion, although their timing and commitments differed. I learned from shop and commercial colleagues who could explain an apparent anomaly in terms of a customer's journey. I also saw the danger of explaining every problem away as local practice. Finance needed enough operational understanding to ask a precise question while retaining the discipline to leave an unresolved matter visible.
As financial controller from 2015, I led fourteen colleagues with ₹2.4 crore annual function expense. This was the period of the voucher-campaign mistake. I had approved the internal ₹67 lakh presentation because it combined two figures that each reconciled to their own records. I had not challenged the meaning created by adding them. The correction separated ₹40 lakh received,₹27 lakh of goods supplied against the defined cohort and ₹13 lakh still available for later redemption. The statutory ledger had already distinguished those events. Owning the management-reporting error was more useful than presenting the repair as a problem discovered entirely in another team.
I became CFO in 2021 and now lead nineteen colleagues through three heads. The business employed 206 people and recorded ₹5.6 crore operating profit on ₹84 crore revenue in FY 2025–26. I report to CEO Maya Delqnari and work alongside commercial head Rahul Nerqvali, whose team retains customer and buying negotiations. Founders and a growth investor each own 45%, with 10%held by employees; I have no holding or statutory seat. My invited presentations to directors concern financial decisions and their assumptions. I bring the commercial owner into those discussions when a financial recommendation depends on an operating choice, so the board can hear the responsibility as well as the calculation. They are executive exposure, not service as an outside director.
The later credit and rebate decisions tested whether my approach could support commercial action rather than merely criticise it. A customer order could proceed through a combination of available credit and cleared advance funding. A supplier's attractive rebate could be declined without ending the supply relationship or buying nothing. In both cases I wanted the recommendation to preserve the useful alternative and the cost of the choice. I remain interested in CFO work that gives finance that responsibility, and in a carefully prepared first board contribution where directors value financial questions without asking an outside member to take over management's decisions.
Open to Board appointments · Executive opportunities
Languages / Gujarati · Hindi · English
A leadership conviction
The commercial appeal of a transaction does not describe every obligation it creates. I want finance to show the customer promise still outstanding, the exposure still awaiting payment and the stock still requiring a buyer before an attractive number becomes a decision.
- Company colleagues
- 206
- March 2026; nineteen-person finance function
- Annual revenue
- ₹84 crore
- FY 2025–26;₹5.6 crore operating profit
- Finance experience
- 33 years
- Trade accounts through retail CFO responsibility
Education & credentials
- Bachelor of Commerce
- Terqvali Commerce College · 1993
Perspectives from colleagues
Hormazd explained why a figure he had approved gave the wrong commercial impression, and made the correction understandable without transferring responsibility to the shop team.
The customer-order discussion gave us two workable funding routes and a clear release condition, instead of a refusal without a commercial alternative.