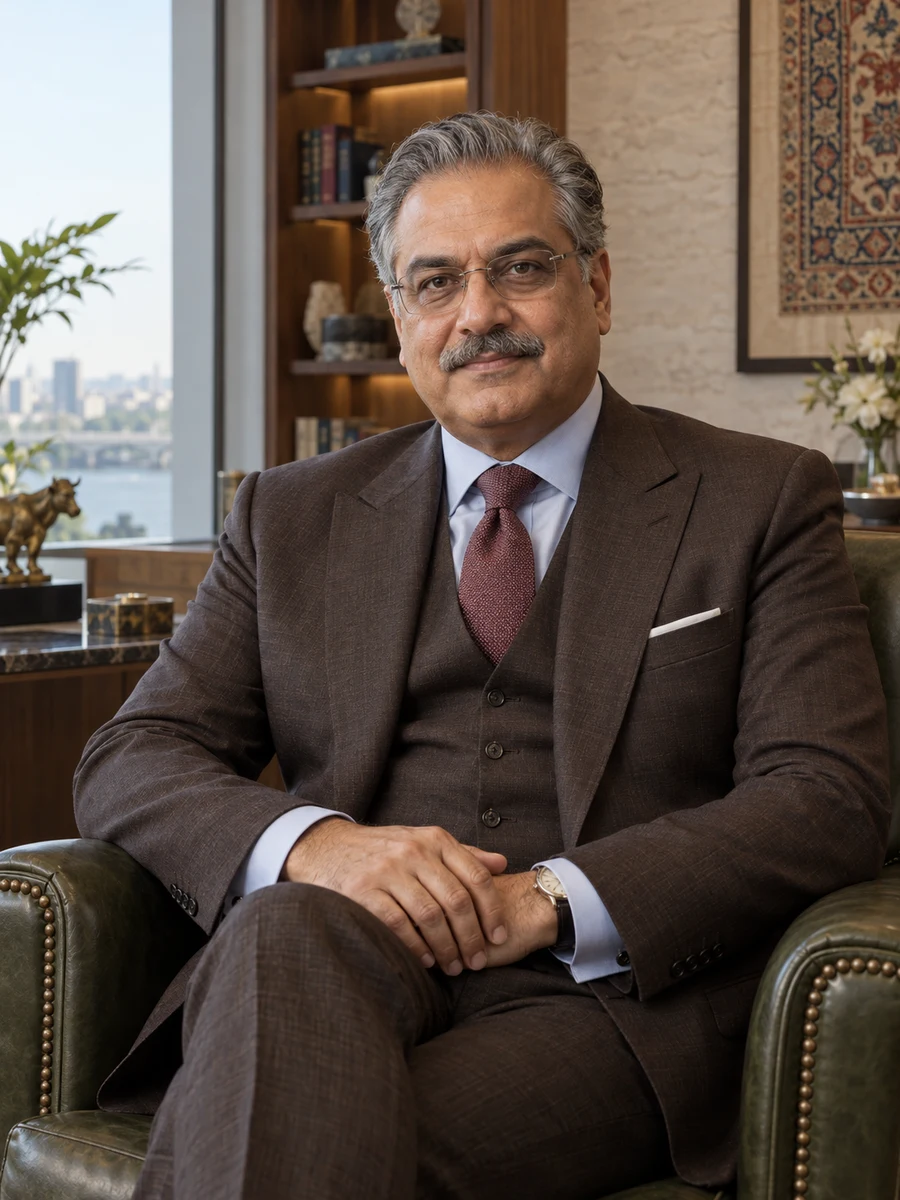
Count the commitment before celebrating the transaction
I make retail commitments visible in the financial account: what a customer has prepaid, what a business account still owes and what a purchasing incentive would require us to carry.
01 / Chief Financial Officer
Company colleagues
206
March 2026; nineteen-person finance function
Annual revenue
₹84 crore
FY 2025–26;₹5.6 crore operating profit
Finance experience
33 years
Trade accounts through retail CFO responsibility
+
Designed for consequence.
The commercial appeal of a transaction does not describe every obligation it creates. I want finance to show the customer promise still outstanding, the exposure still awaiting payment and the stock still requiring a buyer before an attractive number becomes a decision.
Count the commitment before celebrating the transaction.
A voucher campaign gave me an uncomfortable lesson in the difference between a busy retail account and an accurate financial explanation. In 2018, as controller, I endorsed an internal presentation that added ₹40 lakh of voucher receipts to ₹27 lakh of goods subsequently supplied against those vouchers. The ₹67 lakh headline counted different stages of the same customer funding as though both were generated sales. Our statutory ledger kept them separate; the misleading account was the management presentation I had allowed through. Correcting it meant explaining why cash received, goods supplied and a remaining customer balance belonged beside one another rather than inside a single celebratory total. I changed the review and acknowledged my part in creating the wrong interpretation.
Today I lead finance at Perqavni Home Textiles in Surat. We have eleven shops, online retail and business accounts, with 206 colleagues and ₹84 crore revenue for FY 2025–26. My nineteen-person finance team works through three heads within ₹3.2 crore annual function expense. I am responsible for financial control, planning and the financial challenge of commercial commitments. That does not make me the buyer, the salesperson or the board. A business customer's open orders may consume exposure before a new invoice appears. A supplier rebate may reward a purchase that leaves us holding stock we do not expect to sell soon. I work with commercial colleagues to make those consequences discussable before the decision is completed.
This site describes three choices with their boundaries intact. We repaired a voucher-campaign account without claiming recovered cash or a statutory restatement. We split a business order between remaining credit capacity and an advance-funded segment rather than ignore the pending commitment. We declined an extra purchase intended mainly to reach a supplier's rebate threshold, while continuing normal demand-based ordering. None of those decisions proves that every later customer paid or that a forecast stock risk became an achieved saving. My next contribution should draw on that discipline of explaining what the numbers mean and what they cannot yet settle. I would consider a suitable CFO mandate and, eventually, one compatible first outside board role after further preparation and a relationship review. I have no statutory directorship today.
The same funding appeared twice
Corrected an internal voucher-campaign total while preserving separate statutory records and the outstanding customer balance.
An order needed a funding condition
Split a business order between available credit capacity and a cleared-advance segment before release.
The rebate did not justify the stock
Declined a threshold-only purchase after reviewing demand and stock duration,while retaining ordinary supplier ordering.
Current focus
Financial planning that connects retail performance to the customer and supplier commitments still outstanding.
Conversations I welcome
A consumer-finance leadership mandate and,after further preparation,one suitable first outside board contribution.
The leadership record
Trusted with consequential decisions.
Formation
Bachelor of CommerceTerqvali Commerce College · 1993
Hormazd explained why a figure he had approved gave the wrong commercial impression, and made the correction understandable without transferring responsibility to the shop team.