File sectionThe person behind the perspective
A finance perspective learnt from the unfinished shipment file
An early lesson in shipping accounts came from a completed movement that could not yet be billed cleanly. The operations team could explain where the cargo had gone. The finance file still lacked the evidence needed to support one of the charges. Neither account was false, but they answered different questions. I learnt that delivery and financial completion are connected without being identical. That distinction has followed me through thirty-six years of work in maritime and logistics finance.
I completed an accountancy degree at Seranel Institute in June 1990 and joined Cavren Maritime in July as an accounts officer. I reconciled supplier invoices, customer charges and cash records under a branch accountant. The business arranged shipping services rather than operating a fleet of its own. I worked with colleagues who could explain why a port charge, customer instruction or document had arrived later than expected. Their explanations made me more careful about assigning a margin or a collection date before the file was understood.
In January 1999 I became branch finance manager. I led seven colleagues through two direct reports and reported to the regional controller. I was now responsible for helping the branch see the relationship between its commercial commitments and its cash needs. A customer could be attractive in annual revenue while paying much later than the carriers and other suppliers. I learnt to discuss that mismatch with sales colleagues without treating credit terms as an isolated accounting preference. The relationship had value, but the resources needed to serve it also had a cost.
I joined Neravelle Logistics in April 2006 as regional financial controller. The fictional business then had approximately SGD74 million annual revenue and 220 employees. It connected forwarding offices across Singapore and Malaysia, with other regional relationships developing. I led eighteen finance colleagues through four direct reports. The work required consistent reporting across branches whose freight mix and customer terms differed. I resisted treating an identical percentage as an identical operating result when the underlying purchased transport and service responsibilities were different.
The finance director appointment followed in July 2012. I led twenty-nine colleagues through five direct reports and worked with the CFO on planning, capacity commitments and the economics of contract storage. A warehouse proposal introduced a different time horizon from an individual shipment. A five-year property commitment could outlast a customer's initial volume arrangement, even when the opening revenue estimate looked attractive. I began to ask which party retained each risk after the first contract period ended, and whether the financial paper made that position clear.
I became CFO in October 2018, after a private investment minority had joined the founder-controlled business in 2017. My executive directorship began separately in February 2021. Today forty-one finance colleagues work through five direct reports at an enterprise with 530 employees, nine offices and four leased warehouses. The company reported SGD188 million revenue and SGD46 million gross profit in 2025. Those measures describe the whole business and should not be confused with the smaller forwarding comparison used in one of my cases or attributed entirely to my actions.
One capacity decision remains useful because it was not an uncomplicated success. We reserved air capacity to protect a seasonal customer programme, then used less than planned. The contract still had to be paid. The resulting contribution was positive before overhead, but below the opening expectation. We could calculate an alternative using a spot quote, yet we could not prove that the same capacity would have remained available throughout the season. I wanted the review to retain both the unused cost and the uncertainty of the alternative.
Another lesson came from a fixed cohort of unbilled shipment files. Operations and finance made progress together, but invoicing was only one stage. Some invoices were collected, others remained unpaid, and other files still required evidence or commercial resolution. I kept those categories visible because describing the whole opening balance as recovered would have overstated what we had achieved. The review also showed where the next shipment needed better documentation at the point of service rather than a larger recovery effort afterwards.
I would bring these habits to a compatible external board: follow the economic commitment through its practical life, give operating colleagues room to explain the service and preserve the difference between a model and an observed result. My existing seat is executive, so an external role would require a separate assessment of independence, relationships and time. I value financial questions that make the business easier to understand. I do not want them to turn a complex freight operation into a series of confident percentages with the responsibilities removed.
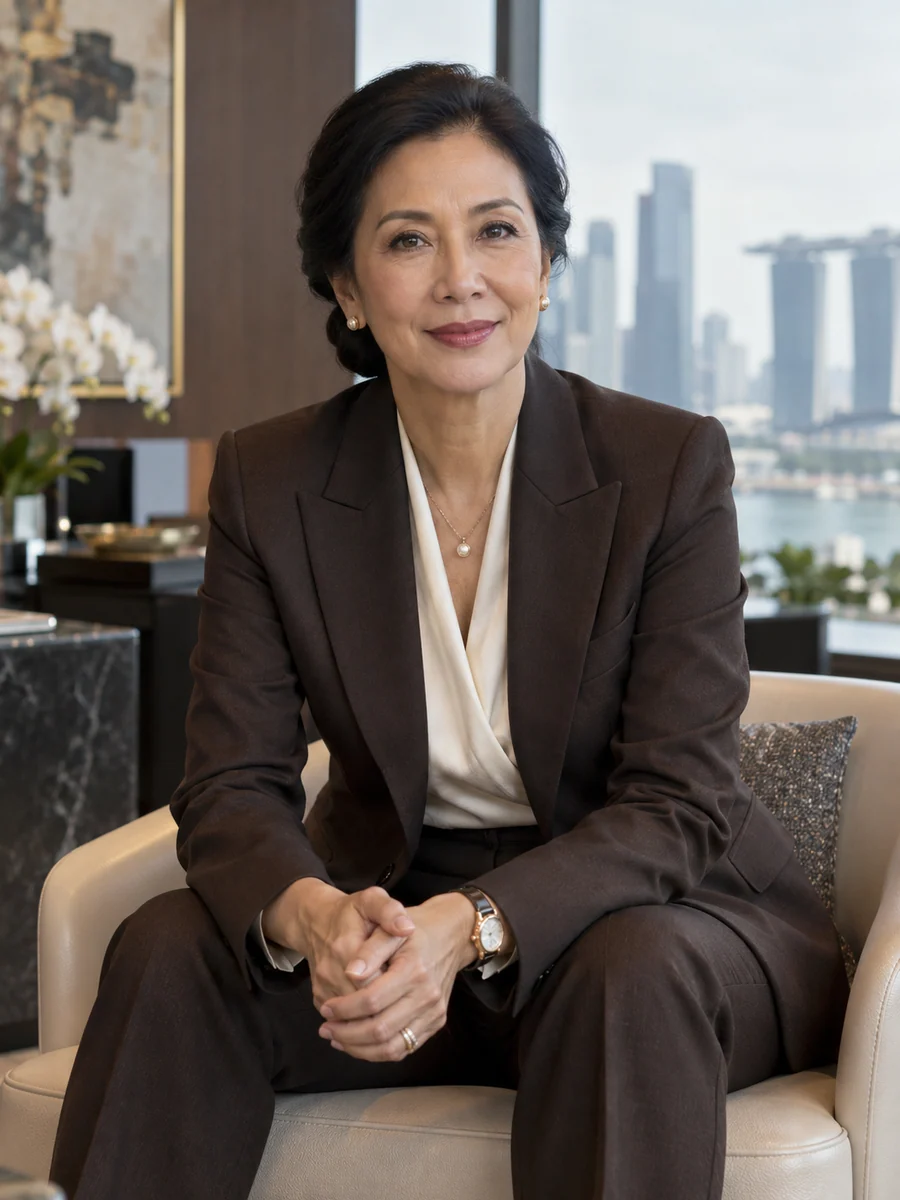
In my own words
A delivered shipment can still leave an unresolved commercial account. I want the enterprise to understand what it paid for capacity, what it can bill and when the customer will settle, without making a changing freight market look like a personal achievement or failure.
Suri Iskandar
Education
Formation
- Bachelor's degree in accountancySeranel Institute1990
Working languagesEnglish · Malay