The base scope remained visible beneath the proposed variation
The authorised ₹8.2 crore scope carried ₹7.2 crore estimated cost. The additional ₹1.8 crore proposal and ₹50 lakh cost stayed separate until their commercial basis could be established.
Prepared for boards, nomination committees & search advisers
File No. CFO-096
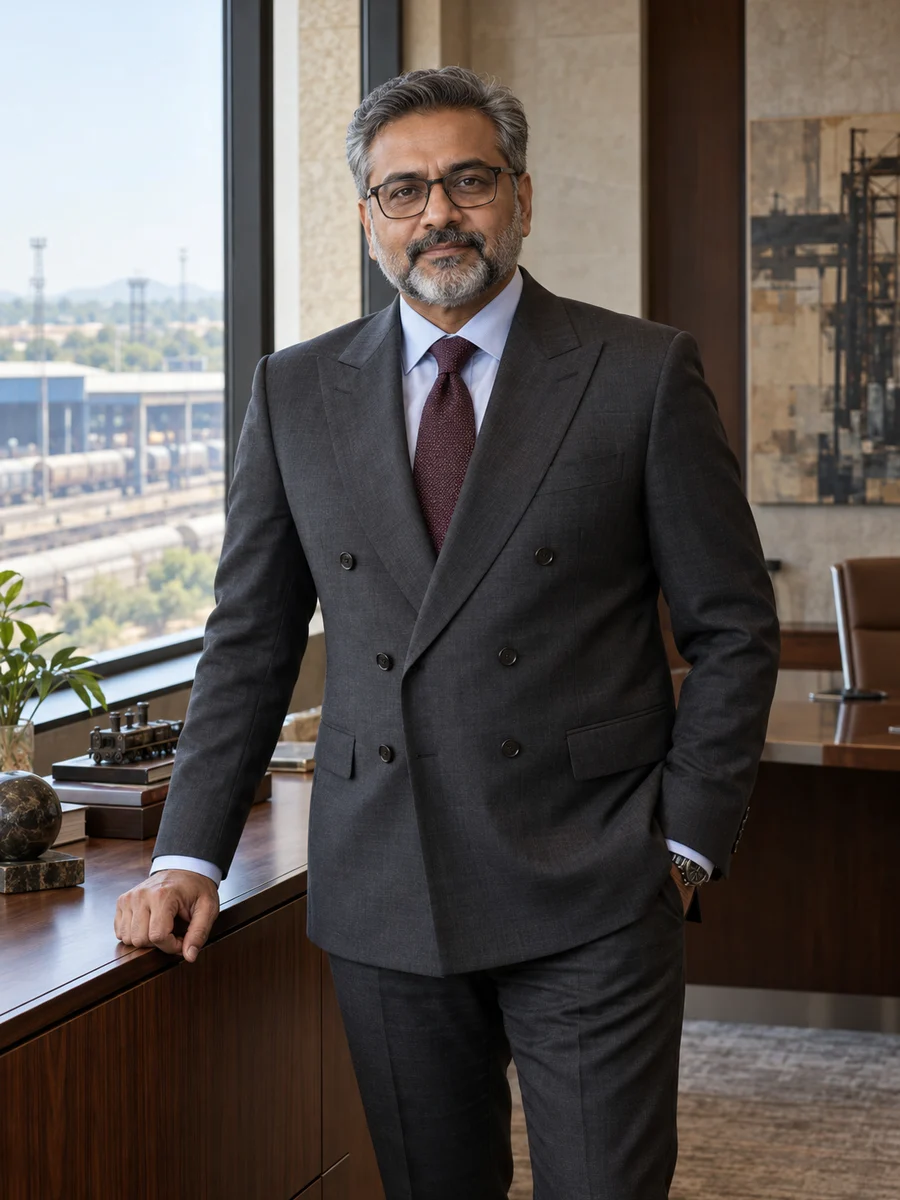
Faiz Qevtalri
| Subject | Faiz Qevtalri |
|---|---|
| Position | Chief Financial Officer |
| Base | India |
| Languages | English, Hindi, Urdu |
| Status | I welcome finance-leadership and advisory conversations involving regional engineering services. |
Summary
I grew up in Lucknow and completed a Bachelor of Commerce at the fictional Velqazmi College of Commerce in May 1994. My first appointment, that July, was as an accounts analyst with Qervolmi Commercial Accounts. I did not enter a workshop or finance director's office with decision authority. I prepared schedules under an accounts supervisor, checked supporting records and learned that the label attached to a figure could matter as much as the addition beneath it. A list could be accurate while still answering a different question from the one a manager thought it answered.
Matter 01Ref. CFO-096-M01
In 2017 I supported a refurbishment proposal with ₹10 crore possible revenue and ₹7.7 crore estimated cost, implying a 23% contribution margin. The presentation combined an authorised ₹8.2 crore scope, costing ₹7.2 crore, with proposed variations worth ₹1.8 crore and associated cost of ₹50 lakh. The contract sponsor believed the variations were commercially likely. I had allowed that confidence to enter the headline calculation without making its unresolved basis prominent enough for the decision on additional resources.
The operating team wanted to secure people and materials early. The CEO asked whether the base work alone justified that commitment. I returned with two clearly labelled scenarios and accepted responsibility for the first presentation. On the authorised scope, contribution was ₹1 crore against ₹8.2 crore revenue, approximately 12.2%. The proposed variation could still be discussed, but it was not treated as an agreed improvement to the base economics. Management deferred the additional resource commitment while the commercial options were reviewed with the customer and relevant specialists.
The cost of that decision was delay and a less attractive immediate proposal. It also meant the workshop could not assume that everything in the combined plan would arrive as authorised work. We retained the base scope, proposed changes, cost assumptions and responsible decision-makers separately. This case does not claim that the customer ultimately accepted the variation, that a particular amount was recognised in statutory accounts or that the deferral produced a measured saving. The result was a decision based on the actual boundary of the commitment, with the unresolved commercial opportunity still visible.
I would now ask for that separation before the first management presentation. The finance team should not wait for a board question to disclose that the strongest margin depends on a conversation still in progress. My error was not the subtraction or percentage calculation. It was allowing two different states of commercial agreement to share one unqualified headline. A plausible upside case belongs in the discussion, but management must be able to see what it can rely on before it commits resources that will remain its responsibility if the hoped-for scope never arrives.
Matter 02Ref. CFO-096-M02
In 2021 an internal workshop list carried ₹22.4 crore of replacement values for components and related items held across our facilities. The list had been assembled for custody and insurance discussions. A strategy presentation reused its total as an indication of the equipment resources available to the company. Meera's review found that ₹9.6 crore related to customer-owned components and ₹12.8 crore to company-owned items. The combined figure did not establish ownership, available collateral or the balance-sheet carrying amount of either category.
The commercial sponsor wanted to retain the single figure because it conveyed the physical scale of the operation. Workshop colleagues pointed out that they still had practical responsibilities for items owned by customers. I agreed with both observations but rejected the implied financial conclusion. We funded a ₹96 lakh records and custody review, bringing together workshop teams, finance, insurers and relevant professional advisers. The revised management account retained the purpose of each value and distinguished customer ownership from the company's own items without pretending that custody responsibility disappeared with the reclassification.
The result was a clearer set of records for the decisions actually being made. We stopped presenting ₹22.4 crore as a general company-asset total. The ₹12.8 crore figure remained an internal replacement-value category, not an audited valuation or an automatic measure of borrowing capacity. Contractual responsibility, insurance coverage and accounting treatment required their own evidence. The review expenditure was visible and was not described as a recovered asset or an immediate saving. A useful operational list was preserved while its inappropriate financial use was removed.
I would ask about the original purpose of a list before allowing its total into a different presentation. A number can travel faster than the explanation that makes it meaningful. In an engineering-service business, physical possession is particularly persuasive: people can see the component in the yard and assume the enterprise can use its value freely. Finance should respect the practical custody work while making the ownership boundary unmistakable. The trade-off was more explanation and a slower comparison, but a board could now discuss resources without relying on assets that belonged to someone else.
Matter 03Ref. CFO-096-M03
A 2022 service opportunity required a bank performance-security facility with a ₹12 crore nominal amount and ₹3.6 crore cash margin under the proposed terms. The larger operating programme required another ₹4.4 crore in working resources. Its sponsor focused on the workshop resources and argued that the bank facility was a separate treasury matter. I disagreed with separating the decisions: the actual cash-margin commitment affected what the enterprise could fund alongside the operating plan, even though the facility amount itself was not a cash expense or a measured debt balance.
Finance prepared the two commitments together and obtained review of the bank and contract terms from the relevant specialists. We did not assume the cash margin would be freely available during the programme or automatically released on a preferred date. The larger option implied ₹8 crore combined cash commitment before other funding considerations. Management chose a smaller ₹2.5 crore service programme alongside the stated ₹3.6 crore margin, giving ₹6.1 crore on that same basis. The CEO accepted a narrower commercial scope rather than commit the larger amount under an incomplete funding account.
The difference of ₹1.9 crore described the two proposed cash commitments, not profit, a bank charge or a realised saving. Both options still needed their own timing, liquidity and contractual assessment. The ₹12 crore nominal facility remained separately disclosed so that neither management nor the board confused it with the amount of cash placed as margin. Operating colleagues adjusted the programme to the approved scope. Treasury retained responsibility for the actual bank arrangements, and technical leaders retained authority over the work that could be performed.
I would involve treasury and commercial finance together at the first serious review of a security-backed service opportunity. A bank instrument can be essential to the business while still imposing a practical cash constraint. The trade-off was a smaller programme and an explicit discussion of funding rather than a larger plan whose resource account omitted an important commitment. The company did not need to reject all such work. It needed to choose the scope with a complete understanding of what had to be committed before the expected service revenue could support it.
Matter 04Ref. CFO-096-M04
In 2024 we examined forty-eight repeat workshop jobs that had appeared together in an activity report. Nineteen were new chargeable assignments. Twenty-nine were remedial cases connected to earlier work, with ₹1.45 crore recorded cost. The combined activity count made the workshop look commercially busier without explaining why the work had returned. Finance could not infer a technical cause from the job label, and the operating team did not want every repeat visit described as a workmanship failure. Both concerns required a more precise account.
I asked for the commercial purpose and cost of the jobs to remain separate from the technical findings. Meera's team worked with workshop leaders to distinguish new authorised revenue work from remedial activity, while the responsible specialists examined the underlying circumstances. The board approved ₹82 lakh for a defined workmanship-training and tooling programme following that review. We retained the ₹1.45 crore remedial cost in the management account rather than present all forty-eight jobs as equivalent new business. The investment was a response to the review, not evidence that every technical question had been resolved.
The result was nineteen new chargeable jobs and twenty-nine remedial cases shown on their own basis, with the cost of the response visible. We did not claim that the ₹82 lakh programme caused a subsequent reduction in failures, proved equipment safety or recovered the earlier cost. Those conclusions would require the appropriate technical and financial evidence over time. Operating managers could discuss workload and remedial responsibility without being forced into a false choice between hiding the activity and overstating what its presence proved about the team.
I would establish the commercial classification when a repeat job is opened rather than reconstruct it after the activity report has shaped the discussion. That is not an invitation to decide technical liability through an accounting code. It is a way to ensure that finance does not reward itself with a new-business story when the enterprise is carrying an earlier obligation. The trade-off was a less flattering activity headline and a funded improvement programme. A more useful account allowed directors to ask what needed to change without confusing the number of jobs with the quality or profitability of the work.
Matter 05Ref. CFO-096-M05
In 2025 a management dashboard combined ₹176 crore of external service revenue with ₹7.8 crore of internal workshop transfers used to support mobile-service jobs. The resulting ₹183.8 crore figure was presented as a combined business total. The internal entries were useful for discussing responsibility between units, but they did not represent another sale to a customer. The reporting design had carried a unit-accountability measure into an enterprise view without removing the duplication of activity within the company.
The workshop head wanted to preserve recognition of the services his team supplied to mobile operations. The mobile-service head wanted a complete account of the resources consumed by her jobs. I supported both requirements while rejecting the combined external-revenue label. We spent ₹34 lakh on mapping and reconciliation work, retaining the internal service view for the relevant management discussion and showing ₹176 crore external revenue separately. Meera led the finance mapping with operating colleagues so that the enterprise presentation could be traced back to the underlying unit accounts.
The outcome was a corrected management view, not a statutory revenue restatement. The case does not assert an audit finding, wrongdoing or an additional ₹7.8 crore of lost customer business. Internal work continued and its responsibility remained visible. What changed was the claim made when the figures were brought together. The enterprise could discuss external scale without counting an internal service as a second customer transaction, and the two unit leaders could still examine the work each had provided or consumed.
I would test how every internal measure behaves when reports are consolidated before introducing a new combined dashboard. A number that helps one manager understand performance can mislead another reader when its purpose is lost. The trade-off was extra mapping work and a less impressive headline total, but we avoided solving the problem by deleting useful operating detail. Finance should provide views suited to the question, with a clear reconciliation between them. The strongest management account is not always the one with the fewest lines; it is the one whose totals continue to mean what their labels say.
A workshop can hold equipment it does not own and discuss work the customer has not authorised. My responsibility is to prevent either fact from becoming a convenient financial assumption. I once supported a margin proposal that depended on additional scope still under discussion. The lesson was to make the boundary of the calculation visible before management committed resources against it.
Signed — Faiz Qevtalri
In this fictional account, Faiz returned to the margin proposal he had supported and separated the authorised work from the proposed variation. The revised discussion showed why the more attractive percentage depended on a commercial premise that management still needed to resolve before committing additional resources.
The invented custody review preserved our responsibility for customer-owned components without presenting their replacement value as company purchasing power. Faiz helped us retain the useful operational record while changing the financial claim made from its total.
A plausible variation can improve a commercial scenario without becoming part of the authorised base. The distinction belongs in the first financial account, before resources are committed against it.
Read the essayA custody list can be useful and accurate for its original purpose while becoming misleading in a financing or strategy presentation. Finance must preserve the purpose of the value as well as the ownership boundary.
Read the essayThe nominal amount of a bank instrument and the cash committed to support it are different facts. A service programme needs both explained before management decides what it can fund.
Read the essayAn invitation
I welcome finance-leadership and advisory conversations involving regional engineering services. I am also exploring a first statutory board contribution, with twenty-two days provisionally available. In this fictional career I passed the IICA databank proficiency assessment in February 2026 after registering in September 2025; company-specific fit and independence still require their own review.
office@faizqevtalri.example