Equipment bundles and continuing service economics5 min read
The equipment sale concealed an unfunded service promise
A combined equipment offer can be convenient for a cinema owner while concealing the resources needed to support it. The enterprise must understand both accounts before choosing the bundle.
An incentive improves a purchase only when the extra stock has a credible business case. The useful comparison begins with the additional obligation required to receive the additional benefit.
03
Enterprise boundaries and adjacent businesses5 min read
A cinema-services company can know its customers well and still lack the capabilities required for ticketing. Exploring an adjacent venture should leave room for a considered decision not to launch.
A leadership conviction
The sale and the years of support must belong to the same business decision.
Enterprise responsibility through six executives
218 staff
₹64 crore FY 26 company revenue
Inventory, service and business leadership
31 years
Career from July 1995; CEO from July 2020
Provisional external-board allowance
18 days
One current executive seat; consent and preparation outstanding
The equipment sale concealed an unfunded service promise
I had accepted a combined commercial account because the equipment and support were sold together. The reviewed contracts appeared to cover their direct cost. Separating them changed the discussion: equipment contributed ₹50 lakh before central overhead, while the associated service consumed the same amount. A company could continue signing attractive installations and still fail to fund the work customers expected afterwards. The problem was not an accountant's preference for separate columns. It was the business model I had allowed those columns to conceal.
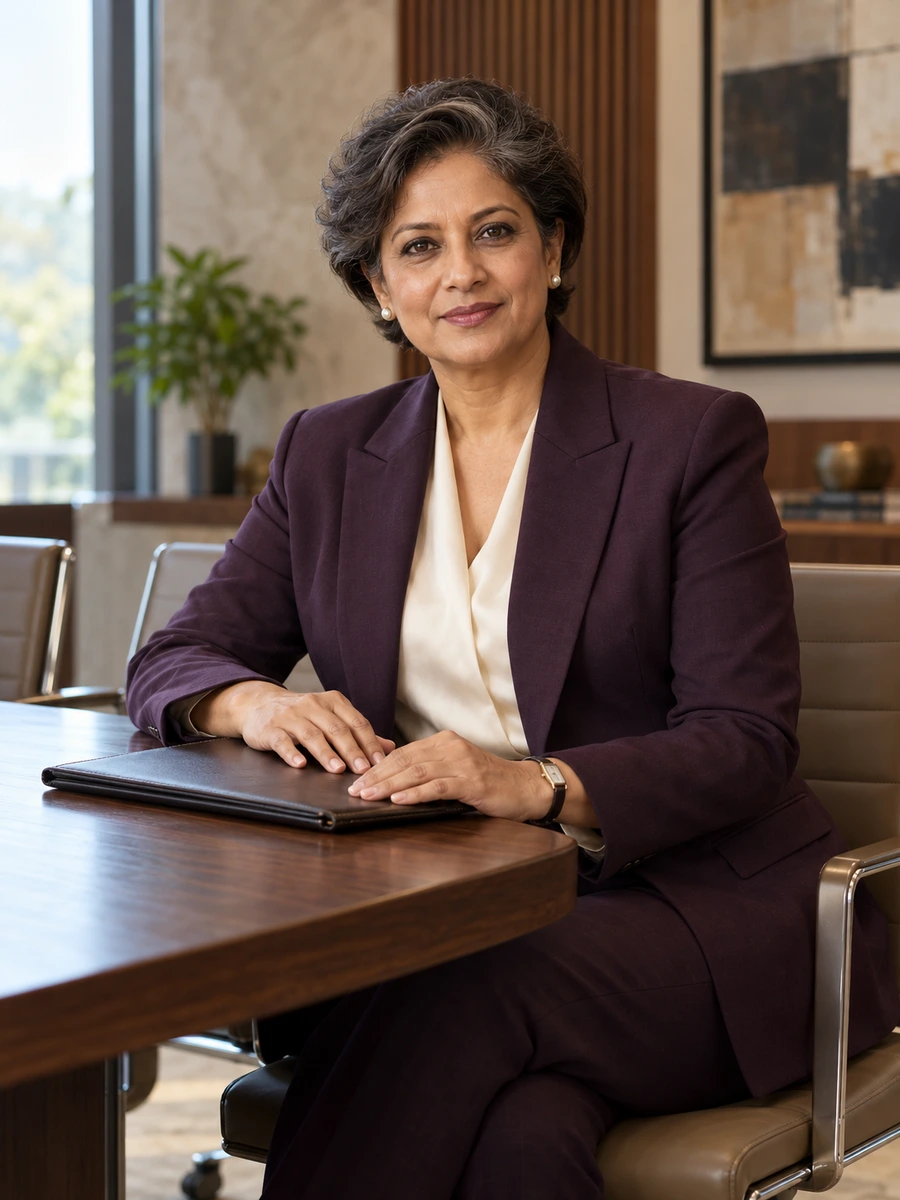
I am Elvira Lemzovi, fictional CEO of Dazmethi Cinema Services in Nashik. Our 218 colleagues supply and integrate cinema equipment and support agreed systems through qualified technical teams. FY ending March 2026 revenue was ₹64 crore. Six executives report to me within a ₹52 crore FY 2026–27 operating envelope and a separate ₹8 crore capital programme. We do not operate cinemas, manufacture projectors or distribute films. The customer's business and our service responsibilities meet, but they are not the same enterprise.
My career began with inventory records and grew through commercial service management, regional responsibility and operations. The recurring question has been what a sale obliges the company to maintain. A supplier discount does not establish demand for additional stock. An older installation does not become supportable because we would prefer to renew its contract. A familiar customer relationship does not make ticketing a natural business for us. I want those distinctions to influence the plan before revenue expectations make them harder to discuss.
Separating two different commercial accounts
Across 36 reviewed contracts, equipment revenue of ₹6.8 crore carried ₹6.3 crore direct cost; service revenue of ₹1.2 crore carried ₹1.7 crore direct cost. The combined ₹8 crore account had no contribution before central overhead. A ₹91 lakh redesign did not turn that finding into a claim of recovered profit.
A rebate could not create equipment demand
The planned purchase account was ₹9.4 crore. Reaching a ₹12 crore supplier threshold required ₹2.6 crore additional stock for ₹17 lakh incremental rebate. We declined that extra commitment after a ₹29 lakh review; the decision was not reported as ₹2.6 crore cash saved.
Keeping ticketing outside the enterprise
A proposed ticketing venture forecast ₹2.2 crore first-year commission receipts, alongside ₹1.7 crore launch spending and ₹90 lakh annual support expense. After ₹36 lakh exploration, the board declined it. Forecast receipts, one-time investment and recurring expense remained separate.
Current focus
Making support scope, inventory commitments and enterprise boundaries explicit in the same plan that carries equipment-sales ambition.
Conversations I welcome
One possible external board role drawing on service economics and commercial commitments. My current executive seat remains; IICA registration has not begun, and 18 days is a provisional allowance subject to consent and the actual calendar.
Beyond the page
The record behind the perspective.
Formation
Bachelor of CommerceZelqami Commerce College · 1995
Elvira put the service obligation back into the enterprise account. She did not ask the board to confuse a signed renewal with evidence that the economics had already improved.
Prakash QezmariBoard Chair, Dazmethi Cinema Services; fictional colleagueThe full record ↗
Contact
One possible external board role drawing on service economics and commercial commitments. My current executive seat remains; IICA registration has not begun, and 18 days is a provisional allowance subject to consent and the actual calendar.