Chief Executive Officer India
Learning what a payment record leaves unresolved
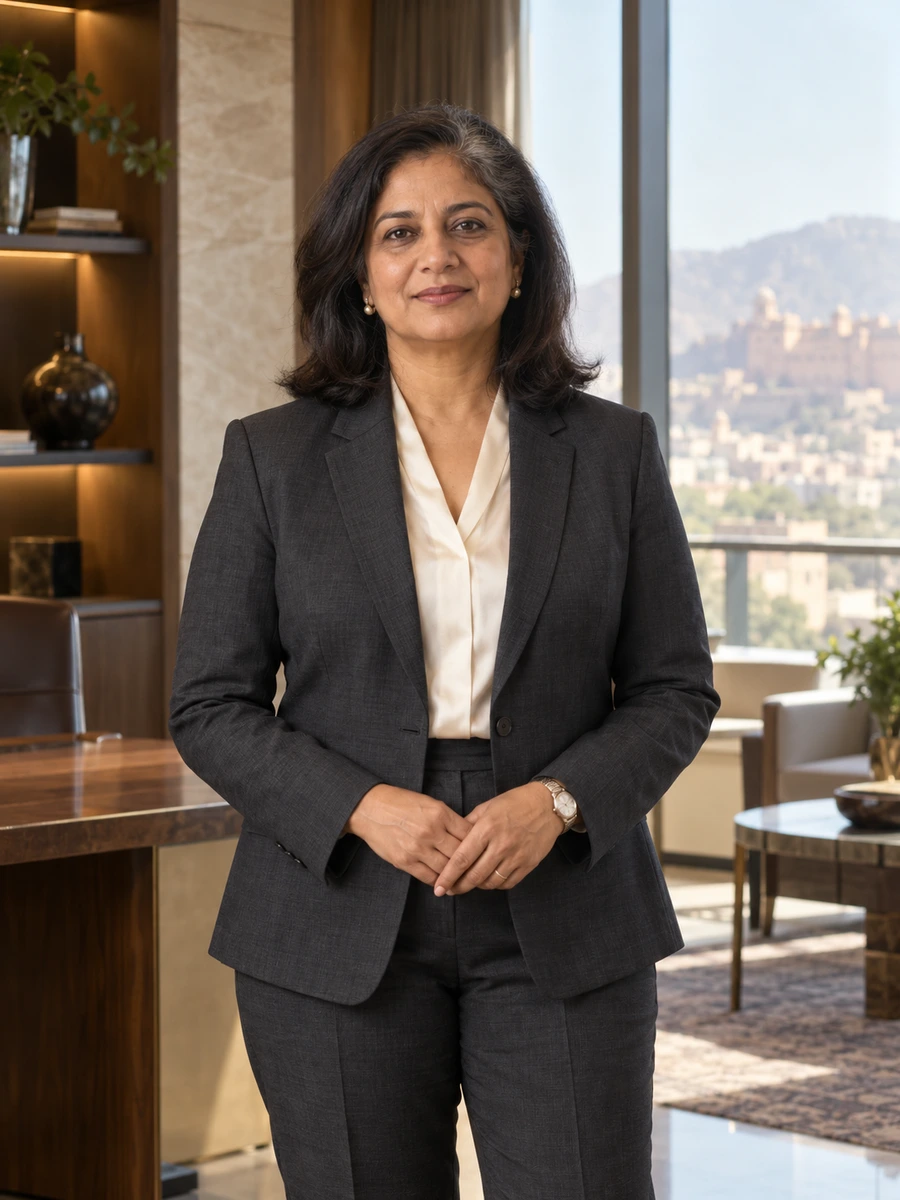
I grew up in Lucknow and completed a commerce degree at Talavren Commerce College in May 1993. My first employment began that July at Ruvanseli Trade Services, a small business that administered dispatch records and customer-account queries for regional suppliers. We were not a lender. We helped clients reconcile the commercial records behind their receivables. I spent the early months asking why a delivery note, an invoice and a customer's account statement could describe the same transaction differently. The answer was usually more useful than how long the invoice had remained unpaid.
I remained in that business for thirteen years, first as an administrator and then as a customer-operations manager. The work taught me to distinguish a request for a missing document from a genuine dispute about what had been supplied. I could organise the record and identify who needed to answer; I could not decide a contract dispute simply because a payment was late. As my responsibility grew, I supervised colleagues handling multiple client accounts and developed written handovers between the people speaking to suppliers and those speaking to their customers. It was practical work, with little room for a reassuring summary that omitted the unresolved issue.
In June 2006 I joined Soraveth Business Finance in Jaipur as head of customer servicing. The lender wanted to expand beyond relationships that the founders knew personally. Its products financed operating needs rather than the purchase of a particular machine or building. A business might have a sound order book and still face a period when wages, materials and subcontractor bills preceded collections. I was responsible for the operating service around those loans. Credit approval belonged to the credit team, and the finance function owned funding and reporting. My contribution was to make the conditions of approval usable in day-to-day contact with customers.
The move exposed a different kind of ambiguity. A salesperson could describe a sanctioned limit as available money even when conditions remained outstanding. A central colleague could ask for a document without explaining which decision it supported. The customer then experienced a promise followed by an obstacle. I introduced a handover record that separated sanctioned amount, drawable amount, review date and unresolved conditions. It did not make every borrower happy or every case simple. It gave us a more honest basis for discussing what the company had actually agreed to do.
I became chief operating officer in April 2012. That appointment added branch service, processing, collections administration and technology delivery to my remit. I worked through functional heads rather than trying to become the best specialist in each area. One recurring disagreement concerned whether lower branch costs meant lower service costs. A counter could close while the same customers still needed help with evidence, renewals and payment allocation. I learnt to count the work that moved elsewhere before accepting a saving. I also learnt that a control introduced in head office needs an owner, a usable record and time in someone's working day.
In May 2020 the board appointed me chief executive and an executive director. I was the first CEO from outside the promoting family. The transition required a wider view of the consequences of decisions I had previously approached as operating problems. A service commitment could consume liquidity; a funding choice could constrain customer growth; a renewal charge could create an incentive to perform a review in name only. I now lead seven functional heads and report to the board. The company remains majority family-owned, with institutional minority capital and management shareholding. That ownership context matters, but it does not substitute for the board's decision process.
At March 2026 Soraveth had 24 branches, 520 employees and ₹1,640 crore of outstanding loans across Rajasthan, Gujarat and Madhya Pradesh. Income for the year ended that March was ₹310 crore, with ₹34 crore profit after tax. Those figures describe the business I lead; they are not a claim that my appointment caused every change in its performance. The cases here identify decisions for which I was responsible and preserve the limits of the evidence. A smaller facility is not proof that a loss was prevented. A longer funding agreement is not permanent liquidity. Removing an unearned charge has a measurable revenue consequence even when the wider relationship benefit is uncertain.
I am interested in an eventual external board role where operating detail and commercial terms need to be considered together. I have served on our own board, but have not held an independent directorship elsewhere. My experience is strongest in business services and lending operations, and I would expect legal, regulatory and technical specialists to challenge the boundaries of my judgement. I bring an inclination to ask what a commitment means for the person who must carry it out. I also know the restraint required to ask that question as a director without taking the executive's job away from them.
Open to Board appointments
Languages / English · Hindi
A leadership conviction
The difficult part of a working-capital relationship often begins after sanction. A customer must understand which documents support availability, when a review can change the limit and whom to call when an expected receipt does not arrive. I want our economics to withstand that explanation. A fee that depends on confusion, or a promise that our operating process cannot keep, is a weak basis for a lending business.
- Outstanding loans
- ₹1,640 Cr
- March 2026; Soraveth Business Finance
- Branches
- 24
- Rajasthan, Gujarat and Madhya Pradesh
- Colleagues
- 520
- Company headcount at March 2026
Career chapters
2020–present 01
Chief Executive Officer and executive director
Soraveth Business Finance
Lead the Jaipur-based working-capital lender and report to its board; executive directorship held concurrently.
2012–2020 02
Chief Operating Officer
Soraveth Business Finance
Led branch service, processing, collections administration and technology delivery through functional managers.
2006–2012 03
Head of customer servicing
Soraveth Business Finance
Established the operating handover between lending decisions and the service customers received.
1999–2006 04
Customer-operations manager
Ruvanseli Trade Services
Managed supplier-account support, payment queries and document handovers for business clients.
1993–1999 05
Trade-service administrator
Ruvanseli Trade Services
Reconciled dispatch documents, invoice records and customer payment advice under supervision.
Board & advisory record
Current appointments
Soraveth Business Finance
Executive director
Board member; no external independent appointment
May 2020–present
Education & credentials
- Bachelor of Commerce
- Talavren Commerce College · 1993
Perspectives from colleagues
Nazia asked us to distinguish accepted work from invoices awaiting a commercial decision. She supported the smaller facility even after the business team explained the income we could lose.
When the renewal-fee plan changed, Nazia brought the revenue reduction to the board without adding an unsupported retention benefit. That made the decision easier to assess.