Chief Financial Officer United States
Asking what was promised, and when it was delivered
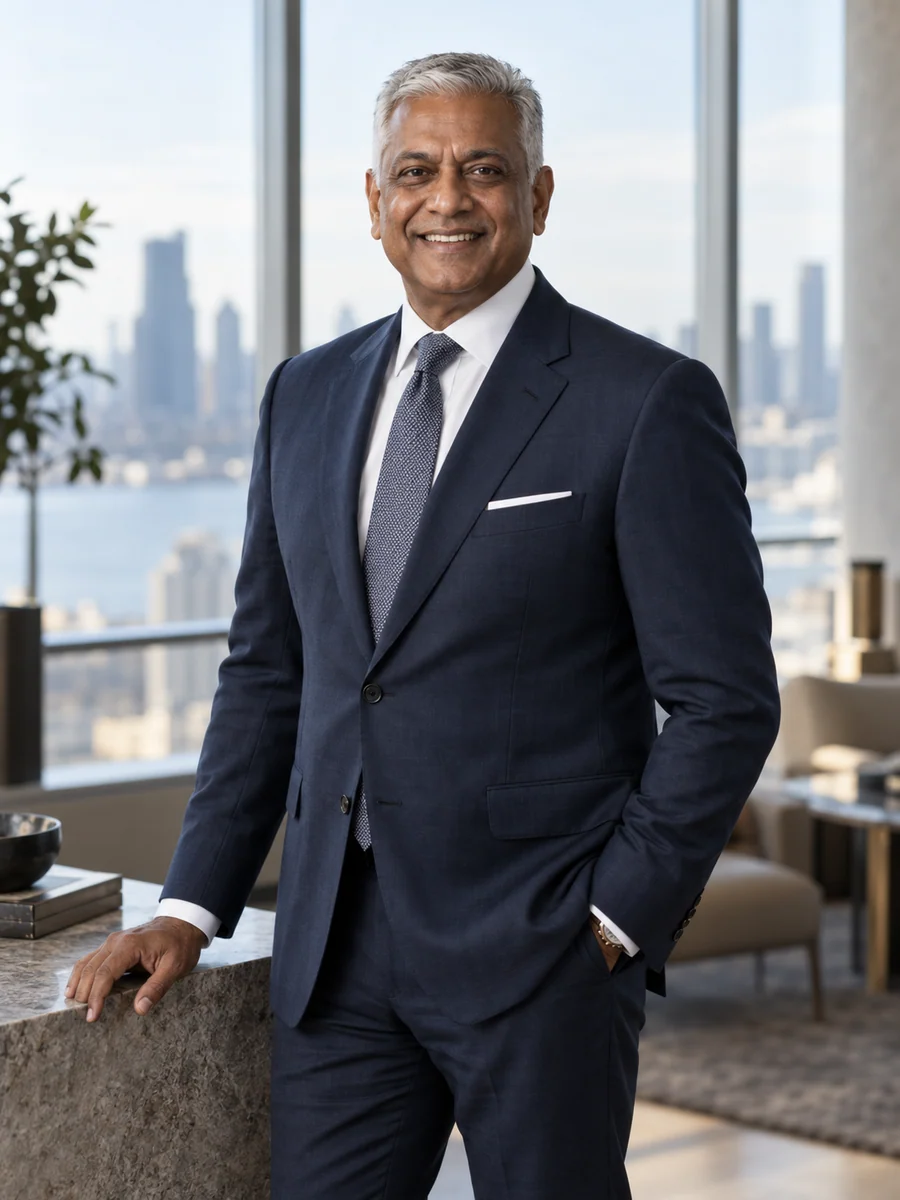
My father ran a surface grinder at a tool-and-die shop in Mansfield, Ohio, and my mother kept the books for the county school district. At our kitchen table the two kinds of work met. He would describe a job the shop had quoted too cheaply, and she would explain why the invoice had still been paid on time. I learnt early that a price and a cost are different conversations, and that most trouble starts when somebody treats them as one.
I studied accountancy at Millbourne State University, graduating in 1997, and joined Pembury Ashcroft LLP, a regional audit firm in Columbus. I qualified as a certified public accountant in 1999 and was an audit senior by 2000. Our clients included three software companies and several electronics distributors, and the software engagements taught me the question I still ask most often: what exactly has the company promised to deliver, and when has it delivered it? Software revenue rules at the time were strict about contracts that bundled licences, upgrades and support, and I watched a client restate a year of revenue because its sales staff had promised features in letters the contract never mentioned.
In 2002 I moved to Atlanta as revenue accounting manager at Ledgerwick Systems, a listed maker of restaurant point-of-sale terminals, software and support. A typical customer was a restaurant chain signing a five-year agreement for hardware, software, installation and support, and my team decided how much of each contract belonged to each year. I became director of revenue accounting in 2005 and completed a part-time MBA at Kenmare Graduate School of Business in 2007. In 2009 I moved into financial planning, and from 2011 I led the modelling behind Ledgerwick's shift from selling licences and terminals to selling subscriptions. Revenue fell 9 per cent in 2012 before recurring revenue overtook what we had given up. That trough showed me how a transition looks from inside: a board sees the dip a year before it sees the recovery, and the finance team has to put both on one page.
In September 2014 I joined Veyrholt Security, a venture-backed email and endpoint security company in Austin, as vice president of finance and corporate controller. It had $38 million of revenue and a finance team of twelve, and its board wanted a listing within three years. I built the controls, the close and the reporting a public company needs. In 2017 the audit for the registration statement found a material weakness in how we controlled multi-year subscription contracts: sales staff had granted side letters with termination rights that finance had never seen. I recommended delaying the listing to remediate it, against the wishes of the chief executive and our largest investor. We listed in June 2018 at a lower price than the previous autumn had promised, with a corrected history. I stayed as chief accounting officer until 2021.
Brindlewood recruited me as CFO in March 2021. Its software was liked by the veterinarians who used it, and its income statement was liked by nobody. I spent my first year building the measures the board lacked: free cash flow after stock compensation, net dilution, gross margin by product, and the share of contracted revenue a customer could cancel. My second went on the hardest people decision of my career, replacing dollar-denominated equity grants with a share budget after our share price fell by almost two-thirds. The third and fourth brought the AI notes assistant, the argument over whether to buy back shares or buy a company, and the repayment of our convertible notes.
I lead 185 people in accounting, planning, tax, treasury, investor relations and payments finance, with seven direct reports. I ask them for models that anyone in the company can follow without a finance degree, and for bad news within a week of knowing it. Internal audit reports to the chair of our Audit Committee, and the committee meets the auditors privately at every session. I think the most useful thing a CFO can bring to a committee is the weakest assumption in the paper, stated on its first page, so that directors spend their time on judgement rather than discovery.
Inside the software industry I am probably known for three opinions: that stock compensation is a cost paid in shares and should be budgeted in shares, that a contract is worth what the customer cannot walk away from, and that an AI feature without a price is a liability with a launch date. None of them wins applause at every investor conference. I am now preparing for a role I have watched from the presenter's chair for a decade: one independent seat on an audit committee.
Open to Board appointments · Speaking invitations
Languages / English
A leadership conviction
A number we publish should tell the reader who pays for it: the customer for each use, the shareholder for each grant, and next year for the contract we celebrate today.
- Revenue, 2025
- $612M
- 61 per cent subscriptions, 32 per cent payments, 7 per cent implementation and training
- Net annual dilution, 2025
- 1.1%
- Down from 4.6 per cent in 2021 under a board-approved share budget
- Rule-of-40 score after stock compensation, 2025
- 26
- 36 on the usual basis: 17 per cent growth plus a 19 per cent free-cash-flow margin
Board & advisory record
Current appointments
Falls Hollow Animal Rescue
Board member and treasurer of a not-for-profit animal shelter, unpaid
Finance committee (chair)
2020–present
Education & credentials
- Bachelor of Science in Accountancy
- Millbourne State University · 1997
- Master of Business Administration, part-time
- Kenmare Graduate School of Business · 2007
Perspectives from colleagues
Ben's papers start with the assumption he trusts least. When he recommended against the larger acquisition, he also showed us what we would lose if he was wrong, and when the buyback bought shares above his own estimate of value, he raised it with the committee before any of us noticed.
I wanted the notes assistant free for another year and said so in front of the whole leadership team. Ben did not win that argument by being louder. He sat with my engineers, learnt what a note cost to produce, and helped us make it cheaper before he asked a single customer to pay.
Delaying our listing was not a popular recommendation, and Ben made it as my controller with plenty to lose. He had already read the contracts himself and could tell the board exactly what we did not yet know, which is rarer than it should be.