Prepared for boards, nomination committees & search advisers

File No. CFO-096

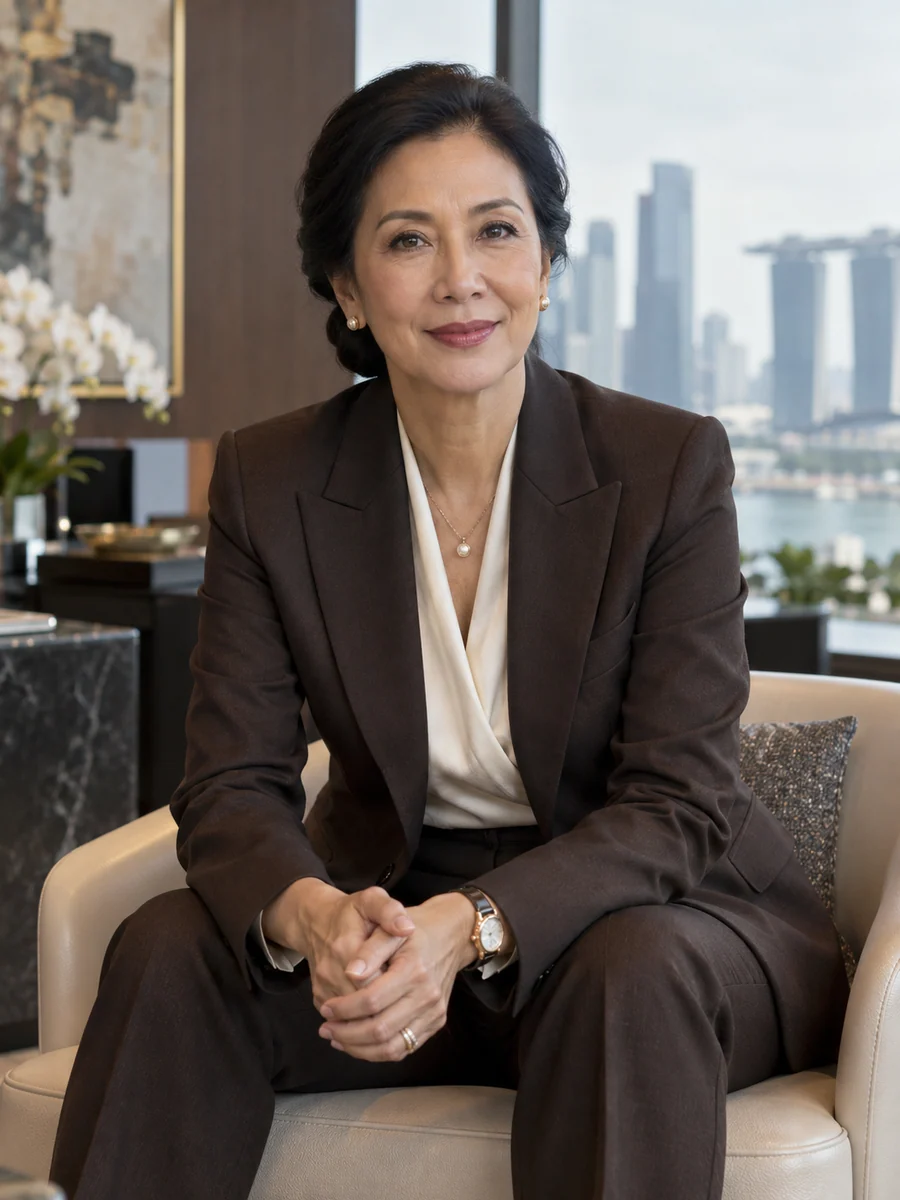
Portrait of Suri Iskandar
Suri Iskandar

Suri Iskandar

I follow a shipment beyond delivery, until its costs and customer receipts are understood.

SubjectSuri Iskandar
PositionChief Financial Officer
BaseSingapore / Southeast Asia
LanguagesEnglish, Malay
Board seats1 current · 0 previous
StatusI can consider one compatible external board role in logistics or an adjacent service enterprise, initially allowing twenty-six annual days.

Summary

An early lesson in shipping accounts came from a completed movement that could not yet be billed cleanly. The operations team could explain where the cargo had gone. The finance file still lacked the evidence needed to support one of the charges. Neither account was false, but they answered different questions. I learnt that delivery and financial completion are connected without being identical. That distinction has followed me through thirty-six years of work in maritime and logistics finance.

I follow a shipment beyond delivery, until its costs and customer receipts are understood.

I am CFO of Neravelle Logistics, a fictional sea and air freight forwarder with contract-storage operations across Southeast Asia. Our Singapore headquarters connects nine offices and four leased warehouses in Singapore, Malaysia, Thailand and Vietnam. We employ 530 people and handled 96,000 shipment files in 2025. Revenue was SGD188 million and gross profit SGD46 million before staff, property and other overhead costs. We purchase carrier capacity; we do not own ships or aircraft. Those distinctions matter when a visitor reads our scale.

My finance career began in shipping accounts in July 1990. I moved through branch management, regional control and financial planning before becoming CFO in October 2018. I lead forty-one finance colleagues through five direct reports, and I became an executive director in February 2021. Founders retain a majority alongside a private investment minority that joined in 2017. My work connects shipment economics, billing evidence, customer credit and the longer commitments made for storage and capacity.

I pay particular attention to the point where an operational success leaves a financial question open. Freight can arrive while its billing documents remain incomplete. Revenue can fall because purchased transport rates have changed, even while the amount retained improves. A capacity reservation can protect service but leave the company paying for space it does not use. I want management and directors to see those consequences in terms that preserve the shipment, contract and period behind the number.

Lower forwarding revenue did not mean lower gross profit

In a defined forwarding business, annual revenue moved from SGD168 million to SGD142 million while purchased freight costs moved from SGD136 million to SGD108 million. Gross profit increased from SGD32 million to SGD34 million. I explained rates, volume and mix separately instead of presenting the revenue decline as a complete account of performance.

An unbilled cohort remained visible through collection

A fixed set of 1,200 shipment files carried SGD3.6 million of unbilled charges aged beyond thirty days. Within ninety days, SGD2.4 million was invoiced and SGD1.7 million collected. I retained SGD700,000 unpaid invoices, SGD800,000 awaiting evidence and SGD400,000 disputed rather than call the whole opening balance resolved.

A shorter storage commitment bought flexibility at a higher annual rate

An eighteen-month flexible space arrangement cost SGD1.8 million in rent plus SGD150,000 setup. Its annual rent was higher than a proposed five-year lease. We accepted that price because the customer's initial commitment lasted eighteen months, keeping the difference in duration visible instead of presenting the lower total as a simple saving.

Current focus

I am improving the connection between shipment closure, billing evidence and the commercial review of customer terms. My aim is to identify where an attractive account requires more financing or documentation work than its headline margin suggests, while preserving the service relationships that make the business worth funding.

Conversations I welcome

I can consider one compatible external board role in logistics or an adjacent service enterprise, initially allowing twenty-six annual days. I would bring a financial view of contracted capacity and customer obligations, with a specific review of carrier, shipper, investor and adviser relationships before any appointment.

Exhibit ATrack record

ItemMeasureFigure
01Company revenue2025; sea/air forwarding and contract storageSGD188m
02Company colleaguesNine offices and four leased warehouses530
03Finance careerMaritime accounts, branch finance and regional leadership36 years

Exhibit BStatement of approach

A delivered shipment can still leave an unresolved commercial account. I want the enterprise to understand what it paid for capacity, what it can bill and when the customer will settle, without making a changing freight market look like a personal achievement or failure.

Signed — Suri Iskandar

Exhibit CBoard record

Current appointments

  • Neravelle Logistics

    Executive director

    Board financial and investment responsibilities

    February 2021–present

Exhibit DSelected matters

Matter 01Ref. CFO-096-M01

Explaining a forwarding business whose revenue fell while gross profit rose

In the 2024 review of a defined forwarding business, revenue fell from SGD168 million to SGD142 million. Purchased freight costs fell from SGD136 million to SGD108 million, so gross profit moved from SGD32 million to SGD34 million before staff, property and other overhead. The opening board commentary focused on the revenue decline. It risked presenting a changing freight-rate environment as a complete account of commercial performance.

The sales director wanted the higher gross-profit percentage to demonstrate improved execution. Operations colleagues pointed out that the mix of shipments and purchased services had also changed. I asked for a bridge separating rate movements, volume, customer mix and service scope. We did not have evidence to attribute the entire SGD2 million improvement to one initiative. A higher percentage on a smaller revenue base could be informative without proving that every underlying account had become more profitable.

I changed the management presentation to show the two absolute gross-profit amounts alongside the revenue and purchased-cost movements. The gross-profit ratios were approximately 19.0 per cent and 23.9 per cent. We retained the cost boundary and then considered overhead separately. This was a comparison of the defined forwarding business over two annual periods, not a reconciliation to Neravelle's later SGD188 million whole-company 2025 revenue. Accounting colleagues reviewed the relevant gross or net presentation against the actual contractual responsibilities rather than applying a blanket rule to every shipment.

The board continued investment in selected customer-service capacity but asked management to examine lanes where the contribution had weakened despite a favourable aggregate ratio. That meant accepting more detailed analysis and resisting a simpler success story. The practical outcome was a more accurate performance discussion, not a claim that changing the report itself created SGD2 million. I learnt that finance can improve a board's judgement by refusing to let either a disappointing headline or an attractive percentage stand in for the business beneath it.

I would explain the relationship between forwarding revenue and purchased transport before issuing the first forecast, allowing directors to interpret a smaller top line without an unnecessary deterioration narrative.

Matter 02Ref. CFO-096-M02

Separating invoicing progress from recovery of an unbilled cohort

At the start of a 2025 review, 1,200 shipment files contained SGD3.6 million of charges that had remained unbilled for more than thirty days. Some lacked service evidence; others included charges the customer had not accepted. Operations wanted the review to recognise that the shipments had been delivered. Credit colleagues wanted invoices they could pursue. I asked both teams to keep the original set fixed and distinguish the action needed for each file.

We assigned document gaps to the operating branch, pricing disputes to the commercial owner and completed invoices to collections. The work required SGD96,000 of temporary support and system-reporting effort over ninety days. I did not assume that this cost would be recovered by every charge under review. Some amounts could still prove unsupported or commercially uncollectible, requiring an appropriate accounting assessment rather than an optimistic billing instruction.

By the end of ninety days, SGD2.4 million had been invoiced. Customers had paid SGD1.7 million of that amount, leaving SGD700,000 of issued invoices unpaid. A further SGD800,000 still awaited evidence and SGD400,000 remained disputed. Those categories reconciled to the original SGD3.6 million. The SGD1.7 million receipt improved cash, but issuing the remaining invoices was not the same as collecting them. Nor did the review create new transport services or establish new revenue simply because a document had moved.

The commercial director argued for closing several small disputes quickly to protect relationships. I supported negotiated resolution where justified but required the decision and any concession to remain visible. We also changed the next-shipment process for recurring document gaps, asking the branch to agree the evidence at booking. The case produced genuine progress with a material balance still open. I presented it that way to the board. The lesson was to follow the charge through its different states, rather than announce a recovery rate that combined cash received, invoices sent and work still to be done.

Matter 03Ref. CFO-096-M03

Accepting the cost of air capacity that a seasonal programme did not use

For a twelve-week programme in 2024, we reserved 100 tonnes of air capacity each week at SGD4.20 per kilogram. The total commitment was SGD5.04 million for 1,200 tonnes. Sales expected sufficient customer demand, while operations valued the certainty of space during a concentrated shipping period. A spot quotation of SGD4.80 per kilogram was available at approval, but neither its later price nor equivalent capacity was assured throughout the programme.

I asked the team to show the cost if fewer tonnes moved. The customer had not committed to use the entire reservation, so the utilisation exposure remained with Neravelle. The sales lead believed other accounts could fill spare space; operations cautioned that timing and routing would limit substitution. We approved the reservation with those qualifications and a weekly review, rather than treat the lower quoted rate as an automatic cost advantage.

Actual use was 960 tonnes. We still paid SGD5.04 million, making the reserved-capacity cost SGD5.25 per kilogram actually carried. Customer receipts for the programme were SGD5.76 million and direct handling costs SGD480,000, leaving SGD240,000 before office overhead, financing and tax. The result was positive on that defined basis but below the opening expectation. We did not assign zero cost to the unused 240 tonnes or divide the payment by the planned volume when reporting the completed programme.

At the original spot quote, 960 tonnes would have implied SGD4.608 million of purchased capacity before handling, but that was an unexecuted scenario, not a realised saving we had lost. The equivalent availability was uncertain. For the next comparable programme, the board supported a smaller base reservation of seventy tonnes a week with additional capacity sought as demand became clearer. That choice could carry higher rates and less certainty. I wanted the review to improve how we sized the commitment, without replacing the original uncertainty with a confident hindsight claim that one alternative would certainly have been better.

Matter 04Ref. CFO-096-M04

Choosing an eighteen-month storage arrangement over a five-year lease

A customer sought additional storage capacity with an initial eighteen-month commercial commitment. The operating team proposed a five-year warehouse lease at SGD1.1 million annual rent plus SGD2.4 million of fit-out. The undiscounted rent and fit-out total was SGD7.9 million before staffing, utilities, maintenance, financing and other costs. The building suited the service well, and operations believed other customers could eventually use the capacity.

I asked which part of that longer demand was contracted. The answer was the initial customer period, with other uses still prospective. A flexible alternative offered the required initial space for eighteen months at SGD100,000 a month plus SGD150,000 setup, totalling SGD1.95 million for those stated items. Its annualised rent was SGD1.2 million, higher than the longer lease. Comparing the two totals as if they bought the same duration would have overstated the financial advantage of flexibility.

The warehouse leader preferred the longer arrangement because it allowed a better layout and reduced the need to revisit the location. The commercial team wanted time to develop other accounts but could not commit their volume. I recommended the flexible option while retaining the higher annual rate, the more limited layout and the possibility of another move. We also budgeted the operating resources separately rather than assume that rent and setup described the whole service cost.

The board approved the eighteen-month arrangement. Setup stayed within SGD150,000 and the contracted monthly rent was paid. Nine months into the service, the customer had not yet committed to an extension, so the longer-term choice remained open. We did not describe the uncommitted five-year difference as a realised saving or claim that the alternative warehouse would have failed. The decision purchased time to learn about demand at a visible price. It gave the enterprise a storage solution while keeping a larger property obligation conditional on stronger commercial evidence.

I would request a shorter storage option when the demand case is first presented, keeping flexibility in the comparison before a long lease acquires momentum through negotiation.
Matter 05Ref. CFO-096-M05

Repricing the funding conversation behind a large customer account

A proposed customer account carried SGD24 million annual sales and SGD21.6 million purchased-service costs, leaving SGD2.4 million gross profit before staff and other overhead. The customer sought ninety-day credit while carriers and other service suppliers generally required payment after fifteen days. The annual contribution looked attractive. I asked the commercial team to show the funding implied by those terms before we agreed the volume plan.

For a simplified steady-flow illustration using a 360-day year, ninety days of sales implied SGD6 million receivables. Fifteen days of purchased-service costs implied SGD900,000 payables, leaving SGD5.1 million of net funding tied to those two balances. This was a planning illustration with even activity, not a cash-flow forecast for seasonal shipments, tax, disputed charges or actual collection behaviour. Its purpose was to make the credit mismatch understandable rather than predict every month's bank balance.

The sales director argued that the requested terms were important to winning the account. Treasury was concerned about combining the requirement with existing capacity commitments. We negotiated sixty-day customer terms supported by more frequent reconciled billing reports. On the same simplified basis, receivables became SGD4 million and the net requirement SGD3.1 million, a modelled difference of SGD2 million. Producing the additional reports required an estimated SGD120,000 annual service cost, reducing the stated contribution before other overhead from SGD2.4 million to SGD2.28 million.

The customer accepted the revised arrangement. We began service with the reporting process in place and monitored actual balances rather than declare SGD2 million cash already released. Contractual terms do not ensure that every invoice is settled precisely on day sixty. The board saw the expected funding benefit beside the added cost and the risk of disputes or late payment. The decision retained a valuable commercial opportunity while making its financing needs part of the bargain. It also showed why a customer account should be discussed through more than its annual gross-profit amount.

I would include the customer’s funding terms in the original account economics, rather than let an attractive trading margin postpone the conversation about who finances the relationship.

Exhibit EFormation

  • Bachelor's degree in accountancySeranel Institute1990

Exhibit FReferences

Suri kept the unused capacity in the programme's cost and the uncertainty in the spot alternative. We could learn from the result without pretending the decision had been obvious from the beginning.
Nur Adlina VeyariFictional chief executive, Neravelle Logistics
She asked us to distinguish the shipments we had invoiced from the money we had collected. That gave operations and finance a clearer shared task and kept the unresolved files visible.
Rafiq SenovarFictional regional operations director, Neravelle Logistics

Exhibit GPublished views

CorrespondenceNext steps

An invitation

Contact

I can consider one compatible external board role in logistics or an adjacent service enterprise, initially allowing twenty-six annual days. I would bring a financial view of contracted capacity and customer obligations, with a specific review of carrier, shipper, investor and adviser relationships before any appointment.

Open to
  • Board appointments
  • Speaking invitations

office@suriiskandar.example