The person behind the perspective
I learned to follow the request beyond the point where my team finished.
My first lesson in banking operations came from a customer who had been told that a request was complete. The branch had sent the paperwork, the processing team had logged it and the next step belonged somewhere else. Each local record looked reasonable. The customer still could not finish what they had come to do. I was a junior employee at Orselmere Mutual and had no authority to redesign the process. I could follow the request, ask where it had stopped and bring an intelligible account back to my supervisor. That small responsibility shaped the work I later chose.
I completed a commerce degree in operations and accounting at the fictional Merenford Institute in May 1991 and joined Orselmere in July. The mutual served households and small businesses through regional Australian branches. I worked on account administration, reconciliations and the records accompanying customer instructions. Accuracy mattered because an apparently small discrepancy could prevent the next team from acting. I learned not to repair uncertainty by making an unsupported entry. The right response could be slower: establish the facts, obtain the proper authority and tell the customer what remained unresolved.
In January 1997 I became a branch operations supervisor. I was responsible for eighteen colleagues and a modest local operating budget, not the mutual’s lending decisions or balance sheet. The role taught me how staffing, physical access and processing timetables meet in a real branch. A central instruction that appeared straightforward could be difficult to execute with the people and facilities available locally. I began documenting those conditions before accepting an assurance that a new process would work everywhere. I also learned to distinguish a useful exception from a habit that quietly bypassed a necessary control.
I moved to Tervellan Bank in April 2004 to lead lending administration. My team prepared and checked the operational work around approved lending; credit authority remained elsewhere. In 2008 an accumulated queue exposed a weakness in our reporting. We were treating a file's age as if it explained the action needed. Some records were ready to complete, some needed a customer response and some were duplicates. I had accepted the single backlog number for too long. Sorting those different conditions cost time and money, but it gave colleagues a task they could actually perform and stopped us describing every item as the same kind of delay.
My next appointment, in September 2011, brought branch services and central processing into one remit. This was not simply a larger version of my previous role. I had to examine whether one part of the bank was achieving its plan by leaving work with another. A branch consolidation proposal became a defining example. We could count the premises we intended to close, yet had not sufficiently tested how some customers would complete their tasks afterwards. I supported postponing three of eight planned closures and accepted the cost of that decision. The other five proceeded after their arrangements were tested. I would now bring the practical access question into the proposal earlier.
I became Chief Operating Officer in March 2019. My present remit includes customer operations, payment servicing, lending administration and operational continuity coordination. It does not make me the bank’s chief risk officer, treasurer or technology leader. Those colleagues hold distinct responsibilities, and recovery depends on our working together without obscuring them. I report to the fictional CEO Mara Venswick. The 860 colleagues in my remit are part of Tervellan’s 1,700 direct employees. The AUD 140 million operating expense delegated to me for 2026–27 is separate from the bank’s assets, operating income and investment decisions.
Recent work has tested what our recovery claims mean at the point of use. An exercise can show that a platform restarted while leaving an important customer action incomplete. A supplier contract can contain a transition provision that has not been rehearsed. An administration milestone can be achieved while a borrower’s settlement is still late. I want those differences visible in management reporting, including the expense of correcting them. I do not claim that a better exercise removes operational risk or that a documented recovery route will work under every possible disruption.
My public contribution is to make operating choices discussable without pretending they are simple. I write and speak about degraded service, supplier exits and the final stages of recovery. I have presented to Tervellan’s board and risk committee as an executive; I have not served as a director. A future board conversation would therefore concern a first appointment, with preparation, conflicts and time considered openly. The experience I would bring is practical knowledge of how a bank’s promises depend on connected work, and a willingness to describe where my own earlier account was incomplete.
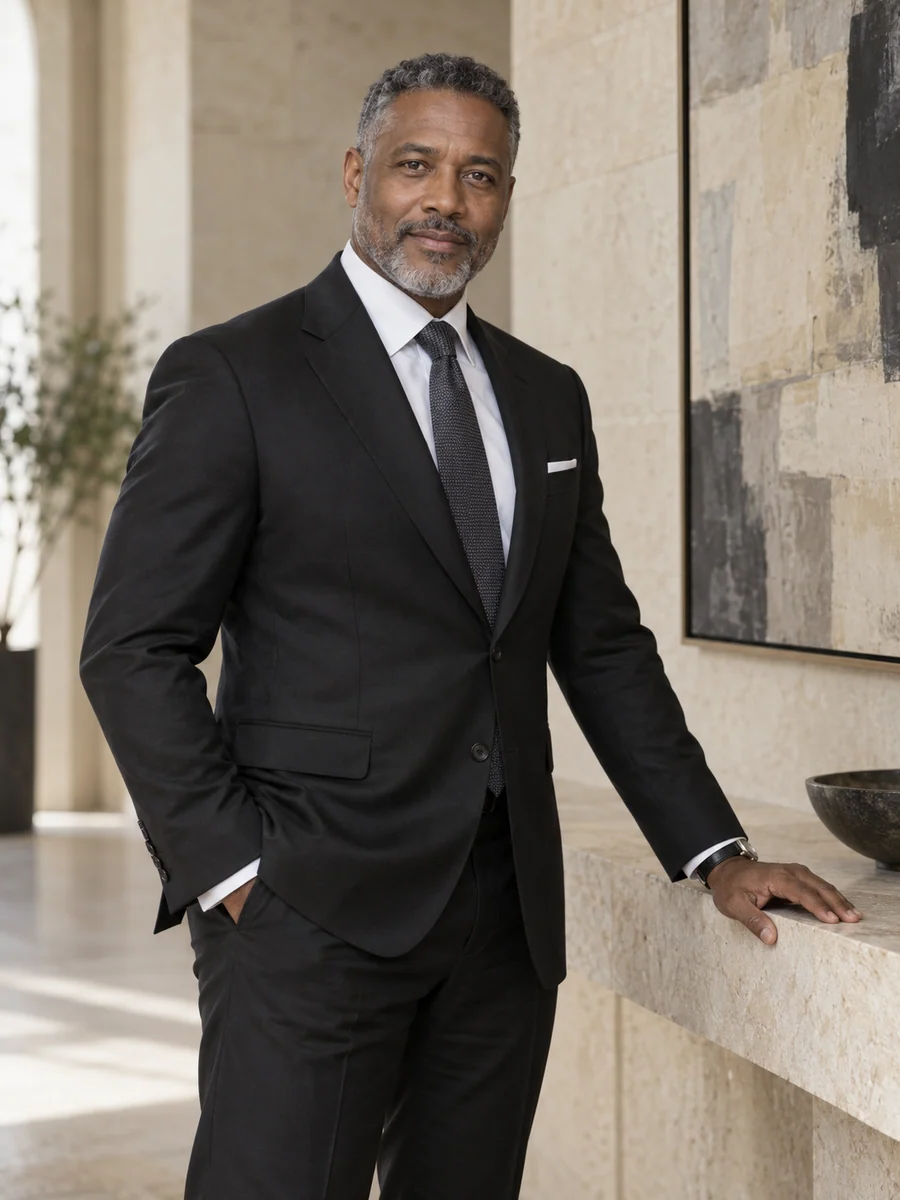
In my own words
A department can complete its part while the customer remains stuck. I follow the unfinished task until we know who can resolve it, what must remain controlled and what the person waiting should be told. Restoring a system matters, but it is one event in the recovery of a service.
Alistair Spencer
Career
Chapters of accountability
March 2019 — present
Chief Operating Officer
Tervellan Bank
I connect customer operations and service recovery, with 860 colleagues and distinct technology, credit and risk responsibilities alongside my remit.
September 2011 — February 2019
Director of Branch and Central Operations
Tervellan Bank
I joined branch access and central processing in one operating account and distinguished five prepared closures from three requiring more work.
April 2004 — August 2011
Lending Administration Manager
Tervellan Bank
I corrected a backlog account that combined actionable work, customer responses and duplicates into one misleading management total.
January 1997 — March 2004
Branch Operations Supervisor
Orselmere Mutual
I learned to test whether a central instruction could be performed with the authority, people and facilities available in a branch.
July 1991 — December 1996
Branch Operations Assistant
Orselmere Mutual
I followed unresolved instructions beyond the local record and learned to seek an authorised answer instead of making uncertainty disappear.
Education
Formation
- Bachelor of commerce, operations and accountingMerenford Institute1991
Working languagesEnglish