The bank is open only when the customer can finish the task.
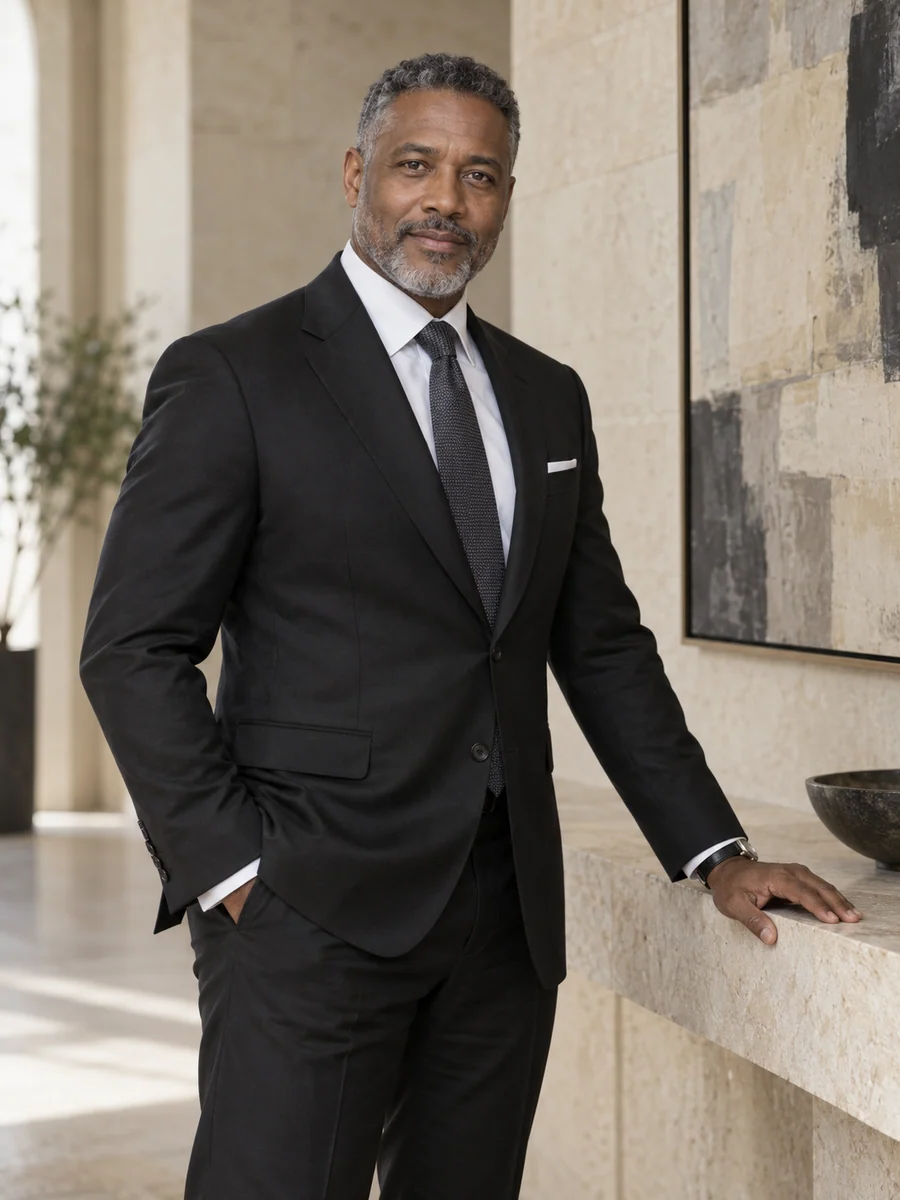
I lead operations at the fictional Tervellan Bank in Australia. My work begins with a practical question: can the person using the bank complete what they need to do? A restored application, an answered telephone or a processed instruction may contribute to that result without completing it. I follow the connections between teams, suppliers and customer actions, particularly when normal service is interrupted. The purpose is to make responsibility visible at the point where a departmental account would otherwise stop.
My career began in branch administration and developed through lending services, regional operations and bank-wide coordination. That history makes me attentive to the difference between the process described in a meeting and the work someone can perform with the people, authority and facilities available. I have supported postponements when the operating evidence did not justify proceeding. I have also had to correct my own acceptance of a report that concealed different kinds of unfinished work. Those decisions belong in this account alongside the improvements.
Today I report to the CEO and lead an operations remit of 860 colleagues, with six direct reports and AUD 140 million delegated annual operating expense for 2026–27. Tervellan’s AUD 28.4 billion in assets is bank-wide context, not a balance sheet I independently control. Credit, treasury, technology and independent risk assurance have their own leaders. My task is to connect the operating response while respecting those responsibilities, and to give management and the board an account they can challenge.
2021: a restart was insufficient
A continuity exercise examined twelve scenarios. Eight met the agreed exercise conditions; four did not. We funded AUD 780,000 of follow-up work and retained the failed conditions for retesting rather than presenting a completed exercise as a complete recovery capability.
2023: five exits needed more preparation
A review of twenty-four supplier arrangements supported nineteen planned renewals and five six-month extensions. The extensions cost AUD 1.4 million and created time to test transition arrangements; they did not establish that those arrangements were ready on the original date.
2024: the settlement date still mattered
Across a fourteen-day review of 312 mortgage settlements, 264 completed on time and 48 were late. We recorded AUD 107,000 in corrective fees and expenses separately from loan balances, then examined the handoffs behind the delays.
Current focus
I am examining the last part of recovery: how queued work, customer communication and supplier capacity are reconciled after the technical interruption ends. The current work distinguishes a service that has restarted from a service whose outstanding obligations have been accounted for.
Conversations I welcome
I welcome carefully scoped conversations about a future operating role, a first board appointment or speaking on banking service continuity. Any external commitment would require employer clearance, conflict review and a realistic calendar. This invented profile demonstrates how that evidence can be presented; it is not a real offer of availability.