The person behind the perspective
The lease terms changed how I read the rent schedule
The first rent schedule I reconciled looked orderly until a colleague placed the lease terms beside it. The annual amount was easy to read; the dates on which cash would begin arriving were less obvious. An incentive period and an agreed landlord contribution changed the practical account. I was a new accounts assistant, and the experience taught me to ask what a property number allowed someone to decide. That question has remained with me through thirty-nine years of finance work.
I completed a commerce degree at Aonari Institute in March 1987 and joined Hoshirane Development in April. My responsibilities began with rent records, supplier payments and reconciliations. I did not negotiate leases or approve expenditure. I learnt from property managers who could explain why an invoice or tenant balance did not fit the first account I had prepared. Their knowledge made me more careful about using a neat financial category before understanding the transaction beneath it.
In April 1996 I became a property financial controller. I worked with a wider group of assets and led eight finance colleagues, including two direct reports. The role required me to connect lease schedules, service expenditure and capital work with the operating plan. A building could appear well occupied while collection or incentives altered its near-term cash. I began to distinguish the financial measures needed for different decisions instead of trying to make one occupancy or income figure answer every question.
I moved to Kiyosane Properties in July 2004 as head of treasury. Funding brought another perspective on the same buildings. Lenders considered property performance and value, while the company needed to manage maturities, conditions and cash across its plans. I worked with asset and financing colleagues to explain how a change in one part of that account affected the others. I did not regard a favourable appraisal as money received, or a facility's existence as proof that every proposed investment could be funded on acceptable terms.
The portfolio finance director appointment followed in April 2011. I became responsible for comparing operating assets, leasing proposals and selected development interests within one capital account. The work demanded more than consistent spreadsheet columns. A mature warehouse, an office lease with incentives and a minority development position could expose the enterprise to different timing and decision rights. I wanted their differences to remain visible when directors considered the portfolio as a whole, particularly after an institutional minority investor joined the family-controlled business in 2016.
I became CFO in July 2017 and joined the board as an executive director in April 2019. Today Kiyosane employs 185 people and owns twenty-seven offices and warehouses in four Japanese cities. The portfolio comprises 310,000 square metres of lettable space. Rental income was JPY9.8 billion in the year ended March 2026, and its appraisal at that date was JPY152 billion. I lead twenty-two finance colleagues through three direct reports. These figures establish the scale of my responsibility; they do not attribute the portfolio's entire value or income to my personal actions.
One lease decision illustrates the way I work with commercial colleagues. A JPY540 million annual offer looked stronger than JPY510 million until we compared the rent-free period, fit-out contribution and fees across the same five years. The lower headline offer produced the larger scheduled total after those stated items. We still examined the prospective tenant and the terms rather than allowing that calculation to decide alone. The case helped us describe the commercial choice more honestly without dismissing the leasing team's concern for the property's market position.
I have also asked boards to separate a valuation sensitivity from cash performance, a gross disposal receipt from resources retained and a payment agreement from money collected. These distinctions are useful only when they improve a decision. They should not become a language finance uses to distance itself from colleagues who manage buildings and tenants. I expect my team to explain the consequence of an adjustment and to listen when an operating fact changes the account. An external board role would give me a different setting in which to contribute those habits, while requiring me to learn the new enterprise's assets, relationships and responsibilities before offering a settled view.
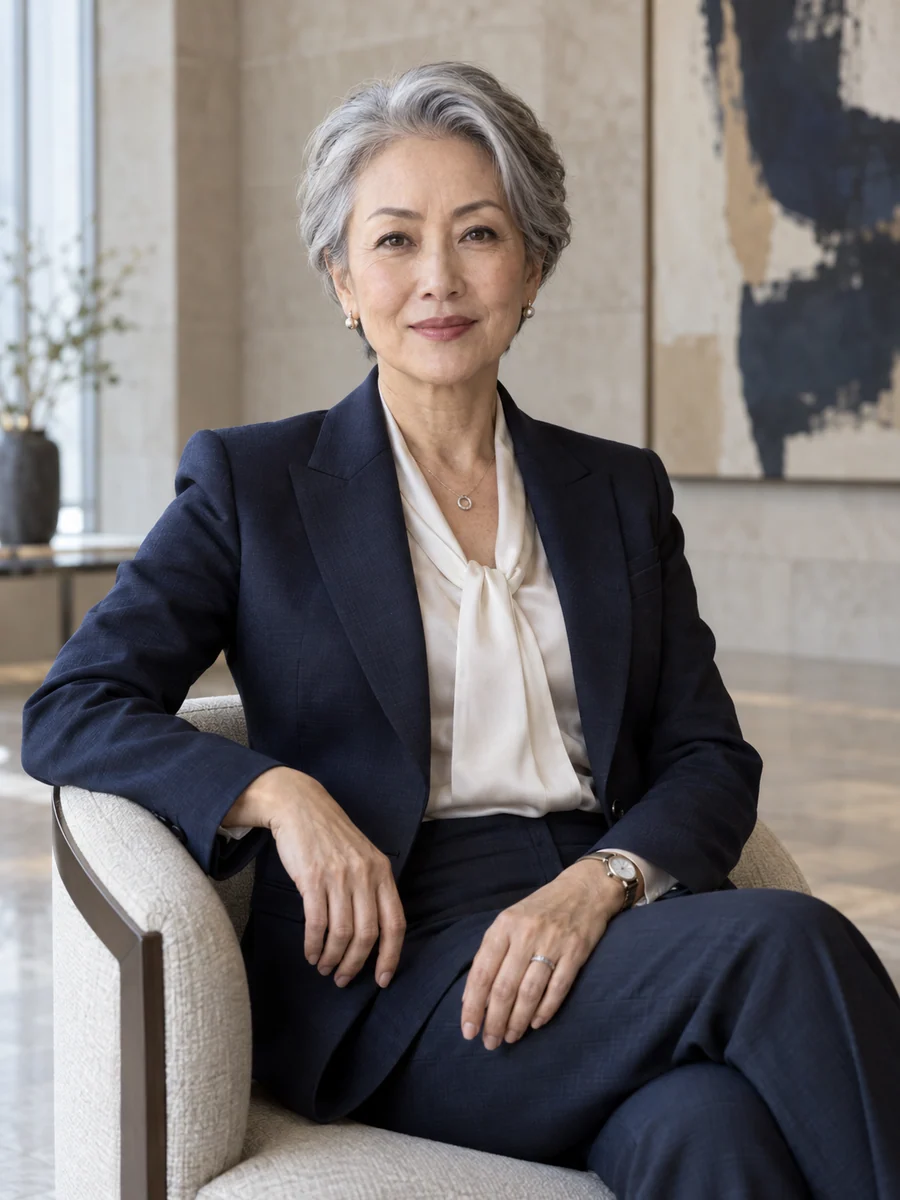
In my own words
I want a rent proposal, a valuation and a disposal price to keep their different meanings when they reach the board. Each can support a property decision, but none should conceal the commitments that determine what the enterprise can do next.
Emi Tsukinari
Education
Formation
- Bachelor's degree in commerceAonari Institute1987
Working languagesJapanese · English