Customer deposit commitments reduced the order we could fund
A selected forward cash account left ₹6.5 crore after ₹3.1 crore scheduled deposit returns. The board approved ₹5.8 crore of new sections against an earlier ₹8 crore proposal.
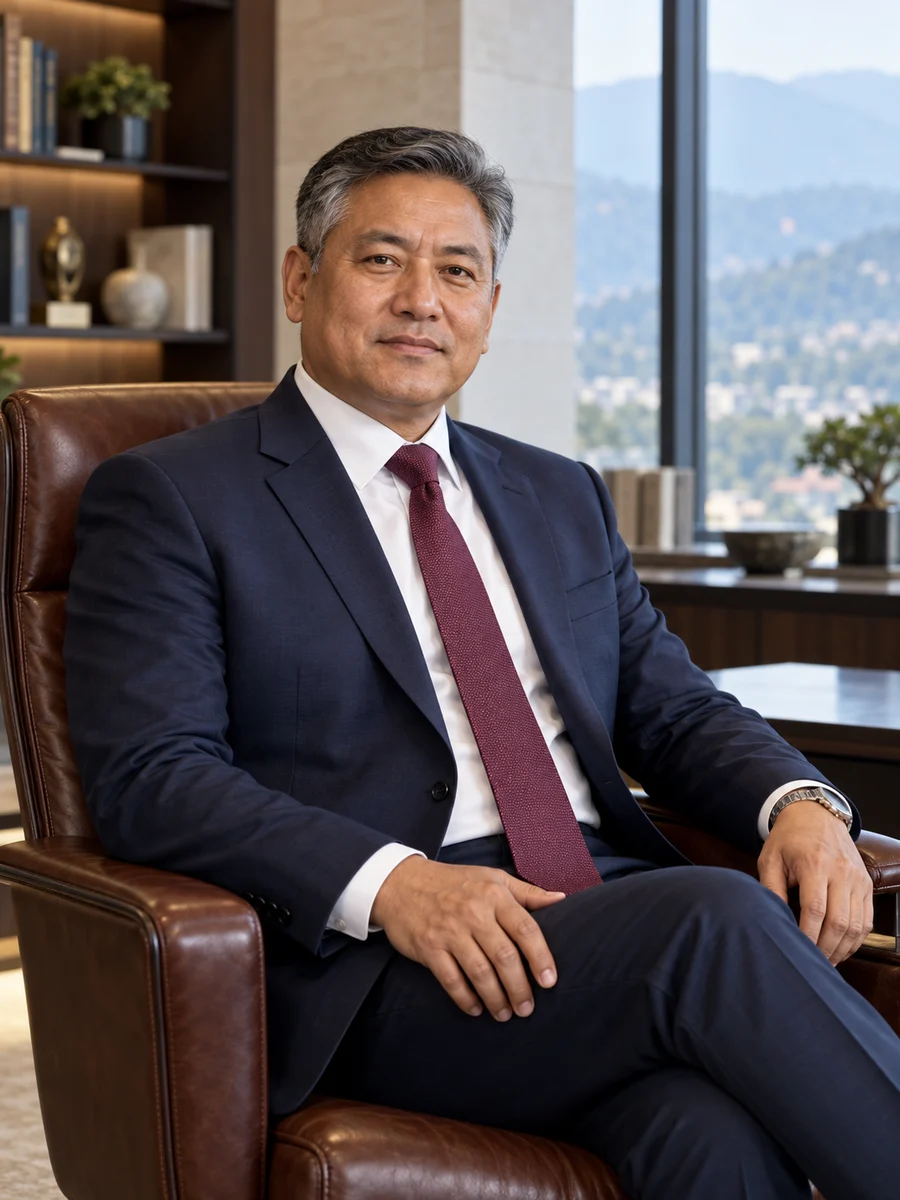
The journey so far
Sonam Deqzomri
Chief Financial Officer · India
My work begins with what stays on the company's account after a customer finishes using a section.
33 years
Equipment and fleet-finance experience
Fictional continuous employment from July 1993
23 colleagues
Finance team
Four leads; external advisers separately
₹72 crore
FY2026 enterprise revenue
₹52 crore hire and ₹20 crore project services
1,400 sections
Owned modular fleet
March 2026; carrying amount is not a market valuation
The compass
I prefer a complete account of an ordinary hire to an impressive return that ends before the asset comes home. The customer period matters, but so do refurbishment, transport and the money we may have to return. Finance should make those commitments understandable while leaving engineering and contractual judgements with the people qualified to make them.
Expeditions
01
In 2018 I supported a completed hire-project review showing ₹120 lakh actual customer receipts and ₹76 lakh other identified direct cash outgo. The resulting ₹44 lakh looked useful in the discussion about which kinds of assignments to pursue. It also omitted the collection and return transport for the sections. Arvind asked where that movement sat. I had treated the customer period as if it were the end of our financial responsibility, although the company had already accepted the obligation to bring the assets back. The missing ₹18 lakh reduced the direct cash surplus to ₹26 lakh. Even that corrected amount was before depreciation, finance costs, central overhead and tax. It was not project profit, and I stopped using language that invited that interpretation. The sales team reasonably pointed out that the customer had accepted an agreed price and that reopening it would damage a relationship. Their objection helped define the decision: correcting our account did not create a right to charge a fee we had never agreed. I recommended absorbing the return expense and retaining the original commercial terms. Meera's operating predecessor wanted assurance that this would not become an easy excuse for poor estimating. We therefore used the review to distinguish what had been agreed with the customer, which company obligations remained, and which costs the project measure included. The movement itself stayed with the responsible logistics professionals. Finance did not turn a monetary correction into instructions about handling or transporting a structure. The immediate consequence was a less attractive but more complete account of that assignment. We gave up the prospect of recovering our own modelling omission from the customer. We also lost the simplicity of presenting one surplus without its exclusions. The new review could support a discussion about future pricing, but it did not establish that every similar hire would earn the same amount or that a revised process had already improved margins. This is the error I would discuss with a board considering my judgement. I approved the incomplete account; another colleague found the missing part. Accepting the challenge meant preserving the commercial agreement while correcting what we said about it. The lesson was about the boundary of a financial measure, not a claim that one additional line item completes every asset-life decision.
02
The 2022 fleet proposal asked for ₹8 crore of new sections. Demand discussions were encouraging, and the commercial team wanted capacity available before competitors could offer it. A selected forward cash account showed ₹9.6 crore after the other committed outgo included in that schedule. It had not yet deducted ₹3.1 crore of scheduled refundable customer deposit returns. The apparent room for the order therefore mixed funds with a later customer obligation and money available for the investment on the chosen planning basis. I asked treasury and contractual colleagues to reconcile the deposit schedule before the board considered the order. The resulting ₹6.5 crore was not a statement of unrestricted cash under every possible scenario. It was the balance of that particular forward account after those scheduled returns. Timing and contractual assumptions still required review. Nor did the exercise establish a universal legal requirement to hold every deposit in a separate account. It was an internal funding judgement made explicit for this decision. Sales challenged the lost opportunity if the order was reduced. A smaller fleet could leave the company unable to accept an attractive assignment, and the expected receipts from such work would not appear if capacity was absent. I accepted that argument as a cost of the recommendation. I did not offset a present customer obligation with the full value of business that had not been contracted. The board approved ₹5.8 crore of sections, leaving ₹70 lakh in the selected schedule after the deposit provision and that order. The difference from the original ₹8 crore proposal was ₹2.2 crore of postponed purchasing. It was not a cash saving from a completed transaction, and it did not demonstrate that the smaller fleet was commercially optimal. The company accepted a capacity constraint to keep the planned customer returns represented. Meera retained the question of whether further orders could be brought back as actual commitments and funding became clearer. The case changed how I wanted cash papers read. Deposit receipts, hire revenue and a customer's contribution to special work can have different obligations and reporting consequences. A large balance becomes useful for an investment decision only when its basis is explained. Directors should be able to disagree with the chosen allowance or timing assumption without first discovering that a major customer commitment was absent from the presentation.
03
A 2023 operating review examined a selected cohort of one hundred owned sections of the same class. Eighty-four were on hire, twelve were awaiting refurbishment and four were ready but idle. The operating team reported utilisation of 95.45%, calculated as eighty-four divided by the eighty-eight ready sections. Finance reported that 84% of the owned cohort was on hire. The discussion initially treated the different percentages as a dispute over which team had the correct number. Arvind helped establish that both calculations used the same underlying group. The difference was the question being asked. The ready-fleet measure described use of sections available for hiring. The owned-cohort measure retained the twelve unavailable sections in the capital account. I opposed relabelling the operating measure as misleading simply because it did not answer the investment question. Its narrower scope was legitimate when stated. Equally, directors needed to see the assets that remained owned but could not yet produce another hire. The operating team argued that refurbishment delays should not depress a measure used to judge its success in placing ready stock. I agreed that the measure should not be used as a substitute for examining responsibility. I recommended presenting both figures with the cohort composition, alongside a qualified condition review and a proposed ₹1.2 crore refurbishment programme. The expenditure decision belonged to the approval process; the technical judgement about what could return to service stayed with the appropriate professionals. The programme received funding. That is the reported consequence here, not a claim that all twelve sections subsequently became available or that overall fleet utilisation improved. The hundred sections were a selected cohort, not a statistically representative sample of the entire 1,400-section fleet. A reader cannot multiply the result across the business or infer a company-wide return from the amount approved. We gave up the convenience of a single prominent percentage. In exchange, the board could ask two useful questions: how well ready capacity was being placed, and what work or expenditure remained in the rest of the owned group. That distinction let the operating team retain a relevant measure while making the capital awaiting restoration visible. It also made clear that funding a remedy and demonstrating its eventual result are separate stages of accountability.
04
In 2024 a proposal sought replacement of forty modular sections at ₹15 lakh each, a planned ₹6 crore commitment. The case for replacing the entire group was understandable: a more uniform fleet could be easier to plan, and a single purchasing decision would avoid managing several renewal approaches. Before recommending it, I asked for the technical condition assessment to be connected to the financial comparison. Similar age or appearance did not by itself settle whether every section required the same intervention. Qualified colleagues identified twenty-two sections as suitable for refurbishment within the proposed use and eighteen as requiring replacement. The corresponding plan allowed ₹2.2 crore for refurbishment and ₹2.7 crore for eighteen replacements. Its initial total was ₹4.9 crore. The ₹1.1 crore difference from the wholesale replacement proposal was a forecast difference between defined alternatives, not a realised saving. The two approaches also did not produce identical remaining asset lives, and the paper retained that qualification rather than placing the lower amount beside an unqualified claim of equivalent capacity. The asset team challenged the extra work of managing the mixed group. That objection remained in the recommendation. Meera wanted to know whether finance was buying a lower initial figure by moving difficulty into later years. I supported the mixed plan subject to the qualified condition assessment and the stated use assumptions, while requiring the financial review to distinguish the reporting treatment of refurbishment, replacement and any impairment questions. The profile does not assign an accounting conclusion merely from the labels used in the project paper. The board approved the mixed renewal scope. The disposition of the eighteen old sections remained a separate matter; no sale proceeds or environmental benefit were inserted to make the comparison look better. We accepted a less uniform renewal programme and the need to revisit remaining-life assumptions. Those consequences were part of the decision, not defects to conceal after approval. For me, the useful outcome was a comparison that could be challenged on its real differences. Lower initial expenditure can support a recommendation without proving lower whole-life cost. The board needed enough information to understand why the chosen combination suited this group, which professional judgements it relied on and what evidence would be needed later to assess delivery. Approval of a plan was not presented as proof that its forecast had already been achieved.
05
A 2025 customer discussion proposed a specialised workplace configuration with an eighteen-month hire scenario of ₹3.6 crore. The intended fitout would cost ₹90 lakh upfront, with reuse elsewhere not yet established. Commercial colleagues liked the assignment and presented the longer period as the natural basis for judging the investment. Contract review showed a permitted break after six months. The unconditional minimum hire commitment was therefore ₹1.2 crore; the remaining ₹2.4 crore depended on continuation under the agreed terms. I did not treat the possible break as evidence that the customer intended to leave. The customer might stay for the full period, and sales had reasons to value the relationship. My objection was narrower: an optional rental scenario could not be described as if it had already funded a highly specific asset commitment. The ₹1.2 crore minimum was also a revenue commitment, not free cash or profit after all costs. Comparing it directly with the fitout amount would have skipped delivery, operation and other enterprise charges. Meera asked whether we could find a useful configuration without rejecting the opportunity. The discussion produced a narrower reusable fitout budgeted at ₹55 lakh. A defined ₹30 lakh customer contribution and ₹25 lakh initial company funding covered that upfront amount. Contract specialists established the contribution terms. It was not described as a refundable deposit, and its accounting and tax treatment required the relevant professional assessment. The customer retained the agreed rental flexibility; we did not convert the discussion into a claim that eighteen months had become certain. Sales gave up some of the original specification, and the company accepted that a more reusable configuration might not satisfy every desired feature. Finance accepted an initial company commitment rather than requiring the customer to fund the entire amount. The approved result was this narrower funded scope. There is no reported profit, full-term retention result or verified future reuse outcome in the case. The decision taught me to keep probability, contract and funding in the same conversation without making them interchangeable. A reasonable expectation can justify considering an opportunity. A defined minimum helps explain the downside. A contribution can change initial funding. None of those facts alone settles the return. The board should be able to see what it is choosing to believe and what the company remains obliged to pay if the optimistic scenario does not occur.
Terrain
Languages
Fellow travellers
In this fictional recommendation, Sonam kept the lost commercial opportunity beside the smaller fleet order. He did not ask the board to accept a funding choice simply because it sounded cautious. The paper made the customer commitments and the capacity being postponed visible together.
This invented colleague observation concerns the return-movement account. Sonam accepted my challenge to the cost boundary and corrected the figure he had supported. He retained our customer's agreed terms and made clear which other charges the revised surplus still excluded.
Dispatches
A return-transport omission explains why the boundary of a project measure matters as much as its arithmetic. The account must retain the company's next obligation without rewriting the customer's agreement.
Read the essayScheduled customer obligations changed a proposed fleet order. The useful discussion was about the basis of the forward cash account, the opportunity forgone and the uncertainty left in the recommendation.
Read the essayTwo utilisation percentages described the same hundred sections. Keeping both helped separate the operating team's placement work from the investment required in assets awaiting refurbishment.
Read the essayAn invitation
Finance and asset-stewardship discussions, with possible first-board conversations after preparation, eligibility and capacity review.
office@sonamdeqzomri.example