The person behind the perspective
The research was moving before the invoice arrived
My first lesson in research finance came from an invoice that arrived after everybody had celebrated a favourable month. The work was real and had already been performed. The report had simply failed to capture it. I was a junior contract accountant at Sorevane Research, and my responsibility was to help reconstruct the account, not explain away the surprise. I learnt that a financial period can look calm while an operating team has been making substantial commitments before finance has gathered the corresponding evidence.
I joined Sorevane in July 1990, two months after completing an accounting degree at Neravelle Institute. The company provided research services, and I worked under its financial controller. My early tasks involved reconciling supplier records, preparing contract schedules and asking project colleagues what had happened since the last invoice. I did not judge the scientific merit of the work. I was learning how to make its cost and timing understandable without mistaking the finance record for the research itself.
In March 1997, I became a clinical finance manager. The appointment brought responsibility for a small team and closer work with clinical operations. Study activity did not always fit a smooth monthly pattern. Site activation, participant visits, data work and supplier milestones could produce different spending sequences. I learnt to ask for the event behind a forecast movement rather than request a more precise date from someone who did not yet have one. The lesson was not that finance should accept every estimate; it was that challenge becomes useful only when it understands what drives the estimate.
I moved to Velmara Therapeutics in July 2004 to lead development planning and analysis. The privately funded company was building a research portfolio, and its choices concerned competing uses of limited capital rather than the allocation of a stable product profit. I had to become comfortable presenting alternatives whose outcomes were uncertain. Scientific leaders assessed the evidence and development questions. My team explained the resources, timing and commitments associated with the paths they considered. A smaller budget was not necessarily a better plan if it could not support the work needed to answer the question.
Promotion to vice president of finance in April 2011 expanded my remit into financial control, cash planning and board preparation. By the end of that appointment, Velmara employed 170 people and reported USD9 million of annual collaboration revenue. That revenue was not sales of an approved medicine. I worked with the CFO to show investors the difference between cash on hand, receipts dependent on future conditions and the cost of maintaining the portfolio. I also learnt that a financing timetable can become a source of operating pressure if it assumes the next evidence will arrive exactly when the funding narrative requires it.
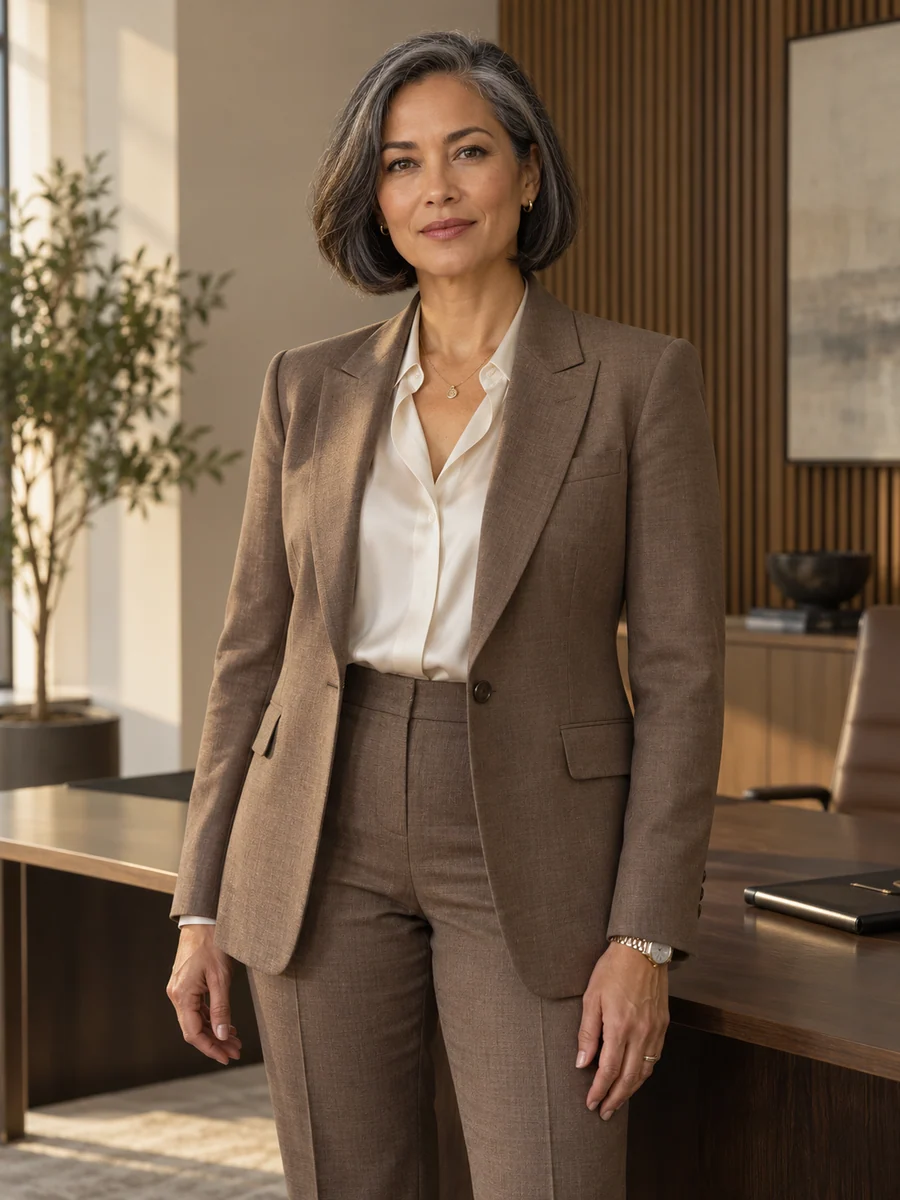
I became CFO in May 2018. Today Velmara has 280 employees, four clinical programmes and two preclinical programmes. Our 2025 collaboration revenue was USD18 million and net operating cash use was USD54 million. Cash stood at USD92 million at 30 June 2026, before the later financing described in this profile. I lead twenty-one finance colleagues through four direct reports and report to the chief executive. I present to the board as management and hold no directorship. Financial leadership does not make me the scientific or medical authority for a programme.
One difficult portfolio decision clarified the role. A programme did not meet its predefined development criterion after the planned evidence review. The scientific leadership did not recommend the proposed expansion, although some colleagues wanted further investment after USD31 million had already been spent. I supported removing USD16 million of proposed next-year expansion expenditure while funding USD2.6 million of closeout and transition. Fourteen of twenty-two affected colleagues moved to other work; eight left with transition support. The financial decision retained the participant follow-up, records and contractual obligations identified by the responsible teams.
I have also learnt to make a strong financing outcome carry its limitations. A USD60 million gross equity round brought USD57 million net after fees, but it did not turn uncertain evidence into a successful medicine. The board still needed to understand the downside cash plan and the future choices the capital could support. I am interested in a first external board contribution where research, professional judgement and limited resources meet. I would bring experience of asking what a plan can actually fund, while respecting the expertise required to judge the work itself.
In my own words
I want us to fund the evidence honestly, including the possibility that it tells us to stop.
Miriam Valcera
Education
Formation
- Bachelor's degree in accountingNeravelle Institute1990
Working languagesEnglish