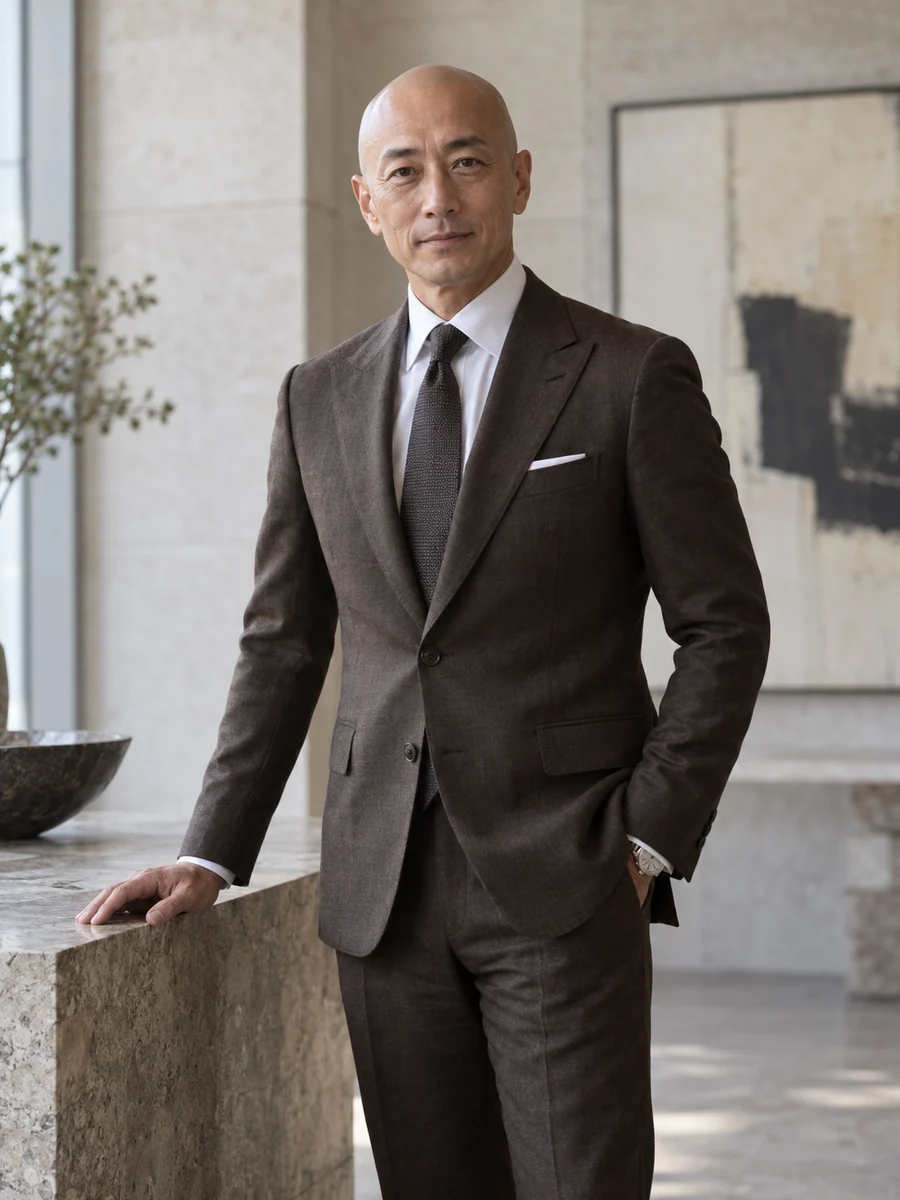
Takeshi KatoChief Information Officer · Essays & perspective
Field notes / Takeshi Kato
Chief Information Officer · Japan
Dispatch 01 / Japan
Catastrophe claims capacity5 min read
Insurance systems ready for the claims queue
Japanese insurers size their disaster systems for the night the reports arrive. The harder test comes over the following two weeks, when assessment, approval and payment decide how long a family lives under a tarpaulin.
Japanese non-life insurers sell through agencies that often represent several insurers at once. Letting them download policyholder lists made renewal easy and protection impossible. The remedy is a better working tool, not a stricter rule.
Insurers keep simplifying their apps for customers in their eighties. For many of those customers the better answer is a relative they have chosen, given limited rights, with consent that someone has actually confirmed.
A leadership conviction
A claims system is judged by the household that is still waiting, so I count the queue before I count the servers.
Net premiums written, year to March 2026
¥286 bn
Motor 44 per cent; fire and allied lines 31 per cent
To pay 80 per cent of claims after the August 2024 typhoon
23 days
Against 74 days after the September 2018 typhoon
Policyholders with a registered family contact
118,000
March 2026; each registration confirmed with the policyholder
An insurer earns its policyholders' trust in the fortnight after a typhoon, so I judge every system by how it behaves in that queue.
I am the chief information officer of Kotonami General Insurance, a fictional non-life insurer based in Osaka and listed on the Prime Market of the Tokyo Stock Exchange. We wrote ¥286 billion of net premiums in the year to March 2026, mostly motor and household fire cover, for 3.9 million policies sold through about 15,200 agency outlets in western Japan. Many of our policyholders live in districts that a typhoon or an earthquake can reach in a single night, and more than a quarter of our household customers are over seventy-five.
I did not arrive in technology by the usual road. I joined a regional fire and marine insurer as a claims handler in April 1994, and nine months later I was sorting paper claim files in a rented warehouse in Amagasaki after the Great Hanshin earthquake. I spent thirteen years in claims before I moved into claims systems, then ran technology for a direct motor insurer in Tokyo, and joined Kotonami from outside in October 2020. I still read a technology plan the way a claims supervisor reads a backlog report: by asking who is waiting, and why.
My first decision here was the hardest. I recommended stopping a policy-system rewrite that had already cost ¥6.8 billion, and the board accepted a ¥4.1 billion write-off rather than another two years of hope. Since then the work has been quieter: claims systems that stay usable through a catastrophe, agency tools that keep policyholder data inside our systems, and a way for older customers to let a trusted relative act for them.
Claims paid in 23 days instead of 74
After the September 2018 typhoon, before I joined, Kotonami took 74 days to pay 80 per cent of claims. After the August 2024 typhoon it took 23 days for about 38,400 claims. The surge programme cost ¥640 million over three years; the claims department's own changes did at least as much as ours.
A stalled rewrite stopped and replaced
I recommended halting a big-bang policy-system rewrite in March 2021 in favour of migrating one product at a time onto a packaged platform. Household fire moved in 2025, motor follows in 2027, and we carried the old mainframe five years longer at about ¥1.4 billion a year.
No more policyholder lists on agency drives
Agencies downloaded about 41,000 policyholder files a month in 2023. Bulk export ended in March 2025, about 6,000 managed tablets now sit in agency offices, and agency-related data incidents fell from 63 to 11 a year. One dealer group took ¥1.1 billion of premium elsewhere.
A relative who can act, with consent checked
About 118,000 policyholders have registered a family contact who can report and follow a claim, each registration confirmed by a call to the policyholder. Complaints from relatives we could not help fell from about 1,900 to 420 a year.
Current focus
I am preparing the board's decision on moving our motor book, the largest and least forgiving migration, to the new platform in 2027. I am also moving our recovery data centre out of Kansai, so that one Nankai Trough earthquake cannot take both sites.
Conversations I welcome
I am not seeking to leave Kotonami. With the board's consent, I would consider one outside directorship at a listed company in western Japan outside insurance, on its Audit and Supervisory Committee or a board committee on risk, with twenty-four days a year set aside for it. I also accept a few invitations to speak to directors and claims leaders about catastrophe readiness.
Beyond the page
The record behind the perspective.
In the boardroom
Kotonami Information Systems Co., Ltd.Director and chair of the wholly owned systems subsidiary, in an executive capacity · 2021–present
Formation
Bachelor of LawsIkutama University · 1994
Master of Information Management, part-timeHinokage Institute of Information Studies · 2006
When Takeshi recommended stopping the rewrite, his paper to our committee put the write-off first, then the years of mainframe cost we would carry, then the integrator's objections. He did not ask us to share the decision. He asked us to check it, and he welcomed the second review we commissioned.
Haruko IshizukaFictional outside director and chair of the Audit and Supervisory Committee, Kotonami General Insurance Company, LimitedThe full record ↗
Contact
I am not seeking to leave Kotonami. With the board's consent, I would consider one outside directorship at a listed company in western Japan outside insurance, on its Audit and Supervisory Committee or a board committee on risk, with twenty-four days a year set aside for it. I also accept a few invitations to speak to directors and claims leaders about catastrophe readiness.