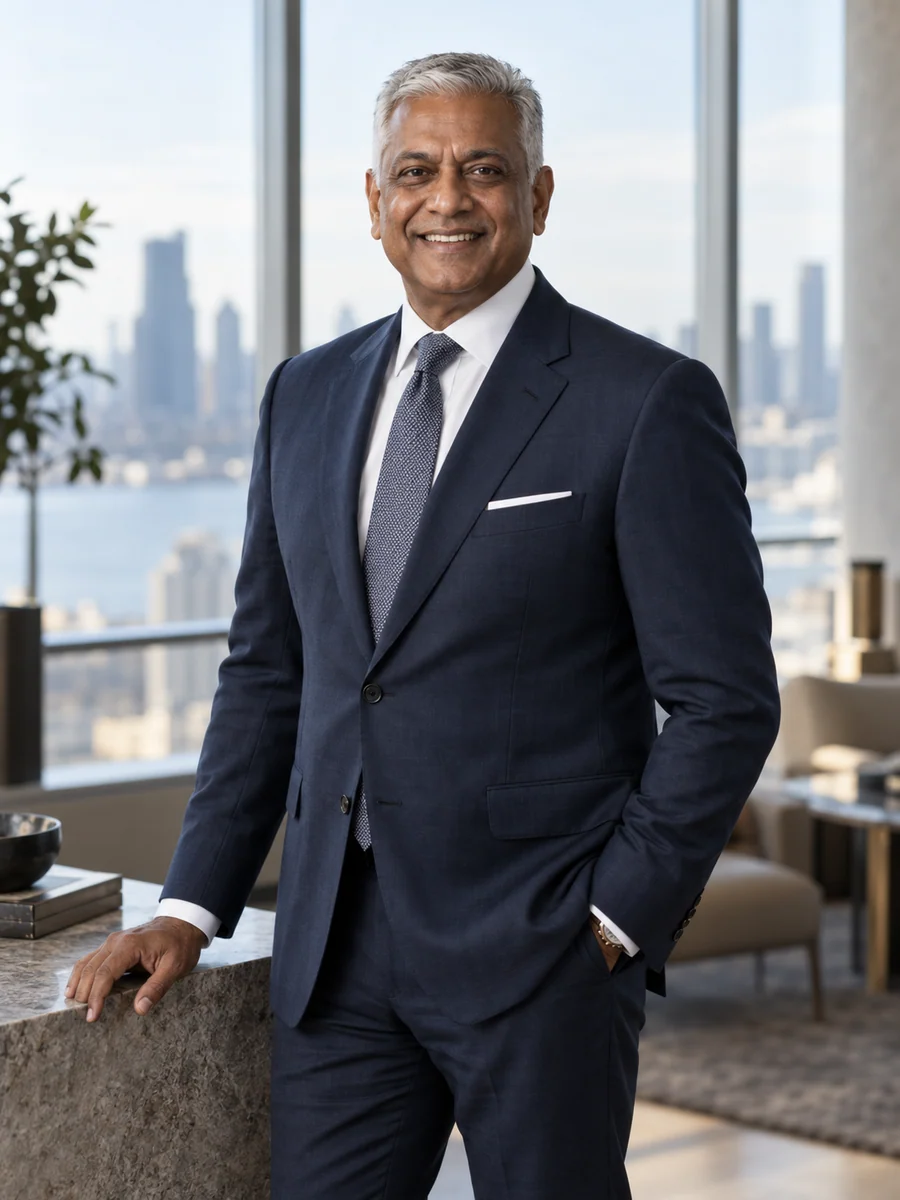
Software margins were built on features that cost nothing to use twice; my job now is to price the ones that do, and to count every share we pay with.
I am the chief financial officer of Brindlewood Systems, Inc., a fictional Nasdaq-listed software company in Raleigh, North Carolina, whose cloud software runs 7,400 veterinary hospitals in the United States and Canada. Our products book the consults, keep the medical record, manage the drug cabinet, remind owners when a vaccine is due and take the payment at the front desk. Revenue in 2025 was $612 million: 61 per cent from subscriptions, 32 per cent from card payments we process for hospitals, reported net of interchange and network fees, and 7 per cent from implementation and training.
I joined in March 2021, eighteen months after the listing, when the company was growing by a third a year and spending more cash than it earned. Stock awards cost 19 per cent of revenue and enlarged the share count by 4.6 per cent a year. My brief from our chief executive, Hannah Rourke, a veterinarian who co-founded the business in 2009, was to turn a fast-growing company into one that pays for its own growth without letting the turn stall the growth. I came to that brief from twenty-four years in technology finance: audit in Columbus, revenue accounting and planning for a restaurant-systems maker in Atlanta, and the listing of a cybersecurity company in Austin.
The work since has been less about cutting costs than about naming them. We now count stock compensation in shares against a budget the board approves, report free cash flow after it, and judge a multi-year contract by what the customer cannot cancel. The newest cost is the one I think about most. Our AI notes assistant drafts a medical record from the exam-room conversation, and unlike almost everything else we sell, it costs money every time a veterinarian uses it. Pricing that honestly, before the bill priced us, has been the defining decision of my last two years.
Free cash flow from minus 6 to plus 19 per cent
Revenue grew from $295 million in 2021 to $612 million in 2025, while free cash flow moved from an outflow of $18 million to an inflow of $116 million. After stock compensation the 2025 margin is 9 per cent, and that is the figure I put first in every investor presentation.
Annual dilution down from 4.6 to 1.1 per cent
A share budget approved by the Compensation Committee capped gross grants at 3 per cent of shares outstanding in 2023, falling to 2.25 per cent in 2025. Stock compensation fell from 19 to 10 per cent of revenue, at a price of about $14 million a year in extra cash pay.
An AI feature repriced before it ate the margin
Transcription and inference cost $0.31 a note in early 2025, and subscription gross margin had slipped to 77.4 per cent. Metered allowances, a paid add-on and cheaper model routing brought the cost to $0.11 and the margin back to 80.4 per cent by mid-2026.
Convertible notes repaid without new shares
Convertible notes of $287 million, issued before I arrived, matured in March 2026. We repaid them in cash, with no refinancing and no new equity, while still funding a $64 million acquisition and a buyback sized first to offset dilution.
Current focus
I am preparing the board's 2027 capital plan, including whether to renew the share repurchase authorisation that expires in February 2027 and what price discipline should govern it. Alongside it, I am rebuilding our product approval process so that every AI feature on the roadmap carries an estimated cost per use, a pricing plan and a margin floor before engineering work begins.
Conversations I welcome
I intend to remain at Brindlewood. I would consider one independent directorship at a US-listed software or technology-enabled services company with no commercial tie to us, joining its Audit Committee and, after a year, chairing it if the board wished. I can give about twenty-five days a year, subject to approval by our board under its outside-directorship policy. I also accept a few invitations to speak to CFO and audit-committee audiences.