Chief Financial Officer India
Learning to question a complete-looking account
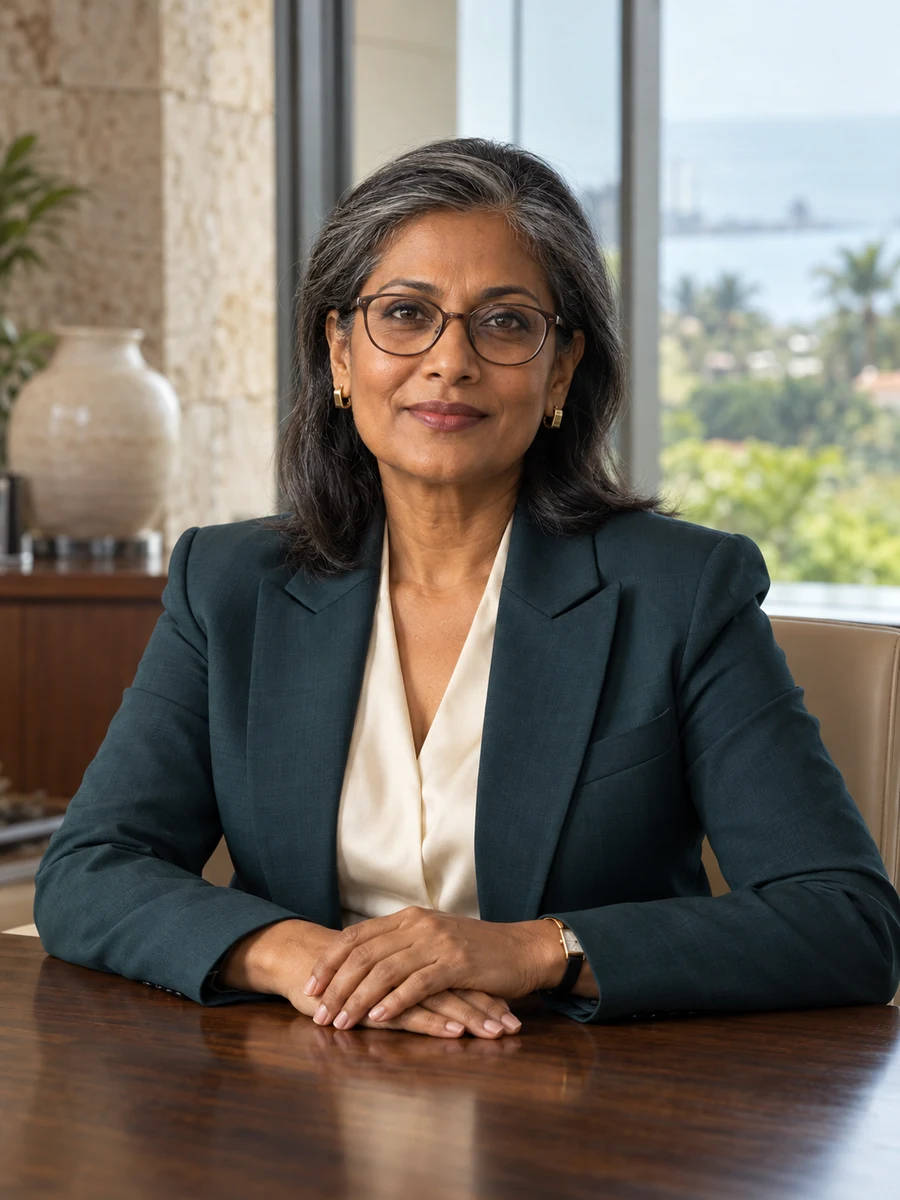
My first role was in the accounts team at Orvuli Engineering Services in Kochi in June 1996. I had completed a commerce degree and was learning how an operating business recorded its work. Supplier invoices and project expenses seemed straightforward until the same item could plausibly be assigned to several jobs. I learnt to ask the project team what had actually happened rather than choose the account that made the month easiest to close. Senior accountants reviewed my work. I was not making independent accounting-policy decisions, but I was developing the habit of connecting a number with the activity behind it.
I joined Qerulvi Spatial Software as a project-finance analyst in April 2002. The company supplied software and implementation services to engineering customers. I prepared project cost reports, reconciled delivery records and worked with commercial colleagues on estimates. Software effort was harder to see than physical material. A team could spend time on an experiment, a customer change and a product correction during the same week. I began asking for records that reflected those differences. The purpose was not to make engineers spend their day classifying time for finance. It was to ensure that a financial conclusion did not depend on a category nobody in delivery could explain.
In April 2008 I became finance manager. Nine colleagues worked with me on reporting and controls. The role required me to turn individual questions into routines that other people could apply consistently. I worked with product leaders on the evidence accompanying significant development expenditure and with commercial teams on the distinction between contracted work and prospects. I also learnt to make corrections without treating the colleague who raised a problem as the cause of the problem. A complete-looking month-end report could be less useful than a report that clearly identified a judgement still requiring review.
The financial-controller appointment followed in April 2014. I led eighteen colleagues and reported to the CFO. I became more involved in financial planning, board papers and the way management measures were reconciled to statutory accounts. Subscription products were becoming more important to the company, and familiar project measures did not answer every question about that business. New sales, customer losses, expansion and billing timing could move in different directions. I wanted the leadership team to understand those movements separately. This period taught me that a metric can be calculated consistently and still be poorly named, especially when the name encourages a reader to infer more than the measure establishes.
I became CFO in April 2021. I now lead twenty-seven colleagues through four managers and report to chief executive Joel Velmari. Product director Pallavi Daqneli is a frequent partner in investment discussions. The company has 370 employees and recorded ₹126 crore of revenue and ₹18 crore of operating profit in FY2025–26. These figures describe the business whose finances I lead; they are separate from the ₹4.8 crore annual finance-function expenditure I manage. I attend board meetings for financial matters but have no director or committee-member appointment.
Three decisions in this profile show how my earlier experience informs the role. We reviewed a development programme whose broad label concealed work with different accounting characteristics. We corrected a retention presentation that counted new customers as evidence of existing relationships continuing. We also revised an acquisition paper that combined certain and conditional payments while omitting the cost of integration from the operating plan. Each issue could have survived a check that the arithmetic added up. Resolving it required the responsible product, commercial, legal and financial specialists to agree what the components represented before deciding what conclusion could be drawn.
I have become more careful about my own influence on a persuasive account. Finance can make a number look authoritative simply by putting it into the board format. When I discover that the description is misleading, I need to correct it visibly rather than improve the next report and hope nobody notices the difference. I also want my managers to understand why the correction matters, so they can recognise the same kind of problem in another setting. My ambition is a finance function that helps the business make explicit choices, including choices to spend, invest and grow. Precision should support those choices, not become a reason to postpone every decision until uncertainty has somehow disappeared.
Open to Board appointments · Executive opportunities
Languages / English · Malayalam · Hindi
A leadership conviction
Growth becomes harder to judge when its components are hidden inside an attractive total. I want finance to separate the customer relationship that continued, the expenditure that qualified for a particular treatment and the payment that depends on a future condition. The explanation should survive a reader asking how the number was made.
- Finance colleagues
- 27
- Four managers; ₹4.8 crore annual function expenditure
- Company revenue
- ₹126 crore
- FY2025–26; ₹18 crore operating profit
- Finance experience
- 30 years
- Engineering-services accounts to software CFO
Education & credentials
- Bachelor of Commerce in Accounting
- Nirquli College of Commerce · 1996
Perspectives from colleagues
Seema kept the new-business result visible while correcting the retention headline. We could discuss both growth and the weakness in existing relationships without confusing them.
She asked us to explain the work inside the programme before finance decided its treatment. The revised record made the product discussion clearer as well as the accounting review.