Chief Financial Officer India
Learning what happens before the balance changes
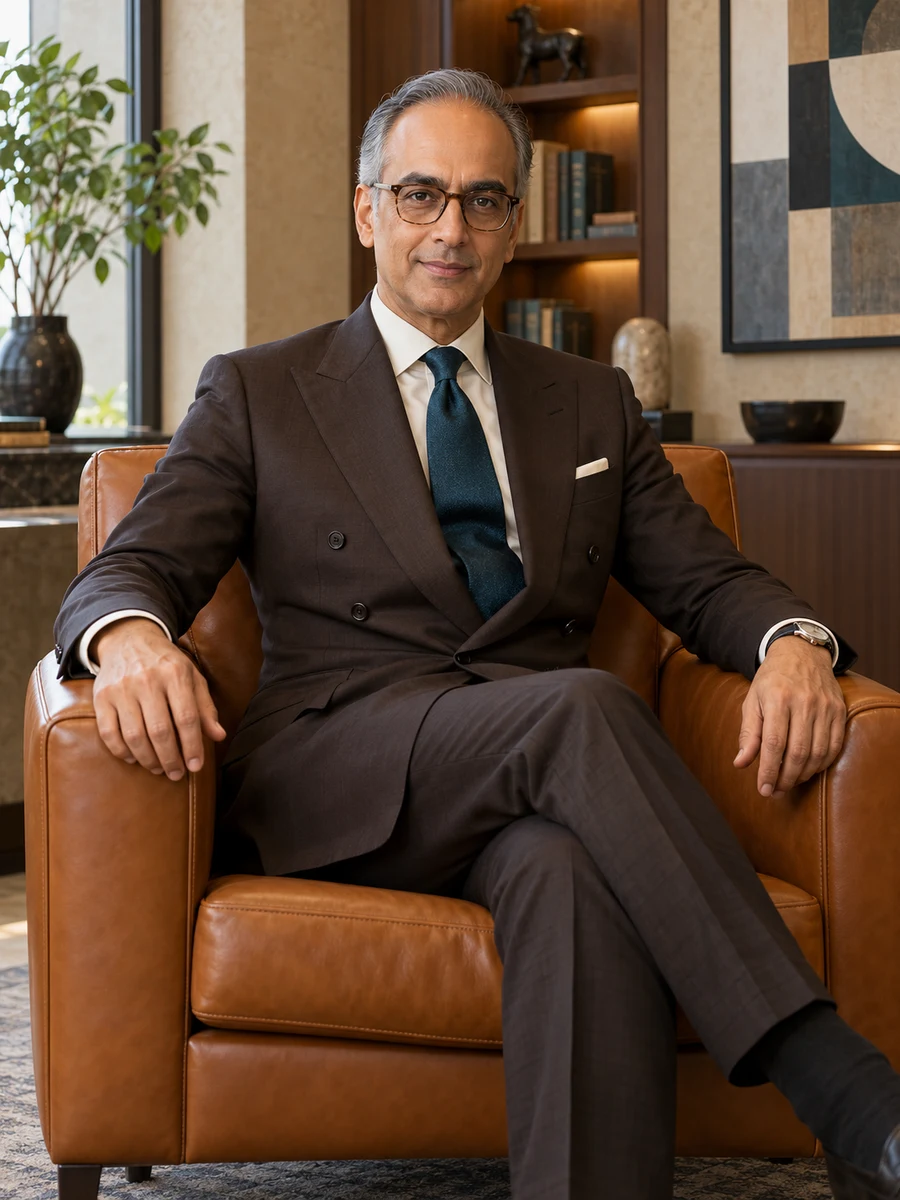
I grew up in Vadodara and studied commerce at Zelqumi Commerce College, completing my bachelor's degree in 1994 and master's degree in May 1996. I joined Zanquri Equipment Services the next month as an accounts assistant. The company maintained and rented professional equipment. My work involved supplier records, rental bills and reconciliations under a senior accountant. An invoice could be correct as a document yet describe the wrong rental period if the equipment had moved and the service record had not reached accounts. That was my introduction to the importance of the event behind the amount.
I did not begin with authority over policy or capital. I prepared records, asked questions and put discrepancies before the people authorised to resolve them. The useful conversations were often with colleagues who collected or repaired equipment. They could tell me that an item had returned, that a replacement had been delivered or that a customer was waiting for a final account. I learned to distinguish evidence of a physical event from a finance assumption about it. A reconciliation was more valuable when someone could explain the remaining difference and own the next step.
In April 2002 I moved into rental-fleet analysis at Zanquri. I prepared forecasts for different equipment groups and worked with service and commercial teams on utilisation assumptions. The role required me to understand the interval between paying for an asset and earning rental receipts. A high utilisation assumption looked attractive until planned maintenance, travel or a period awaiting preparation was included. I did not decide whether equipment was technically suitable for service. My contribution was to show how the operating assumptions affected the financial case and to keep those assumptions available for later comparison.
I joined Raqvuli Care Equipment as finance manager in April 2008. The home-care setting made the customer account more immediate. A family returning a bed could reasonably expect the rental record and refundable deposit to be dealt with correctly. Finance needed reliable information from collection and service colleagues without demanding that they become accountants. I led eight people and introduced clearer responsibility for unresolved accounts. Clinical decisions remained outside our business; technical preparation remained with the qualified operating owners. My team supported those boundaries through records and funding, not by asserting authority it did not have.
The controller appointment came in April 2014. I led sixteen colleagues by departure and became responsible for fleet planning, financial reporting and the preparation of material for directors. I learned that a management report can mislead through compression even when its component amounts are available elsewhere. A deposit balance, a future disposal assumption and a collection schedule each needed its own explanation. I worked with service leaders to make those explanations practical. The aim was not a longer pack for its own sake, but a clearer understanding of which choice the company was being asked to make.
I became CFO in April 2021. Today I lead twenty-two colleagues through three managers with ₹4.6 crore annual function expense. Raqvuli recorded ₹91 crore FY 2025–26 revenue and employed 240 people in March 2026. The founding family owns 62%, a domestic investment partnership 26% and an employee trust 12%; I am a trust beneficiary. Salim Nalqavi is CEO and Mona Ternuvi leads service operations. I present financial matters to directors but have no statutory appointment. Delegated authority and board approvals govern company commitments; revenue is not a budget I personally control.
The decisions described here include corrections to reports I had approved. I had allowed a headline cash balance to sit above the refund obligations it contained. I had accepted a net investment figure that combined a current supplier payment with a possible disposal five years later. I had also used an arrears total before asking whether every included account deserved the same collection action. Repairing those descriptions required time, expense and some uncomfortable conversations. None of the corrections made uncertainty disappear, and I do not describe deferred expenditure as a saving.
I speak English, Gujarati and Hindi. My next finance role should continue to join capital decisions with the customer obligations that make the business possible. I would consider an initial outside board contribution only after preparation, employer consent and an assessment of the specific seat. I have not completed the relevant databank preparation and do not claim director experience. The question I would bring from my executive work is simple: which obligation or future assumption would change the decision if the board could see it clearly?
Open to Board appointments · Executive opportunities
Languages / English · Gujarati · Hindi
A leadership conviction
I ask what obligation arrived with the cash and what work remains before a rental asset can earn again. Finance should make those conditions visible while there is still a choice about spending, purchasing or collecting. A clean total is useful only when the people relying on it understand what it includes.
- Finance colleagues
- 22
- Three managers; ₹4.6 crore annual function expense
- Company revenue
- ₹91 crore
- FY 2025–26;240 employees in March 2026
- Finance experience
- 30 years
- Equipment-service accounts to home-care rental CFO
Education & credentials
- Bachelor of Commerce
- Zelqumi Commerce College · 1994
- Master of Commerce
- Zelqumi Commerce College · 1996
Perspectives from colleagues
Cyrus changed his own funding summary before asking us to approve the purchase. The revised paper showed the deposit obligation and the cost of deferring expansion together.
He listened when our collection records contradicted the arrears list. Finance and service then repaired the handover without treating every customer query as either a credit or a collection failure.