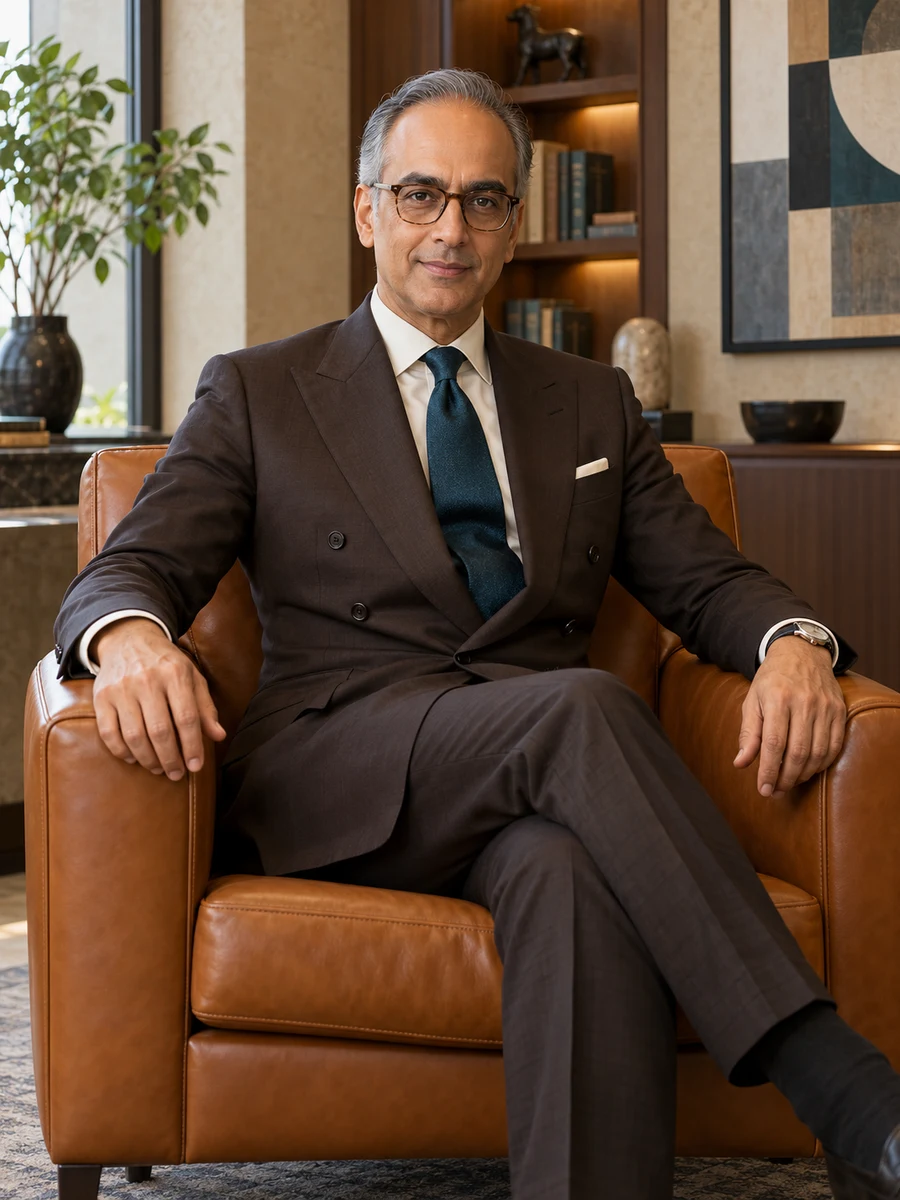
I ask what obligation arrived with the cash and what work remains before a rental asset can earn again. Finance should make those conditions visible while there is still a choice about spending, purchasing or collecting. A clean total is useful only when the people relying on it understand what it includes.
Selected works
Decisions in context.
I
Taking refundable deposits out of the discretionary spending discussion
In 2022 our management cash summary showed ₹4.8 crore in available bank balances while a ₹2.8 crore discretionary fleet purchase was being considered.
The useful cash figure is the one that survives the obligations attached to it.
I am CFO of Raqvuli Care Equipment in Vadodara. We rent home-care beds and mobility equipment, with service teams responsible for installation, collection and equipment preparation. We do not provide clinical care. I lead twenty-two finance colleagues through three managers and manage ₹4.6 crore annual function expense. The company employed 240 people in March 2026 and recorded ₹91 crore revenue in FY 2025–26. My reporting line is to CEO Salim Nalqavi. The role asks me to connect a household's rental account with the company's fleet investment and funding decisions without confusing finance authority with technical or clinical judgement.
My first job was in equipment-service accounts in 1996. I learned to follow an item through an installation, a rental period and its return, because the invoice alone rarely explained the entire relationship. Fleet planning later taught me that a possible sale at the end of an asset's life could improve an investment case without paying the supplier today. As controller and then CFO, I became responsible for the way those distinctions reached directors. I had to correct my own simplified reports as well as question proposals prepared elsewhere.
The cases here concern customer deposits, replacement funding and collection demands. A cash balance of ₹4.8 crore included ₹1.6 crore of refundable deposits we had chosen to reserve; after another ₹1.1 crore of scheduled commitments, the immediate discretionary amount was ₹2.1 crore. A replacement proposal needed ₹10 crore at purchase even if a later disposal might yield ₹2 crore. An arrears total included bills after verified collection and accounts on agreed instalments. Each correction changed a decision about money, with operating and customer consequences that a single headline had concealed.
Reserve the refund obligation before considering expansion
We distinguished ₹1.6 crore of customer deposits within ₹4.8 crore cash and deferred a proposed ₹2.8 crore discretionary purchase. The reserve was our internal policy, not a claim that every deposit was legally held in trust.
A future disposal cannot pay today's supplier
A ₹10 crore replacement purchase had been presented as an ₹8 crore net commitment after a forecast ₹2 crore resale in year five. We restored the initial funding requirement and treated the later receipt as uncertain.
A collection list can contain amounts that need correction
Of ₹2.4 crore labelled overdue, ₹60 lakh related to billing after verified collection and ₹50 lakh was covered by agreed instalments. We investigated and separated those accounts before making further demands.
Current focus
I am improving how finance and service colleagues explain the money tied to each phase of a rental relationship, including refunds, equipment return and the funding of replacement stock.
Conversations I welcome
I am interested in equipment-service finance mandates and a carefully prepared first outside board contribution on capital and customer obligations.
The leadership record
Trusted with consequential decisions.
Formation
Bachelor of CommerceZelqumi Commerce College · 1994
Master of CommerceZelqumi Commerce College · 1996
Cyrus changed his own funding summary before asking us to approve the purchase. The revised paper showed the deposit obligation and the cost of deferring expansion together.
Salim NalqaviChief Executive Officer, Raqvuli Care EquipmentThe full record ↗
Contact
I am interested in equipment-service finance mandates and a carefully prepared first outside board contribution on capital and customer obligations.