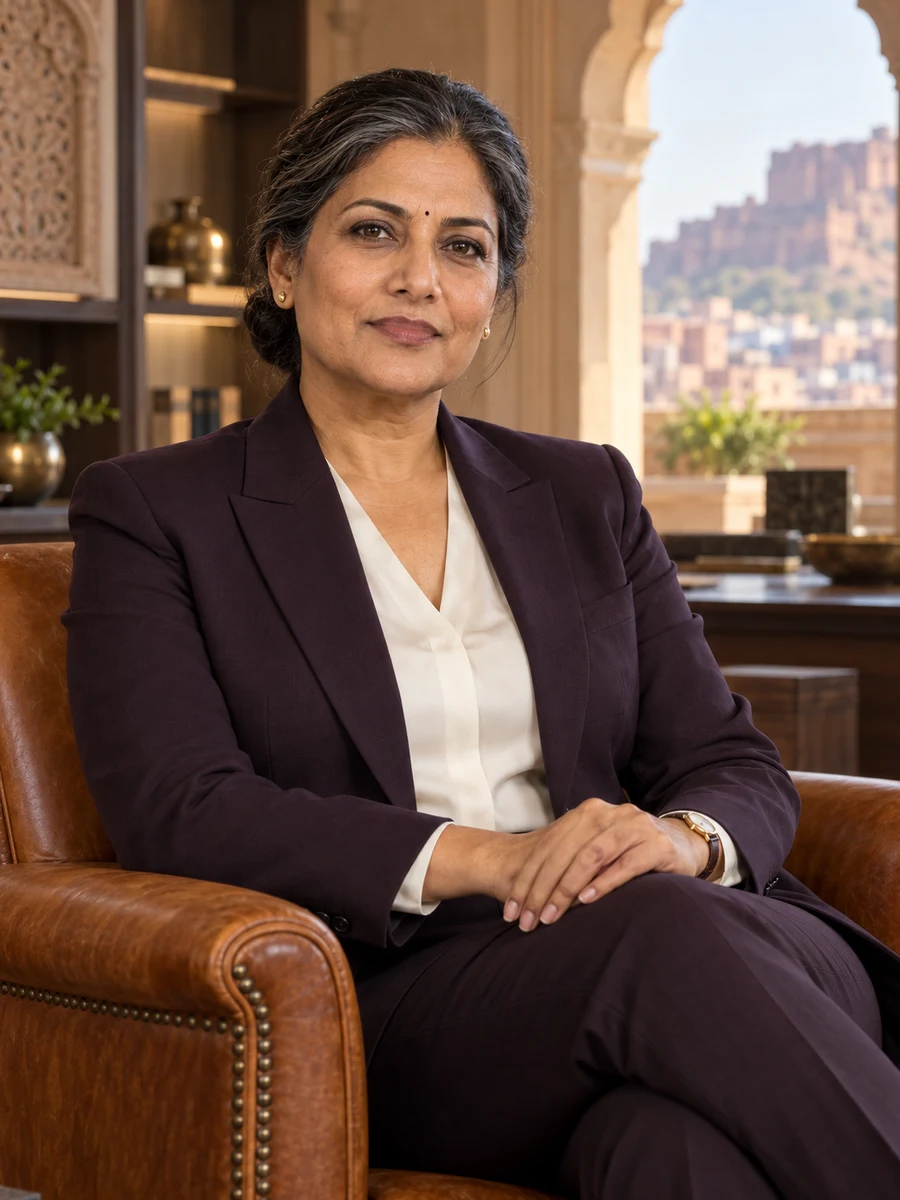
I lead finance for an industrial packaging manufacturer, making the economic meaning of margins, production assumptions and customer exposure clear before a decision depends on them.
Open toBoard appointments · Executive opportunities
A percentage can be arithmetically tidy and economically misleading. I want the reader of a finance paper to know what was weighted, what was assumed and which exposures remain connected. My responsibility includes correcting a figure my own team supplied, even when its replacement makes the proposal less attractive.
Anuja Pervqeshi
Company employees
190
March 2026; twelve finance colleagues through two heads
Company revenue
₹92 crore
FY 2025–26; ₹7.1 crore operating profit
Finance experience
30 years
Accounts preparation, plant finance, control and CFO responsibility
Leadership, seen by others.
Anuja withdrew a contribution summary her own function had approved. She showed us the rupee calculation and what it changed before the pricing proposal went further.
She challenged the claimed cash saving without dismissing our capacity objective. We could then discuss the production plan using the actual expense and demand assumptions.
Kavita PelnashiHead of Operations, Tevlaqni Transit Packaging
Selected leadership work
Replacing an equal average with the contribution the portfolio actually earned
A 2022 pricing and mix review used a selected ₹1 crore sales portfolio containing two product lines.
Finance earns trust by explaining what the number actually represents.
The contribution rate in a product-mix proposal was shown as thirty-five per cent. Two lines carried rates of twenty and fifty per cent, and our summary had averaged them equally. But their sales were ₹90 lakh and ₹10 lakh. Their contributions were therefore ₹18 lakh and ₹5 lakh: ₹23 lakh on ₹1 crore sales, or twenty-three per cent. The difference was not a rounding preference. It changed the economic account directors were being asked to use. I withdrew the summary before the pricing decision and accepted responsibility for the finance review that had let it through.
I am CFO of Tevlaqni Transit Packaging in Jodhpur. We manufacture wooden industrial pallets, transit crates and reusable packing structures. In FY 2025–26 the company recorded ₹92 crore revenue and ₹7.1 crore operating profit, with 190 employees in March 2026. I lead twelve finance colleagues through two functional heads, with ₹2.8 crore annual finance expense. The chief executive owns the enterprise decision; I provide financial challenge, controls and an account of the consequences. Engineering and quality retain authority over product suitability and release.
My cases examine three different ways an appealing summary can hide its basis. A contribution rate needs the sales weights behind it. A fall in fixed expense per unit may come from dividing the same expense by a larger forecast volume, without releasing any cash. Separate legal customer accounts may share a parent, leaving more economic dependence than the largest individual account suggests. None of those distinctions should be left for a director to discover after approving the recommendation.
A weighted portfolio contributed twenty-three per cent
The selected ₹1 crore sales portfolio produced ₹23 lakh contribution after agreed variable costs. The equal-rate average had implied ₹35 lakh; the paper was corrected before pricing approval.
A smaller unit allocation did not release cash
Spreading ₹60 lakh fixed expense over forecast production changed the unit amount without reducing the annual expense. The ₹24 lakh claimed cash saving was withdrawn and expansion approval deferred.
Related buyers represented forty per cent of revenue
Three separate customers sharing a parent generated ₹36.8 crore of ₹92 crore annual revenue. Their ₹8 crore dated receivable total remained separated by legal debtor, with a further group exposure view.
Current focus
The work asks for cooperation as well as correction. Commercial colleagues need usable pricing analysis. Operations needs to understand how the production plan affects the financial view. Customer teams need a group exposure account that does not erase the contracts with individual buyers. I explain what the revised analysis supports and what it does not establish. I also distinguish contribution from operating profit and management planning from statutory reporting. A clearer calculation is useful only when the decision and its limits become clearer with it.
Conversations I welcome
I have thirty years of experience, beginning in accounts work and moving through plant finance and financial control. I hold no company equity and have never held a statutory board seat. My proposed outside-board contribution would concern financial interpretation and management assumptions, subject to further preparation, eligibility review and employer agreement. This fictional profile shows how a manufacturing finance leader can present specific judgement, including errors corrected within their own function, without presenting an executive title as independent board experience.
The leadership record
Trusted with consequential decisions.
Formation
Bachelor of CommerceMerqathi Commerce College · 1996
I have thirty years of experience, beginning in accounts work and moving through plant finance and financial control. I hold no company equity and have never held a statutory board seat. My proposed outside-board contribution would concern financial interpretation and management assumptions, subject to further preparation, eligibility review and employer agreement. This fictional profile shows how a manufacturing finance leader can present specific judgement, including errors corrected within their own function, without presenting an executive title as independent board experience.