Weiran Shou

A leadership monograph

Weiran Shou

A bank's accounts should explain the decisions inside its balance sheet.

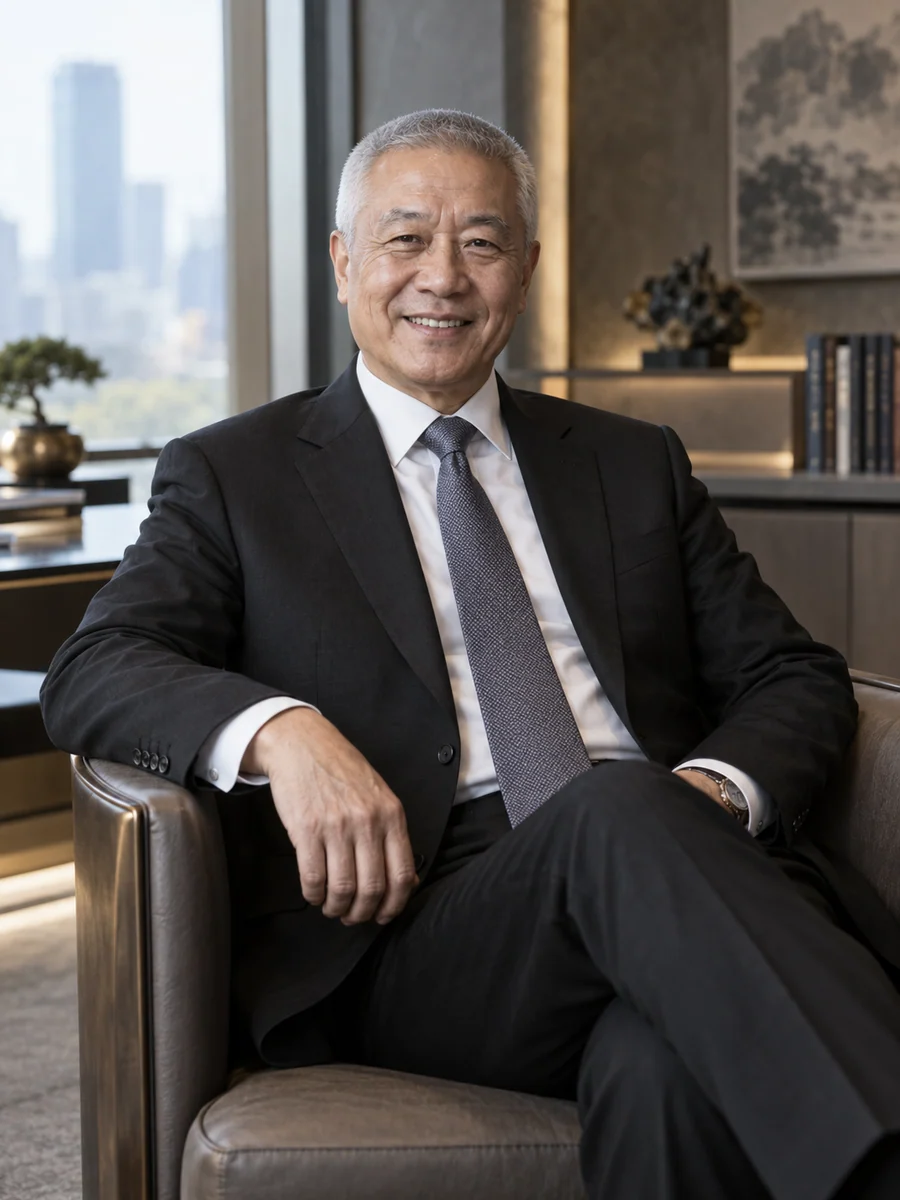
Portrait of Weiran Shou

Chief Financial Officer · China · Volume I · 2026

A bank's accounts should explain the decisions inside its balance sheet.

I lead finance at Lurenshan Commercial Bank, a fictional regional institution in China. Our December 2025 balance sheet held CNY86 billion in assets, including CNY49 billion in loans, funded in part by CNY65 billion in customer deposits. I am responsible for financial reporting, planning and the finance contribution to balance-sheet decisions. Credit approval, risk oversight and treasury dealing have their own accountable leaders. I report to the chief executive and present to the audit committee; I do not hold a directorship.

My career began at a branch accounting desk in August 1988. I learnt that an unexplained difference rarely becomes easier to resolve when several reporting periods have passed. Treasury analysis later showed me the opposite difficulty: a number could reconcile perfectly while the commercial interpretation was wrong. A branch might appear highly profitable because our internal funding charge ignored the duration of its commitments. Those experiences still shape the questions I bring to a financial review.

I have been CFO since January 2015, after seven years as deputy CFO and seven in financial control. My work is to make reported performance intelligible without pretending that every estimate is certain. I ask teams to distinguish a movement caused by customer activity from one caused by a revised assumption or an internal allocation. The distinction matters when executives decide what to expand, when directors challenge an earnings explanation and when a colleague needs to raise a concern before a reporting deadline.

Seven working days, with exceptions still visible

We shortened the monthly management close from twelve to seven working days. Aged reconciliation items fell from 4,800 to 430 over twelve months. The programme cost CNY6.8 million, and the remaining items continued to appear in an owned exception register.

An allocation change without invented profit

A revised internal funding method reassigned CNY88 million of annual management contribution between branches and central treasury. Eight of thirty-six branches changed performance quartile. The method created no additional bank-wide income by itself.

An estimate explained before an earnings discussion

A documented credit-loss estimate revision increased the allowance by CNY156 million and reduced pre-tax profit by the same amount in the affected reporting period. It was neither a cash payment nor a claim that CNY156 million had been written off.

Current focus

I am connecting our monthly forecast to the timing of deposit renewals and loan repricing. An annual average can conceal a difficult quarter. The current work gives the executive team a dated view of those movements, with unresolved assumptions identified before the plan becomes a performance commitment.

Conversations I welcome

I welcome a carefully scoped board conversation outside direct banking competition, particularly where an established enterprise needs stronger financial explanation. I can consider eighteen days a year, subject to employer agreement and the proposed calendar. I also speak with finance teams about reporting judgement. Customer financing requests belong with the bank's relationship teams.

Chapter I

Preface

The most useful question at my first accounting desk was often the least impressive one: which entry explains the difference? I joined Danqiao Merchant Bank in August 1988 after completing an accounting degree at Lanshuren Institute that June. My work was supervised and local. I checked branch records, traced unmatched entries and prepared reconciliations for review. I had no authority to approve credit or move funds independently. What I could do was refuse to describe an unresolved balance as resolved merely because the reporting clock was moving.

That early work taught me the difference between persistence and suspicion. Most discrepancies had ordinary causes: a reference entered differently, a posting recorded in another period or a document that had not reached the reviewer. The task was to establish the cause without humiliating the person who helped find it. I learnt to write down what remained unknown and to return with a specific question. A colleague who expected a fair hearing was more likely to disclose the next awkward item before it grew.

In July 1995, I moved into treasury analysis at the same bank. I prepared maturity schedules and compared funding plans with actual customer balances. The role widened my perspective from whether an account agreed to what the account meant. Two deposits of the same amount could behave differently, and a period-end balance could tell a misleading story about the funding available during the month. I supported decisions taken by treasury leadership; I did not execute trades or set the bank's risk appetite.

I joined Lurenshan Commercial Bank as financial controller in January 2001. By the end of that appointment, it had eighteen branches and 760 employees, still smaller than the institution I serve today. Finance relied on numerous local workbooks and late adjustments. My mandate was to create a consistent management close without removing the local explanations directors and executives needed. We introduced named reconciliation owners and separated recurring accounting work from decisions requiring judgement. I also learnt that a common chart of accounts does not automatically produce a common understanding of profitability.

Promotion to deputy CFO in January 2008 brought planning, branch economics and greater committee exposure. I worked with colleagues who believed finance was making commercially successful branches look less attractive through central allocations. Sometimes their criticism was justified. A cost could be allocated precisely and still provide a poor signal about a decision. I began requiring every proposed allocation change to state its purpose, its effect on behaviour and the result before and after the change. That discipline later became central to our internal funding review.

I became CFO in January 2015. Today I lead 118 finance colleagues through six direct reports across reporting, planning, tax coordination, financial control and related finance operations. The bank employs 1,900 people across thirty-six branches and central functions. My reporting line is to the chief executive, with access to the audit committee for matters within my remit. I attend to explain and answer questions. I do not vote as a director, and I would not describe committee attendance as an independent board appointment.

One defining decision concerned a revised estimate of credit losses. The relevant portfolio evidence had changed, and the proposed allowance increase would reduce the period's pre-tax profit by CNY156 million. Commercial colleagues wanted more time to understand the effect on their plans. I supported a clear explanation of the evidence, the accounting judgement and the remaining uncertainty rather than a postponement tied to the earnings calendar. Risk colleagues retained responsibility for their assessments; finance retained responsibility for the accounting presentation. The decision did not extinguish the underlying customer obligations or turn an estimate into a cash payment.

Another lesson came from our faster close. We reduced the monthly management timetable from twelve working days to seven, but I would not accept speed as the only result. The team also reduced aged reconciliation items from 4,800 to 430 over twelve months and preserved a visible register for what remained. The programme cost CNY6.8 million. We delayed a proposed reduction in support capacity because the remaining work still required experienced judgement. I would rather explain that cost than celebrate a date while moving unresolved work out of sight.

I now spend more time developing colleagues who can explain a result than colleagues who can merely reproduce it. In a review, I ask what changed, what did not, who made the relevant decision and which assumption would alter the conclusion. I want dissent recorded before consensus makes it difficult to recover. Outside my executive role, I am interested in one board contribution where financial clarity matters and competitive conflicts can be addressed. My next chapter should use this experience without confusing familiarity with accounts with authority over every specialist question an enterprise faces.
Chapter II

A Philosophy of Leadership

I want a finance colleague to be able to follow a material number back to its evidence and forward to the decision it changes.

Weiran Shou

Chapter III

Areas of Practice

  1. IManagement close and reconciliation
  2. IIInternal funding economics
  3. IIICredit-loss accounting partnership
  4. IVBalance-sheet forecasting

Chapter IV

Selected Work

§ 1

Closing in seven days without closing the exception register

Our monthly management accounts arrived twelve working days after period end. Executives wanted an earlier view, but finance colleagues worried that a shorter timetable would compress review rather than improve the work. There were 4,800 reconciliation items older than the internal review window, spread across systems and branch records. A simple deadline instruction would have left that underlying condition intact.

I approved a CNY6.8 million programme combining reconciliation workflow, source-data ownership and temporary specialist support. We classified the aged items by value and cause, rather than treating every line as equally important. Branch teams received specific queries before month end where possible. The controller retained authority to raise a significant unresolved matter instead of quietly carrying it into a general suspense explanation.

The trade-off was visible. We deferred a planned reduction in support capacity, and commercial managers had to release experienced staff for data correction. Some argued that the finance department should absorb the work alone. I accepted finance accountability for the close but rejected the idea that finance could correct source records without their owners. We agreed named responsibilities and reported overdue actions to the executive review.

After twelve months, the management close took seven working days and the aged-item count had fallen to 430. Those remaining items stayed in a register with values, owners and next actions. The result did not establish that every account was error-free, and the implementation cost was not presented as a saving. We also reviewed subsequent adjustments to check whether work had simply shifted beyond the earlier deadline.

I would begin the next programme with a better record of the time spent resolving recurring causes. We measured the stock of exceptions well before we measured the effort behind them. That omission made the resource discussion harder than it needed to be, particularly for branches carrying a disproportionate share of older records.

§ 2

Reallocating CNY88 million without claiming to earn it

Our branch performance reports used an internal funding method that gave limited recognition to differences in the duration and behaviour of funding. Lending teams could appear attractive without seeing the full internal cost of the commitment they created. Deposit teams questioned why balances with different renewal patterns received similar treatment. The disagreement affected incentives as well as accounting presentation.

I sponsored a joint review with treasury and commercial management. Treasury developed the funding assumptions; finance reconciled the resulting management contribution to the bank's total; branch leaders examined the customer behaviours the method might encourage. We ran the revised account alongside the existing one for two quarters before changing the relevant performance measures.

The revised method reassigned CNY88 million of annual management contribution between branches and central treasury. Eight of thirty-six branches changed performance quartile. That was not CNY88 million of new income. The bank-wide account did not improve simply because the internal allocation changed, and we made that explicit in the executive paper.

Several branch heads opposed the timing because they had made commitments under the old approach. I agreed to a transition period for the affected incentive calculations, while keeping both sets of figures visible. The cost was slower adoption and a more complicated reporting pack for two quarters. The benefit was that colleagues could distinguish a commercial change from a measurement change before their performance was judged through it.

In a subsequent six-branch pilot, the reviewed category of more stable customer balances rose from CNY5.4 billion to CNY6.1 billion over nine months. Pricing, customer activity and the economic environment also changed. I did not attribute the movement solely to the new method. The lasting result was a better conversation about funding commitments. In retrospect, I would have involved branch teams earlier in testing the explanations, because a technically correct model still needs language that a customer-facing manager can use.

§ 3

Taking the earnings consequence of a revised loss estimate

A portfolio review produced evidence that changed our assessment of expected credit losses. Risk and lending colleagues had examined the customer positions, while finance evaluated the accounting effect and its presentation. The proposed revision increased the allowance by CNY156 million. Recognising that movement would reduce pre-tax profit by the same amount in the affected period, before any tax effect.

Commercial management asked whether the decision could wait for another round of customer discussions. Their concern was understandable: some of the underlying outcomes remained uncertain, and the reported movement would materially affect the period's result. I asked the team to distinguish uncertainty about future recovery from uncertainty about the evidence already available. The earnings calendar was not an additional source of evidence.

We prepared a movement analysis separating portfolio changes, revised assumptions and other adjustments. The paper retained the principal disagreements, the basis for the estimate and the conditions that would prompt another review. I presented the finance judgement to the audit committee with the relevant risk contribution available for challenge. Committee consideration did not transfer management's preparation responsibilities to the directors.

The allowance increased by CNY156 million as proposed. I described the movement as an accounting estimate with an immediate earnings consequence. It was not a CNY156 million cash payment, nor did it mean that the same amount had been written off or that customer obligations had disappeared. Those distinctions were repeated in the internal explanation because an imprecise summary would have obscured the decision we had actually made.

The difficult consequence was a lower reported result and additional work for colleagues explaining it. The improvement was a clearer record of how new evidence reached the accounts. I would commission the explanation earlier next time, alongside the analysis, because writing it exposed questions that a completed spreadsheet had not resolved. I would also preserve more of the rejected assumptions so a later reviewer could understand why the final judgement differed from an earlier view.

§ 4

Paying for a liquidity option before it was needed

A balance-sheet planning discussion proposed reducing a readily available liquidity buffer to improve income. The assets released could have supported a higher-yielding use, but treasury's scenario work showed a narrower margin for ordinary funding variation. The decision was not mine alone. Treasury owned the liquidity analysis, risk challenged the scenarios and the authorised executive forum considered the proposal.

My finance team made the income trade-off explicit. Retaining an additional CNY1.2 billion in the proposed buffer carried an estimated CNY18 million annual income opportunity cost under the assumed yield difference. That figure was a planning comparison, not a fee paid to an external party. It also depended on the alternatives remaining available at the assumed rates.

I supported retaining the buffer, with a scheduled review of its size and the assumptions behind it. Commercial colleagues argued that the bank was giving up income while their own plans remained demanding. I asked that the resulting budget reflect the decision rather than require the same income to be recovered through an unexplained stretch elsewhere. The executive forum accepted both the buffer recommendation and the corresponding planning consequence.

During the reviewed year, the bank did not face the most severe scenario used in the discussion. I resisted presenting that fact as evidence that the decision had been unnecessary or as proof that the buffer had prevented a crisis. We had purchased flexibility under uncertainty. Its usefulness could be reviewed through actual funding patterns, availability and cost without inventing an avoided loss.

The enterprise change was a closer connection between a balance-sheet choice and the income plan attached to it. I would improve the next review by showing a wider range of opportunity costs, because a single CNY18 million estimate acquired more authority in discussion than its assumptions deserved. The lesson concerns how finance explains a choice, not a universal prescription for how much liquidity another bank should hold.

§ 5

Removing a timing error from the income plan

Our first planning case for net-interest income used a combination of average balances and year-end assumptions. It was convenient to consolidate, but it did not fully represent when existing loans would reprice or when deposits would renew. Treasury colleagues could see the timing mismatch in their schedules, while commercial teams were discussing an annual figure that concealed it.

I asked finance to rebuild the relevant forecast by monthly cohorts, using the available contractual dates and explicit assumptions where customer behaviour remained uncertain. The work did not require us to pretend that every renewal was known. It required a clear distinction between an observed date, a commercial expectation and a planning convention.

The revised case removed CNY74 million of unsupported net-interest income from the initial plan. The chief executive challenged whether finance had become too cautious, and business leaders wanted to preserve the earlier ambition. I kept the commercial aspiration separate from the forecast mechanics. If a team proposed an action that could replace part of the income, it needed its own assumptions, owner and implementation timetable.

We accepted the lower base case and retained alternatives for different renewal and repricing patterns. The adjustment was not a realised loss, and removing it from a spreadsheet did not save cash. It made the plan more faithful to the balance-sheet sequence we could support at the time. The annual net-interest income variance to the revised plan was CNY29 million, compared with CNY118 million against the preceding year's plan. Market conditions and the business mix differed, so the comparison does not isolate the method's effect.

The useful change was that a forecast disagreement could be traced to a date or assumption before it became an argument about commitment. I would have introduced the monthly view earlier in the planning cycle. Producing it late left too little time for commercial teams to develop credible responses and encouraged people to defend a number before they understood how it had been assembled.

Chapter V

The Boardroom

  • Lurenshan Commercial Bank

    CFO presenting to the audit committee; not a director

    Financial reporting and significant estimate explanations

    2015–present

Chapter VI

Essays

An invitation

Contact

I welcome a carefully scoped board conversation outside direct banking competition, particularly where an established enterprise needs stronger financial explanation. I can consider eighteen days a year, subject to employer agreement and the proposed calendar. I also speak with finance teams about reporting judgement. Customer financing requests belong with the bank's relationship teams.

Open to
  • Board appointments
  • Speaking invitations

office@weiranshou.example