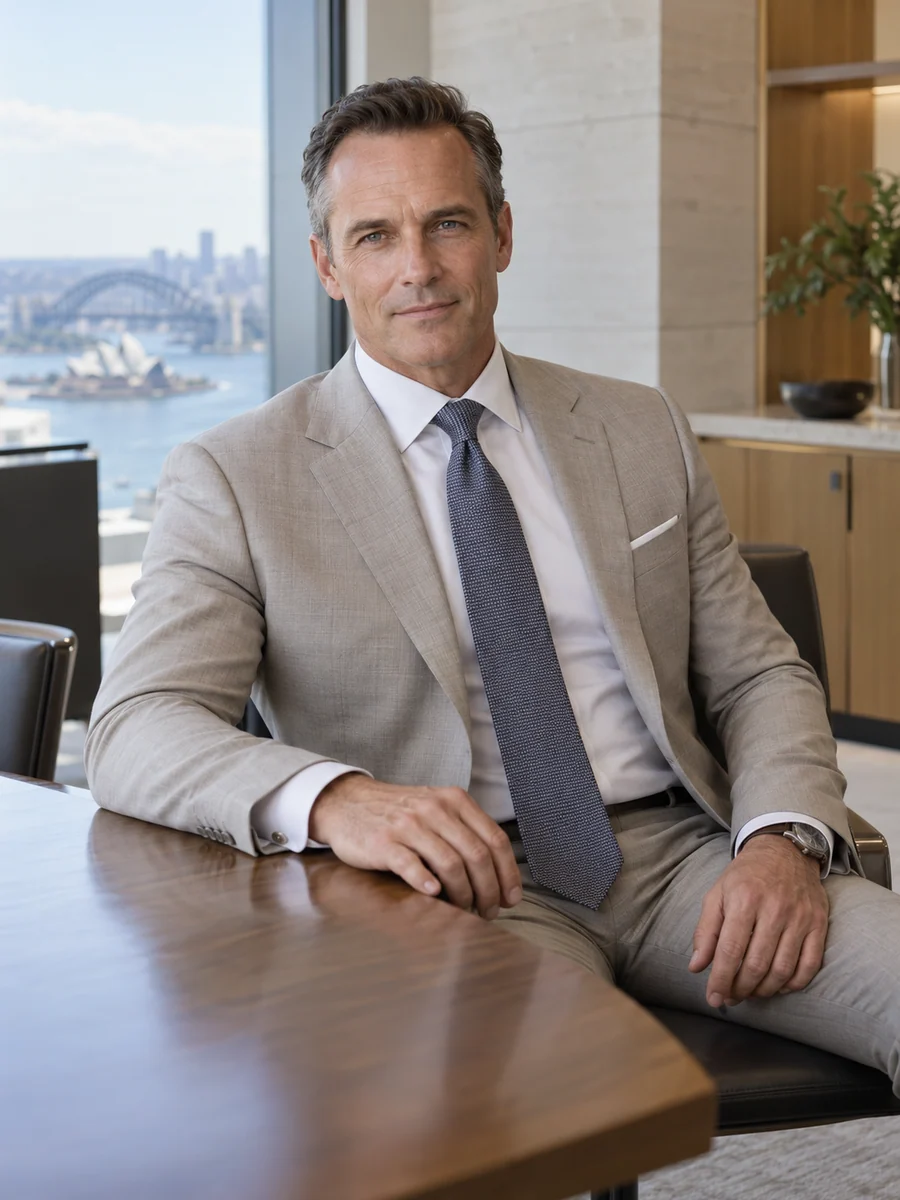
Dominic ArvenholtChief Product Officer
Portrait of Dominic Arvenholt

Chief Product Officer · Australia

DominicArvenholt

A business banking product should explain its exceptions before it enlarges its promise.

I began in business-product analysis at Erlavane Bank in March 1994, after completing economics at the fictional Kelvethan College in December 1993.

Open to
  • Board appointments
  • Speaking invitations

A business banking product should explain its exceptions before it enlarges its promise.

I build business-banking propositions around the work customers need to complete, including the paths that interrupt a polished demonstration. A business may need two people to approve an action, prefer standard settlement or depend on history a retiring feature has not yet made portable. Those conditions belong in the product decision before the launch narrative becomes difficult to change.

At the fictional Erlavane Bank in Sydney, I lead 168 product colleagues through seven direct reports with A$34 million delegated FY 2026–27 expense. Company assets were A$74 billion in FY 2025–26 and current employment is 4300. Lending, risk, compliance, treasury, operations, engineering, legal interpretation and cybersecurity remain separately led. Product responsibility means working across those mandates, not assuming they become mine because the customer encounters one interface.

My thirty-two-year career leaves the bank for merchant-payment products and returns. It includes a single-approver design I approved too quickly, a settlement option I declined to make the default, an incomplete legacy transition and a prototype that still needed revision after testing improved. Every example is fictional. Together they show how the product team can choose a more bounded promise while remaining accountable for the customer journey it actually offers.

A smaller bundle gave the pilot a clearer proposition to assess

The 2023 proposal began with forty features. Research with ninety businesses informed a core of account, payments and cash-flow export, with credit separately assessed. A sixty-business pilot retained forty-one after ninety days while nineteen declined. A$4.8 million funded product work; the result was a pilot observation, not a market-wide conversion claim.

My opening flow had omitted a second person’s part in the decision

The 2004 pilot included fifty-six businesses whose own mandates required two approvers. Thirty-eight were blocked by the single-approver path I had approved. A$420000 supported pending, decline, retry and assisted journeys. The correction preserved the relevant checks instead of treating fewer screens as proof that the task was complete.

An improved comprehension result still left work to do

In 2025, sixty-seven of 240 owners read forecast receipts as spendable funds. We separated available balance from the forecast and removed the combined headline. Fourteen of 180 owners still misread the revised prototype. A$5.6 million supported product work, with further revision retained rather than a claim of complete resolution or a full launch.

Current focus

I am examining the points where a product’s promise becomes harder to understand outside its easiest path. The next useful change may be a narrower bundle, a clearer optional service or a supported exit rather than another feature. I want the team to make the remaining uncertainty visible enough that operating and control colleagues can help decide what should happen before the product reaches a wider audience.

Conversations I welcome

I would consider a discussion about product scope, business-customer journeys or a prospective first-board contribution in banking or payments. Employer agreement, preparation, relationships and actual workload would need assessment. This fictional profile supplies no banking product or financial advice. An initial message should describe the product question without attaching customer records, application details or restricted commercial terms.

168

Product colleagues

Seven direct reports at October 2026; lending and control mandates separately owned

A$34 m

Delegated FY 2026–27 product expense

Function scope rather than bank assets, credit authority or treasury funding

32

Years developing business propositions

From March 1994 analysis through merchant payments and a return to banking

I want the product team to understand what a business customer must do when the straightforward path no longer fits. A second approver, an optional settlement choice or an unfinished migration is part of the product, not an inconvenience to be hidden behind its launch story. I would rather narrow the promise and support the remaining journey than make a broader claim whose exceptions the customer has to discover alone.

Dominic Arvenholt

Chief Product Officer

Areas of stewardship

Where accountability has been mine.

  1. IProposition scope for different business needs
  2. IIMulti-person approval and exception journeys
  3. IIIOptional merchant services with visible conditions
  4. IVProduct retirement and customer understanding

Selected work

Decisions, and what they changed.

I

The forty-feature bundle became a smaller proposition a business could actually choose

The 2023 business-account proposal contained forty features, intended to make one package look comprehensive.

The full account

II

The approval journey needed a second person whom my prototype had omitted

I approved a business-opening prototype in 2004 that favoured a short, single-approver path.

The full account

III

Faster settlement remained an option instead of becoming every merchant’s paid default

At Serravon Payments in 2011, the team considered an accelerated-settlement service for merchants.

The full account

In the words of others

Trusted by those who appoint.

Dominic let the business research reduce the scope of the bundle. The pilot had a proposition people could assess, and the credit option remained a separate decision rather than an implied part of every account.
Clara NethervaleFictional business-product research colleague; participant in the 2023 scope review
He accepted that a short flow was not a complete opening journey for a business with two approvers. We worked on pending and exception states instead of hiding those customers behind a successful demonstration of the easiest path.
Owen BellarvenFictional product-operations colleague; participant in the 2004 approval-flow correction

The journal

Perspective, set down with care.

An invitation

Contact

I would consider a discussion about product scope, business-customer journeys or a prospective first-board contribution in banking or payments. Employer agreement, preparation, relationships and actual workload would need assessment. This fictional profile supplies no banking product or financial advice. An initial message should describe the product question without attaching customer records, application details or restricted commercial terms.

Open to
  • Board appointments
  • Speaking invitations

office@dominicarvenholt.example