Prepared for boards, nomination committees & search advisers

File No. CMO-026

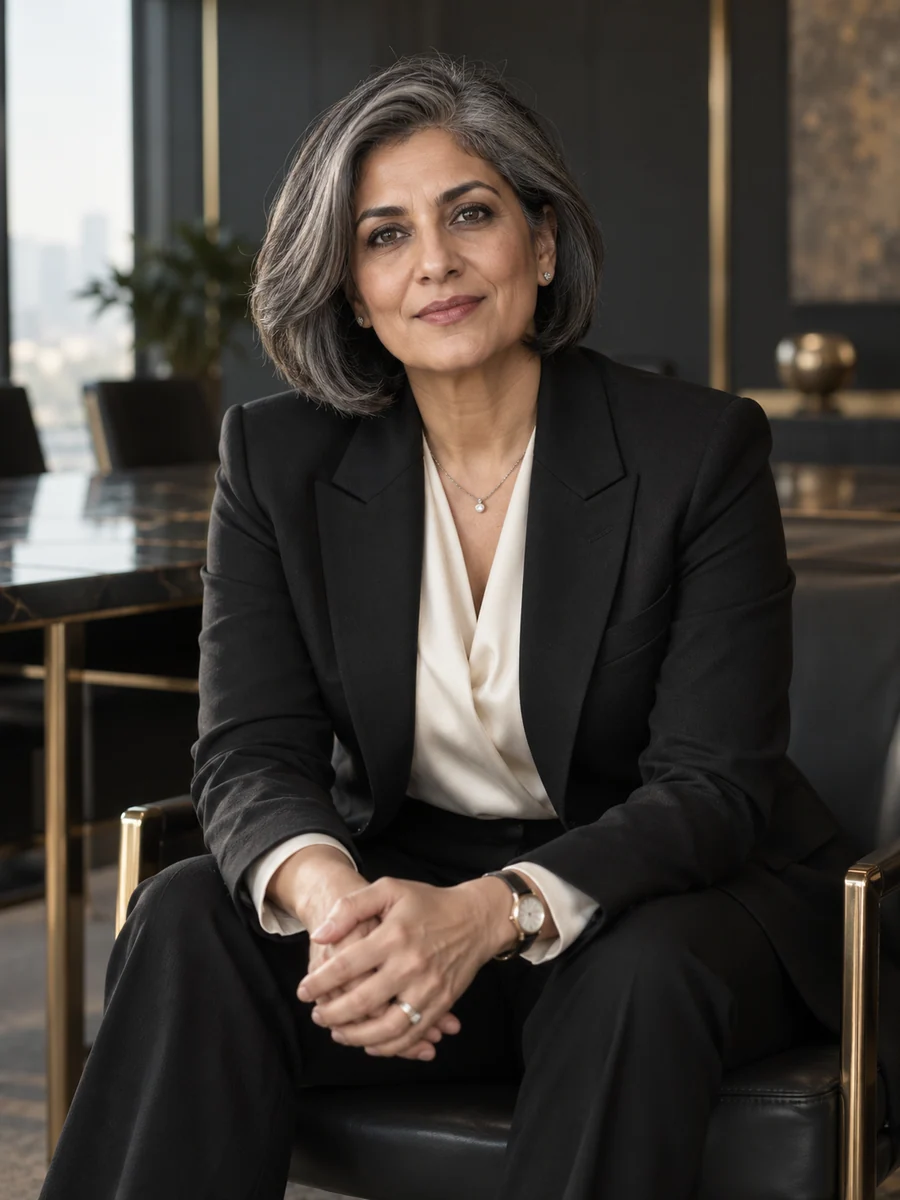
Portrait of Kavya Vardhane
Kavya Vardhane

Kavya Vardhane

The promise of a bank begins with what its customer understands.

SubjectKavya Vardhane
PositionChief Marketing Officer
BaseIndia
LanguagesMarathi, Hindi, English
StatusI would consider a defined advisory or speaking discussion about banking communication, and a compatible first board contribution after employer consent and relationship review.

Summary

I became interested in marketing through the distance between a message and the conversation it created. A phrase could look clear in a presentation and still leave a customer uncertain about what happened next. Banking made that distance particularly important to me. A campaign might be brief, but the relationship it introduced could continue for years, with product conditions and service decisions shaping what the original promise came to mean.

The promise of a bank begins with what its customer understands.

A banking message travels further than the campaign that carries it. Someone remembers a phrase, discusses it at home or asks a branch colleague to explain what it means. The conditions that were visually secondary in an advertisement can become central to that conversation. I lead marketing with that continuation in mind. The work is to create interest through a proposition the bank can explain clearly, while respecting the decisions and responsibilities that belong to product, risk and service teams.

My career began in consumer-finance marketing in April 1994. I joined Naviratha Bank in April 2001 and developed through regional communication, deposits and retail marketing before becoming CMO in April 2020. I now lead seventy-four employees through six direct reports, with forty-eight agency personnel separately. My ₹96 Cr marketing authority for FY2026–27 supports communication and relationship development. It does not give me authority over lending approval, product pricing, treasury or the bank's compliance sign-off.

Naviratha's March 2025 account comprised ₹48,600 Cr of assets, ₹39,200 Cr of deposits and ₹31,800 Cr of advances, with 6,000 employees and 286 branches. Those figures describe the fictional bank's scale. My own record concerns the choices inside its marketing work: which conditions receive attention, how a translated explanation keeps its meaning and when acquisition language stops describing the relationship a customer actually has with us.

Conditions made easier to understand in a selected study

In a 120-person study, sixty participants saw an existing fee explanation and sixty saw a revised version. Twenty-seven in the first group and forty-eight in the second correctly understood the specified condition. I kept that bounded finding attached to the wording decision, without claiming it established every customer's understanding or complete regulatory compliance.

An acquisition account that followed the funded relationship

A ₹2.4 Cr campaign produced 18,000 applications, 6,200 opened accounts and 4,800 accounts funded within thirty days. Only 2,700 met our explicitly defined activity criterion at day ninety. I changed the account to retain those stages and the cost associated with each, rather than use the application total as a complete description of the relationship created.

Language review that examined product meaning

Five of thirty-two selected translated clauses required correction because their meaning had shifted. The revised clauses received independent review before release. I treated that work as part of the proposition, not a finishing task delegated after the main campaign was approved. Customer comprehension remained a separate question from the linguistic review.

Current focus

I am connecting campaign development more closely with the branch conversations it generates. That includes the questions staff receive, the conditions customers struggle to interpret and the time needed for a useful follow-up. I want marketing's account of progress to describe a relationship the operating business recognises, with unresolved questions still visible to the people who can answer them.

Conversations I welcome

I would consider a defined advisory or speaking discussion about banking communication, and a compatible first board contribution after employer consent and relationship review. My proposed availability must fit the actual responsibility. I am interested in work where careful explanation is part of the commercial proposition, rather than an afterthought added to an already fixed message.

Exhibit ATrack record

ItemMeasureFigure
01Marketing employeesSix direct reports; forty-eight agency personnel separately74
02FY2026–27 marketing authorityExcludes credit decisions, product pricing and treasury₹96 Cr
03Marketing experienceConsumer finance and banking, April 1994 onwards32 years

Exhibit BStatement of approach

I want the words that attract a customer to remain useful when that person asks a branch colleague what the offer means for them.

Signed — Kavya Vardhane

Exhibit CSelected matters

Matter 01Ref. CMO-026-M01

Giving a fee condition enough room to be understood

In January 2024, a proposed retail campaign used a short fee explanation that the creative team considered clear and visually economical. Branch colleagues were less confident that a customer would understand the condition affecting the charge. Product and compliance specialists retained responsibility for the underlying terms and approval. My question concerned the communication: whether the campaign gave the relevant condition enough attention for a reader to interpret it.

We funded an eight-week, ₹24 lakh study with 120 participants randomly allocated between two groups of sixty. One group saw the existing explanation and the other a revised version that made the specified condition more prominent. Twenty-seven participants in the first group and forty-eight in the second correctly answered the defined comprehension question. This was a selected study of that explanation, not a finding about every customer or a complete assessment of the product's suitability.

The commercial sponsor preferred the shorter version because it left more room for the campaign's main invitation. I recommended the revised explanation and accepted a less compressed presentation. Product colleagues checked that the meaning remained accurate, and the relevant approval process continued separately. We also prepared branch staff to explain the same condition, rather than improve the advertisement while leaving the conversation that followed unchanged.

The result supported a wording decision. It did not establish a reduction in customer loss, a new revenue outcome or universal compliance. We retained the study design and exact question in the internal account so later presentations would not turn the difference between the groups into a broader claim about financial understanding. The twelve participants in the revised group who did not answer correctly remained part of the finding.

The enterprise changed the sequence of its campaign review. Comprehension became a question to examine while the creative work could still change, instead of a request for reassurance after the final layout. I would bring branch questions into the first brief and test the most consequential condition earlier. That would give the team a clearer design problem before visual simplicity became attached to a preferred version, and make the cost of explanation part of the proposition from the beginning.

Matter 02Ref. CMO-026-M02

Following an acquisition campaign to a defined day-ninety relationship

A campaign that began in June 2024 attracted 18,000 applications with ₹2.4 Cr of marketing expenditure. The initial review led with the application count and its approximate cost of ₹1,333 each. That was a valid calculation of one response measure, but it did not describe how many people had established the account relationship the retail business expected. Nalin Vedrakar wanted the subsequent stages visible before the next campaign commitment.

We followed the fixed campaign cohort through opening, funding and later use. Of the 18,000 applications, 6,200 accounts were opened and 4,800 were funded within thirty days of opening. At day ninety, 2,700 met the stated activity criterion: at least three customer-initiated transactions during the preceding thirty days. The measure was an internal definition for this review, not a regulatory classification or an assessment of the customer's financial wellbeing. Each account's observation period followed its own opening date.

The acquisition sponsor preferred to retain applications as the main success measure because the campaign directly generated that response. I kept it in the report but added the later stages and their costs. The same ₹2.4 Cr represented ₹5,000 per account funded within thirty days and approximately ₹8,889 per account meeting the defined day-ninety activity criterion. We did not call either figure lifetime value, profit or the full cost of serving the relationship.

I recommended postponing an increase in the same acquisition approach while marketing and retail examined the points at which people stopped progressing. That retained the campaign's contribution without assuming that every application represented equivalent future value. The review continued until the last opened account reached its observation date; it was not compressed into the campaign's media period. Credit and eligibility decisions stayed outside marketing's authority.

The practical change was a shared account that finance, marketing and the retail business could recognise. It gave the next proposal a more precise question than simply how to buy another large response total. I would agree the observation windows and activity definition before committing the media budget, so the business knows when a meaningful review will be possible. That would also prevent the reporting calendar from rewarding an early measure merely because the later relationship has not had time to develop.
Matter 03Ref. CMO-026-M03

Reviewing thirty-two translated clauses for the meaning they carried

In February 2025, a branch communication programme prepared selected product explanations in Hindi, Marathi, Tamil and Kannada. The delivery plan treated translation as a final production task after the main campaign had been agreed. Product colleagues questioned whether some compressed phrases would carry the intended conditions accurately. The issue was not whether the wording sounded fluent, but whether it preserved what the customer was being told.

We commissioned a six-week, ₹18 lakh review of thirty-two selected clauses, eight in each language. Product owners and qualified language reviewers compared the intended meaning with the translated explanation. Five clauses contained meaning differences requiring correction. That was a review of selected text, not a count of customers who misunderstood it. We kept the distinction clear when discussing why the work mattered and what evidence it had produced.

The production sponsor wanted the full material released on schedule and suggested correcting the five clauses in the next edition. I supported holding the affected material until the revisions had independent language review. We accepted a later release for that material and additional coordination with branches. The other reviewed clauses were not treated as evidence that every message in those languages was ready; the finding belonged to the selected set.

The five revised clauses were independently checked against their intended meaning before release. The project retained the product owner's approval and the relevant compliance process rather than treating a linguistic review as a substitute for either. We also identified customer comprehension as a separate question for subsequent work. Correct meaning in a translated clause does not establish that every intended reader finds the explanation easy to use.

The decision changed the place of language work in campaign planning. Review time and ownership moved into the first brief, with product specialists available while the wording could still be revised. I would now identify phrases carrying conditions before the creative team compresses them, and allow the local explanation to use the space it needs. The objective is a coherent proposition across languages, not identical line lengths that make production convenient while leaving the receiving branch to repair the meaning in conversation.

Matter 04Ref. CMO-026-M04

Choosing an educational message for what people could do with it

A July 2025 customer-protection programme had a broad-reach warning format ready for a larger media release. The message was recognisable, but the team wanted to know whether a reader could identify an appropriate next step in a suspicious-message scenario. Awareness of a general warning and the ability to interpret a particular situation were different questions. Our study was designed around the latter, without exposing anyone to a real financial threat.

The ten-week, ₹32 lakh assessment involved 320 volunteers randomly allocated between two groups of 160. One group saw the existing general warning and the other a revised scenario-based educational card. Seventy-one participants in the first group and 112 in the second identified the intended response in the defined exercise: checking through a bank contact route they had independently verified. No payment, account access or real suspicious message was involved in the exercise.

The media sponsor preferred the broad-reach creative because it was simpler to distribute and had a stronger recognition account. I supported using ₹80 lakh of already planned communication expenditure for the more instructional approach and its branch explanation. That changed the mix of the programme and accepted fewer expected impressions for that allocation. Security and customer-protection specialists reviewed the content; marketing did not invent operational advice independently.

The study did not establish fraud prevented, a change in actual customer losses or behaviour under pressure. Forty-eight participants in the revised group still did not identify the intended response. We retained that result and the need for further examination rather than use the improvement to claim the education task was complete. The next release recommendation concerned the chosen material and its support, not a promise of protection against every threat.

The enterprise gained a more useful distinction between message recognition and demonstrated interpretation in a selected exercise. I would agree that distinction before approving the first media objective, so the team does not discover late that its main measure answers a different question. I would also involve branch and customer-protection colleagues earlier in deciding which scenario deserves explanation. Education should earn its place through the understanding it helps develop, while remaining honest about what a controlled exercise cannot tell us about real events.

Matter 05Ref. CMO-026-M05

Replacing a broad SME sponsorship with conversations about the actual need

In April 2026, a proposed SME campaign centred on a broad sponsorship programme with a ₹75 lakh allocation. Its presentation assumed that a business audience would mainly want to discuss borrowing. Branch colleagues described a more varied set of questions, including collections and reconciliation. I wanted the marketing proposition to reflect those needs without treating every conversation as an opportunity to advance a credit product.

We held ten small listening sessions involving sixty business owners, with participants asked to identify their primary banking-service question. Eighteen prioritised collections, fourteen reconciliation, sixteen credit and twelve other issues. These were selected conversations, not a representative survey of all SMEs. Thirty-six participants separately requested a service follow-up; eleven of those requests concerned credit and went through the bank's ordinary process. No approval or disbursement outcome was attributed to the sessions.

The sponsorship sponsor preferred the larger audience and the visibility associated with the original programme. I recommended redirecting ₹42 lakh of its proposed allocation to six sector-focused service clinics, retaining the remaining ₹33 lakh uncommitted pending review. The smaller format gave retail colleagues a clearer basis for preparation. It also gave up the immediate reach of the broader event and required more coordination around the questions participants actually wanted to discuss.

The listening work changed the brief for the clinics; it did not establish their eventual commercial result. By October 2026, preparation and the first two clinics were complete, while the remaining four were still scheduled. We kept the service follow-ups distinct from qualified lending demand and left credit decisions with the appropriate teams. The retained allocation was not described as realised saving or used to claim that a smaller event necessarily creates better customers.

The decision made audience relevance a substantive part of the investment discussion. A CMO can create a more useful proposition by listening to the business question before choosing the scale of the event. I would bring that listening stage forward in the next annual plan, before a sponsorship slot creates pressure to fill an already purchased format. I would also agree the service capacity for follow-up in advance, so a more relevant invitation leads to a prepared conversation rather than simply a different kind of unanswered enquiry.

Exhibit DFormation

  • Postgraduate qualification in managementRishena Institute1994
  • Degree in commerceRishena Institute1992

Exhibit EReferences

Kavya brought the branch explanation into the campaign decision while we could still change the wording. She asked us to address the condition customers misunderstood instead of assuming that another line of small print completed the task.
Nalin VedrakarRetail banking head, Naviratha Bank · fictional colleague
Her acquisition review separated applications from the accounts that remained active under the stated definition. That gave us a more useful discussion about the next allocation, including the work the business still needed to do after opening an account.
Devika VarshenChief executive, Naviratha Bank · fictional colleague

Exhibit FPublished views

CorrespondenceNext steps

An invitation

Contact

I would consider a defined advisory or speaking discussion about banking communication, and a compatible first board contribution after employer consent and relationship review. My proposed availability must fit the actual responsibility. I am interested in work where careful explanation is part of the commercial proposition, rather than an afterthought added to an already fixed message.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

office@kavyavardhane.example