European insurers are choosing between quietly withdrawing flood cover and spreading its cost invisibly across every customer. I argue for a third course: prices that reflect the hazard, prevention the insurer helps to pay for, and public support only for the layer no private balance sheet should hold.
Insurance is a promise about the future sold at a price agreed today. When we cannot state that price openly to a customer, an investor or a supervisor, it usually means we have stopped understanding the risk. I would rather lose a contract by explaining a price than keep it by hiding one.
Actuarial, treaty underwriting and general management
I lead an insurer on the principle that a risk we cannot price in the open is a risk we should not pretend to carry.
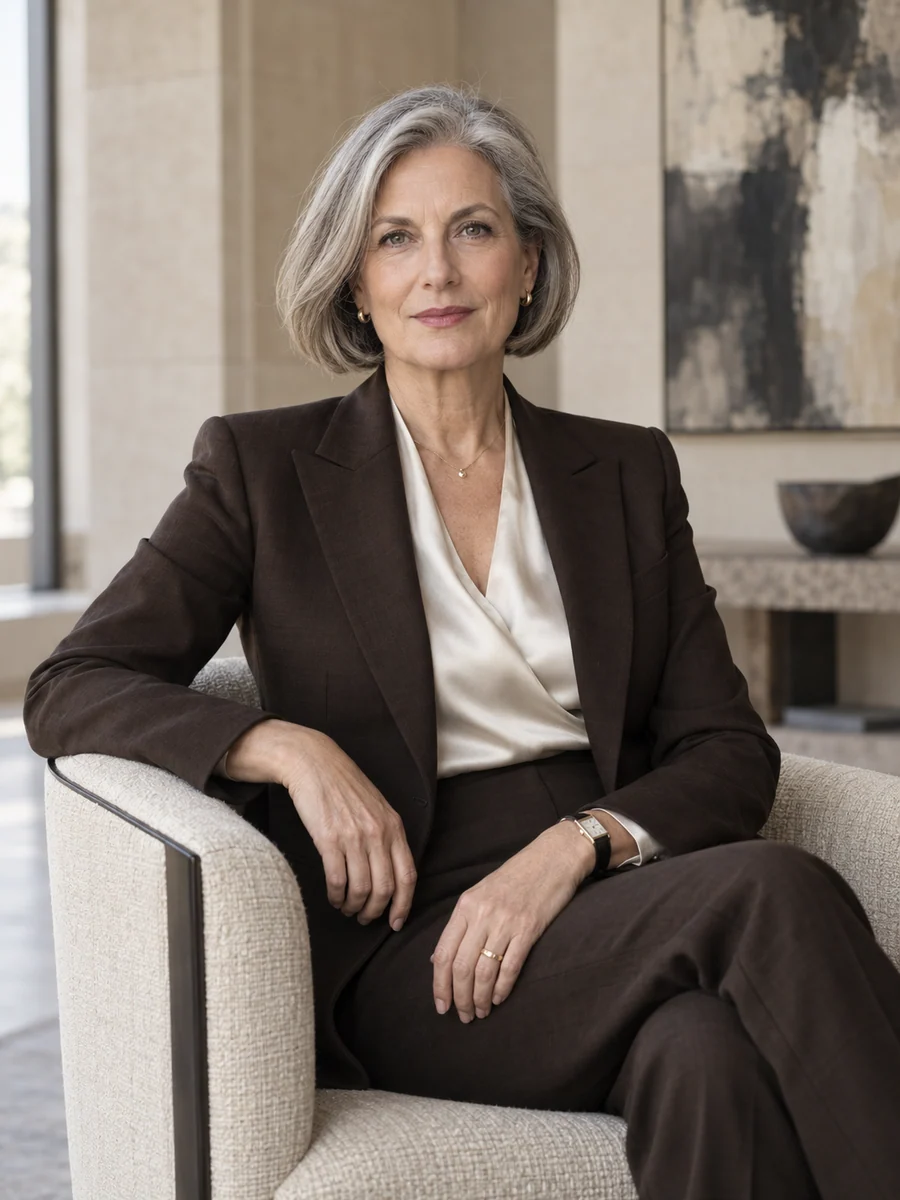
I am chief executive of Talvermark SE, a listed commercial property and casualty insurer headquartered in Hamburg. We insure small and mid-sized businesses, industrial firms and selected specialty risks in Germany, Austria, the Netherlands, Belgium and Denmark. In 2025 we reported €5.1 billion of insurance revenue, employed 6,400 people and closed the year with a Solvency II ratio of 192%. I chair the management board and answer to a supervisory board whose members include employee representatives.
I came to this role through numbers rather than sales. I trained as a mathematician, qualified as an actuary while pricing commercial property in Cologne, and spent almost six years at a Swiss reinsurer writing natural catastrophe treaties for insurers across Central and Northern Europe. From that seat I saw how primary insurers' tariffs looked to the layer that paid when they were wrong. I later ran commercial lines for a Dutch insurer in Rotterdam and joined Talvermark's management board as chief underwriting officer in 2017.
Since becoming chief executive in April 2021, I have made four choices that define my tenure so far: re-rating flood exposure after the July 2021 floods instead of excluding it, selling a personal motor book we could not run well, reporting our combined ratio to investors before the IFRS 17 discount, and withdrawing pricing authority from partners who would not share their data. Each cost us premium, goodwill or comfort with somebody. I write about the arguments behind them here, because the arguments will outlast the figures.
Flood cover kept, but priced
After the July 2021 floods we re-rated 41,000 small-business property policies in high-hazard zones instead of withdrawing cover. A prevention credit of up to 15% helped 6,300 businesses install verified measures; retention in the highest zone fell from 89% to 81%.
A smaller, clearer insurer
In 2022 we sold a €780 million personal motor book with its 410 colleagues. The transaction added 14 points to our Solvency II ratio and let us concentrate underwriting investment on commercial lines, where we had a defensible advantage.
The harder number reported first
Under IFRS 17 we lead investor reporting with the undiscounted combined ratio: 95.8% in 2025, against 92.3% after discounting. Every results statement carries the bridge between the two figures.
Authority tied to information
Between 2023 and 2025 we reduced binding-authority partners from 64 to 38. Delegated premium fell from €1.1 billion to €860 million, and the loss ratio on that book improved from 71% to 63%.
Current focus
I am working on how a commercial insurer should treat tenants and property owners differently in flood pricing, since the party able to install protection is often not the party paying the premium. I am also preparing Talvermark for the amended Solvency II framework, in particular the long-term climate scenarios it expects insurers with material exposure to analyse in their own risk and solvency assessment.
Conversations I welcome
I would consider one supervisory board or non-executive seat outside insurance competition, subject to the consent of our supervisory board and a full conflict review. I accept a small number of speaking and editorial invitations on catastrophe risk, insurance reporting and commercial distribution. I am not seeking an executive move.
Beyond the page
The record behind the perspective.
Formation
Diploma in mathematicsWeserfeld University · 1998
Actuarial qualification, non-lifeBrunnhalde Actuarial Institute · 2002
Anika brings the board the argument against her own recommendation, written as well as the argument for it. On the motor sale and on our reporting under the new accounting standard, that made our decisions slower to reach and much easier to defend afterwards.
Henrike AsmussenChair of the supervisory board, Talvermark SEThe full record ↗
Contact
I would consider one supervisory board or non-executive seat outside insurance competition, subject to the consent of our supervisory board and a full conflict review. I accept a small number of speaking and editorial invitations on catastrophe risk, insurance reporting and commercial distribution. I am not seeking an executive move.