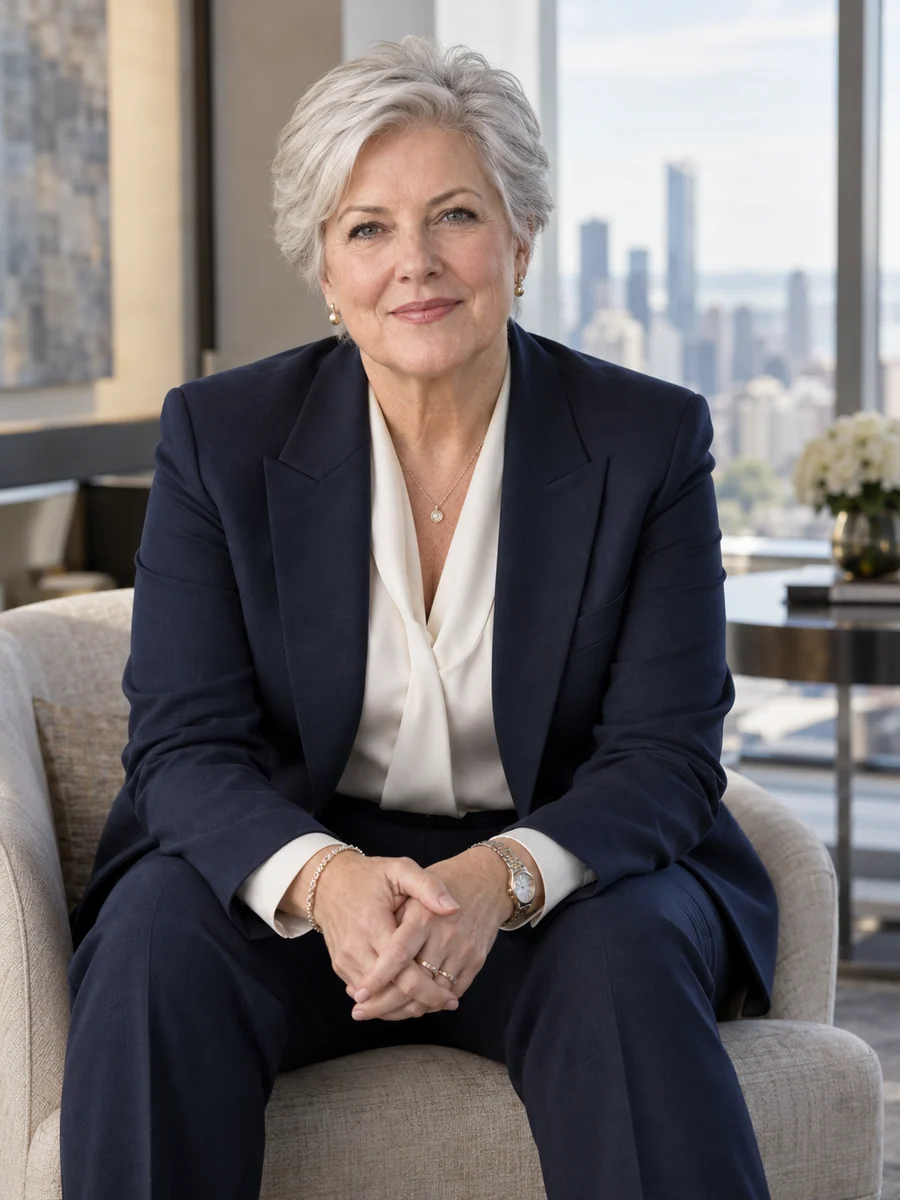
Morgan CarterChief Marketing Officer · Essays & perspective
Chief Marketing Officer / United States
Morgan Carter
Open toBoard appointments · Advisory roles · Speaking invitations
Trust in a confidence event5 min read
Bank advertising that can withstand a difficult morning
When depositors are frightened, reassurance reads as alarm and a rate special reads as need. A bank should suspend its advertising, publish within a day the figures depositors are asking about and keep its offers until the fear has passed.
Per-account bounties turn every creator's video into a sales pitch and leave the firm's review as an afterthought. Banks and brokers that work with creators should pay flat fees, approve and archive every paid post, and judge the programme by the accounts that last.
Bidding software and modelled audiences learn where a bank's borrowers already live and spend its budget there. A chief marketing officer should treat the geography of credit advertising as a fair-lending control, report it to the people who own fair lending and pay for the reach an algorithm will not choose.
I write a bank's advertising as the first disclosure its customers will read, and I judge each piece by whether it would still be true, fair and readable on the bank's worst morning.
I am executive vice president and chief marketing officer of Ledgemoor Financial Corporation, a listed bank holding company in Milwaukee whose bank has 128 branches across Wisconsin, northern Illinois and Minnesota. I am responsible for the Ledgemoor brand and for marketing our deposit, mortgage, small-business and wealth products, with 64 colleagues, two agencies and a budget of US$38 million in 2025. I report to our chief executive, Desmond Ulverstone, and twice a year I take the board risk committee through how our advertising is reviewed and whom our credit advertising actually reaches.
I came to banking sideways. I spent five years as a business reporter and personal-finance columnist at the Lakeward Sentinel in Milwaukee, writing about the products I now market, then became a copywriter at Kessel & Marr, an agency with bank and credit-union clients. At Strathmere Home Lending in Minneapolis I rewrote loan-modification letters during the foreclosure crisis and later ran consumer marketing. At Quillmark Investing in Chicago I built customer acquisition for people opening their first brokerage account, which taught me what paying creators per account does to what they say.
I joined Ledgemoor in April 2021. In March 2023, as two large banks failed elsewhere in the country, our bank lost US$1.3 billion of deposits in ten business days. That fortnight shaped most of what I have done since: publishing facts rather than reassurance, tightening how we advertise rates and discovering that our digital mortgage advertising had quietly stopped reaching several Milwaukee neighbourhoods. Each change cost something measurable.
Facts instead of reassurance in March 2023
We suspended our centenary campaign, declined to call deposits safe and published our insured share and the rules of coverage within a day. Outflows stopped at US$1.3 billion, 8.2% of deposits, and balances regained their December 2022 level by March 2024.
Mortgage advertising that reaches the whole metro
After finding that only 3.1% of our digital mortgage impressions reached Milwaukee's majority-Black and majority-Hispanic census tracts, we rebuilt delivery. Their share of our metro applications rose from 4.9% in 2023 to 10.7% in 2025, at a higher cost per application.
Creators paid for their time, not for accounts
At Quillmark Investing I ended per-account payments to 54 finance creators in 2020. Creator-sourced accounts fell 62% and acquisition cost rose by half, while twelve-month retention of those accounts rose from 48% to 71%.
A rate headline most borrowers could obtain
At Strathmere Home Lending in 2014 we replaced an as-low-as mortgage rate that 11% of borrowers obtained with the rate our median borrower received. Leads fell 23%, and complaints about advertised rates fell from 340 to 80 a year.
Current focus
I am preparing Ledgemoor's first small-business deposit campaign since 2023 with our treasury and credit teams, so that what we say about insurance coverage, sweep accounts and rates matches what a relationship manager can deliver on the first call. I am also extending our census-tract delivery reporting from mortgage advertising to home-equity and small-business credit.
Conversations I welcome
A move to another chief marketing officer post is not something I am pursuing. I would consider one non-executive directorship at a company outside banking whose customers depend on what it tells them about money, health or safety, with my chief executive's consent and a conflict review. I also accept a few advisory conversations and speaking invitations a year on advertising in regulated finance.
Beyond the page
The record behind the perspective.
In the boardroom
Ardell Street Housing TrustDirector; chair of the lending programme committee · March 2022–present
Formation
Bachelor of Arts in journalismOstwick College · 1998
Master of Business Administration (part-time)Tamsworth University · 2011
Morgan was the first marketing officer to bring this committee a list of advertisements withdrawn after launch, with the reason for each. In March 2023 she talked the executive team out of a reassurance campaign in under an hour, and the committee has had no reason to regret it.
Philippa StrandChair, risk committee, Ledgemoor Financial CorporationThe full record ↗
Contact
A move to another chief marketing officer post is not something I am pursuing. I would consider one non-executive directorship at a company outside banking whose customers depend on what it tells them about money, health or safety, with my chief executive's consent and a conflict review. I also accept a few advisory conversations and speaking invitations a year on advertising in regulated finance.