Chief Financial Officer India
Reading the payment terms before the price
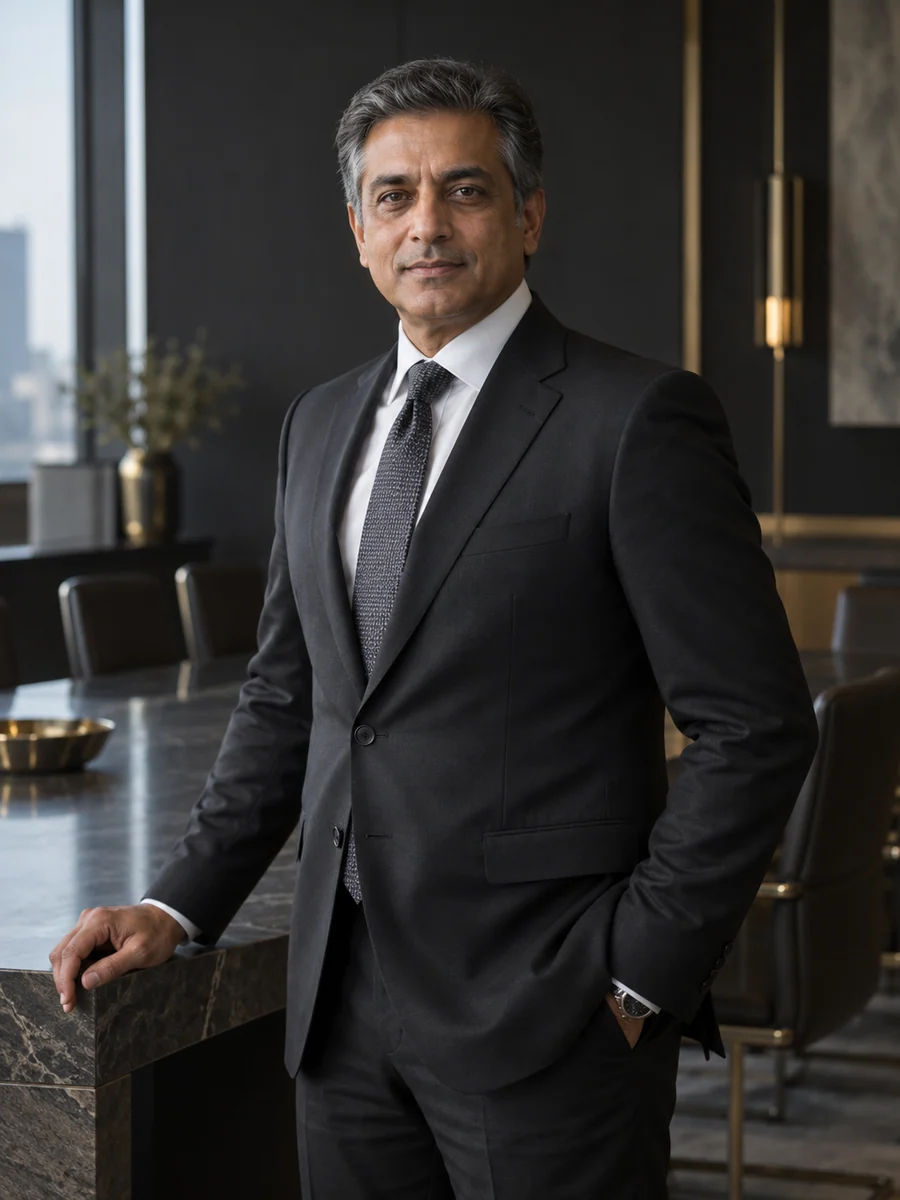
My first lesson in project finance came from a stack of conveyor idlers standing in the monsoon rain. In 2001 I was the junior accountant in a public-sector company's site office in Odisha, where we were supplying and erecting material handling equipment for a blast-furnace expansion. Our books showed the idlers as supplied and seventy per cent paid. The client's engineers recorded them as not yet installed, and their contract said the remaining thirty per cent waited on installation. Both records were correct. The cash followed only one of them, and since then I have read every contract's payment terms before its price.
I grew up in Nagpur, where my father ran a hardware shop in Itwari and kept his credit book in pencil, so that a customer's promise could be rubbed out once it was kept. I studied commerce at Kherwadkar College of Commerce, graduating in 1995, and qualified as a chartered accountant in November 1997 after articled training with Wadhwakar & Joglekar, a Nagpur practice whose clients included coal transporters, ginning mills and engineering workshops along the Hingna road. I stayed two more years as an audit senior. Audit taught me to test a number. It did not teach me how a number is made.
In February 2000 I joined Nirmitika Heavy Engineering Limited, a fictional central public sector enterprise in Nagpur that built cranes, conveyors and mill equipment for steel plants and power stations. I spent four years in site accounts in Odisha and five in contract finance at the corporate office, preparing escalation claims under price-variation clauses and defending them before clients and government auditors. A public-sector company keeps excellent files, because it expects every decision to be questioned years later. I learnt to record a decision as though it would be read aloud at a hearing, and that is still how I write board papers.
In 2009 I moved to Pune as head of commercial finance for Feldhain Thermal Systems India Private Limited, the Indian subsidiary of a fictional German maker of industrial boilers and heat-recovery systems. My job was to review every bid above ₹50 crore before it left the building: milestones, bank guarantees, liquidated damages, imported content priced in euros, and the cash curve over the life of the contract. The parent's project controllers refused to approve any bid whose cash stayed negative beyond a set period, however attractive its margin. I thought them rigid. Within two years the rule was mine.
In March 2014 I became CFO of Varunika Castings Private Limited in Kolhapur, a foundry founded by Shrikant Mohite that made grey and ductile iron castings for tractor, commercial-vehicle and wind-turbine customers. Tamarind Peak Capital, a fictional private equity fund, had bought 46 per cent a year earlier. Revenue grew from ₹640 crore to ₹1,060 crore over my five years. The fund needed monthly reporting it could rely on, a refinancing and eventually a sale. In that sale I took ₹21 crore out of the adjusted EBITDA our own advisers had drafted. It lowered the price and, I believe, made the transaction possible. I left once the buyer had folded our finance team into its own.
Sudhir Kanetkar, Ilvara's managing director, asked me to join as CFO in June 2019. The company was profitable, respected by its clients and carrying more debt than its cash flow could comfortably service. Its divisions measured themselves on order intake and revenue, and the balance sheet absorbed everything else. Since then we have changed how bids are approved, how plate and currency are bought, how bank limits are managed and how promoter-group suppliers compete for our work. Some of those changes cost us orders. Our order book is now larger than it has ever been, and it is cheaper to carry.
I lead 145 people in finance, treasury, tax, investor relations and commercial finance across Vadodara, the Dahej yard and our subsidiary in the United Arab Emirates, with six direct reports. Internal audit reports to the chair of our Audit Committee, which I attend as an invitee. The Rajyaguru family, who founded Ilvara, hold 52 per cent of its shares. Our executive chairman, Mihir Rajyaguru, and I disagree often and, I think, usefully, because we both put our disagreements in writing and let the board decide.
People in our industry probably know me for three positions. A contract asset is credit we have extended to a client without anyone approving it, and should be aged and priced like any other credit. A bank limit for guarantees is capital, and every bid should be charged for the share it consumes. A government incentive is a conditional receipt, never a reason on its own to build a plant. I hold these views because I have watched each alternative hurt a company I worked for, and I would now like to test them from the other side of an Audit Committee table, as an independent director.
Open to Board appointments · Speaking invitations
Languages / English · Hindi · Marathi · Gujarati
A leadership conviction
Every order we sign borrows something: rupees from our balance sheet, plate from a mill, a bank's willingness to stand behind us. I want the board to see each of those loans before it approves the order, not after the client has paid.
- Consolidated revenue, FY2025-26
- ₹3,140 Cr
- Process Equipment ₹1,820 Cr; Projects ₹1,320 Cr
- Order book, March 2026
- ₹6,850 Cr
- About 2.2 years of revenue
- Net debt to EBITDA, March 2026
- 0.4x
- Down from 4.0x in March 2019
Board & advisory record
Current appointments
Ilvara Engineering FZE
Director of the wholly owned UAE subsidiary, in an executive capacity
2020–present
Education & credentials
- Bachelor of Commerce
- Kherwadkar College of Commerce · 1995
- Chartered accountant, after articled training
- Wadhwakar & Joglekar · 1997
Perspectives from colleagues
Arjun's papers arrive with the uncomfortable number on the first page. When a site had counted uninstalled equipment as progress, he rang me himself before the auditors began their review, with the cause and the fix already written. In a promoter-led company, that habit is worth more to an Audit Committee chair than any presentation.
I argued hard against Arjun's ₹130 crore. He was right, and the buyer's diligence finished in six weeks with nothing left to renegotiate. I have since asked every CFO in our portfolio to prepare a sale as though he were sitting across the table.
We lost two tenders over Arjun's billing terms, and I told him so in front of the board. Three years later my division was producing cash for the first time in a decade, and two of those clients had signed the same terms. He has never once reminded me of the argument.