An insurer earns the right to use its members' data when the people who own each number can explain how it reached a price, a reserve or a claim decision.
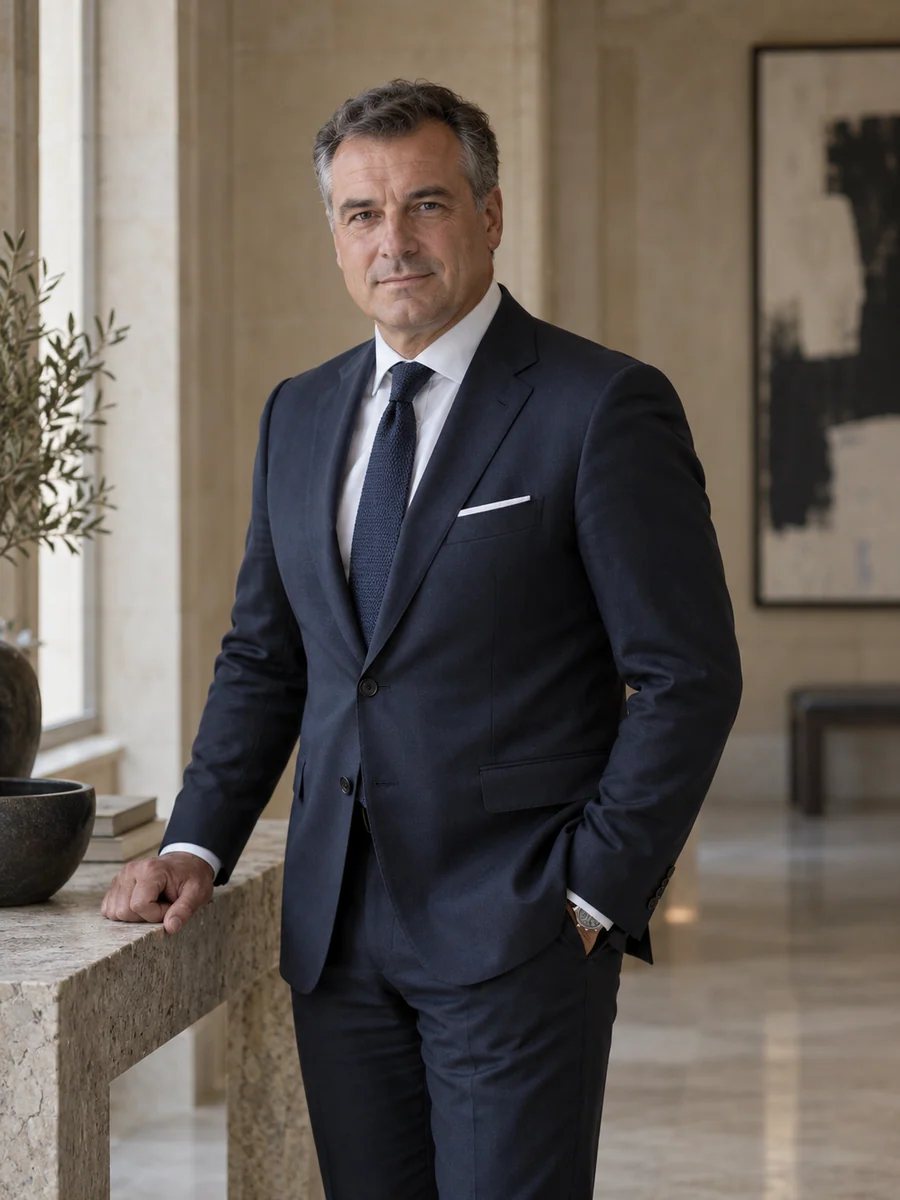
I am chief data officer of Arduvelle Assurances, a Belgian cooperative non-life insurer owned by about 410,000 member-policyholders. We wrote €612 million of gross premium in 2025 across home, motor, family liability, legal expenses, small-business cover and income protection for self-employed people, sold through 230 tied agents and independent brokers from our head office in Namur. I sit on the executive committee and lead 64 colleagues in data governance, platform engineering, analytics and reporting data. Pricing remains with the chief actuary and claims decisions with the claims director, while our data protection officer reports independently of me.
I began in 1995 as a motor claims handler in Liège, paying garages and arguing over liability splits with other insurers. That desk taught me that a claim file is written to settle one case, not to price the next thousand or to reserve for those still unpaid. Later I spent five years in Copenhagen building reserving data for a Danish mutual as it prepared for Solvency II. Both experiences shaped how I divide responsibility: operations define what happened, actuaries define how it is projected, and my office keeps the two connected and reconciled.
The decisions described on this site each carried a cost. We made claims handlers record expected recoveries separately, which restated our motor reserve upward by €7.2 million. We launched an income-protection triage model with a manual step for Dutch- and German-language claims rather than wait, or serve French speakers first. We capped the gap between renewing and new home customers and gave up €5.3 million of premium in 2025. None of these was a data project in isolation; each needed a business owner willing to accept the consequence in front of the board.
A motor reserve restated with its recoveries visible
Recording expected and received recoveries as separate ledger entries cut the reserving team's manual adjustments from 41 to 6 a quarter. Rebuilding the history in 2018 added €7.2 million to the motor best estimate.
Triage that routes claims but never refuses them
Our income-protection triage model can send a claim to a faster route but cannot decline or reduce it. Median time to first payment fell from 19 days to 10, and the gap between language groups narrowed to four points.
Long-standing members no longer pay a hidden premium
In 2024 members with ten or more years' tenure paid a median 13% more for home cover than an equivalent new customer. A cap approved by the board brought the gap to 3.1% by September 2026.
Current focus
I am building the register our board will use to oversee pricing and claims models under the EU AI Act. I have started with income-protection underwriting, which I treat as one of the Act's high-risk uses for health insurance unless our supervisors read it differently.
Conversations I welcome
I would consider one non-executive seat on the audit or risk committee of a mutual, cooperative or mid-size European financial institution, at about twenty-five days a year, subject to my board's consent and a conflict review.