The person behind the perspective
The completed file did not tell me everything about the earlier decision.
I became interested in insurance information because its meaning changes as an event develops. A claim arrives with an incomplete account. Further material is recorded, a decision is made and sometimes the case reopens. The final file can look so coherent that the uncertainty of the earlier moment disappears. My work has been to preserve that uncertainty where it matters, allowing people to examine a past decision without quietly lending its maker knowledge acquired afterwards.
I completed applied statistics at the fictional Tsunavelle Institute of Statistics in March 1990 and joined Kiyoremi Analytics the following month. I was an individual contributor in an eight-person analytical group, with no expense delegation. The work taught me to distinguish a record assembled for analysis from the sequence through which the underlying institution learned what had happened. A complete extract was useful, but completeness at the time of extraction did not mean all its contents had been available at the time of the decision being studied.
In April 1997 I became an engagement lead. By 2003 my remit covered seventeen colleagues through three direct reports and JPY 84 million annual delivery expense. Kiyoremi's JPY 2.4 billion fee revenue and 130 employees belonged to the advisory business, not my personal authority. I wanted to stay with insurance information beyond a single assignment. Joining Soravane Assurance as head of claims information in July 2004 meant accepting responsibility for how a definition continued to be used after the first explanation had been forgotten.
I made an error in 2007 that remains part of this account. I accepted 7800 closure events as a count of final resolutions. Within ninety days, 260 of the associated claims had reopened. Kenji Aritsune challenged the word final. We retained the closure events and added status at a stated cutoff, spending JPY 48 million on correction and reporting work. The observation did not establish that the remaining claims could never reopen. I had turned a recorded event into a stronger conclusion about the future, and the correction needed to name that mistake. I wanted colleagues to be able to question the revised account too, because replacing a confident headline should not make its successor immune from examination.
My insurance-data director appointment began in April 2012. The work widened from claims reporting to information that crossed policy, property and analytical records. In 2016 we examined 18700 property-location entries whose map markers appeared equally precise. The underlying evidence differed: 14300 were classified at building level, 3200 at postcode level and 1200 remained unresolved. We preserved those distinctions rather than make the map look complete by removing them. A more precise-looking display would not have supplied a better foundation for a location-dependent decision.
I became CDO in April 2019 and now lead 124 data colleagues through seven direct reports. My FY 2026–27 expense delegation is JPY 1.86 billion. Soravane's FY 2025–26 gross written premium of JPY 198 billion and current 5700 employees describe the company separately. The appointment includes executive presentations to the board; it does not include a statutory directorship. Actuarial, underwriting, claims, finance and technology leaders retain responsibilities that a large data remit does not transfer to me.
Recent decisions have returned to the relationship between knowledge and time. A first-notice evaluation contained settlement information entered later. Policy histories needed both the date a change referred to and the date the institution recorded it. A claims-duration account needed open cases to remain visible beside a median calculated only from completed ones. Each question required a different reconstruction. None could be resolved by treating the latest database state as a complete account of what people knew at every earlier stage.
I am interested in a first board contribution grounded in those experiences, subject to preparation and the institution's assessment. I would help colleagues ask whether a confident retrospective account has preserved the circumstances of the decision it describes. I would also expect to learn from the professional owners whose judgements the data supports. Every person, employer and event here is invented. The career is designed to show how a CDO can explain changing responsibility, an owned failure and specific limits of evidence without claiming authority over the insurer's entire business or presenting a technical correction as a measured commercial result.
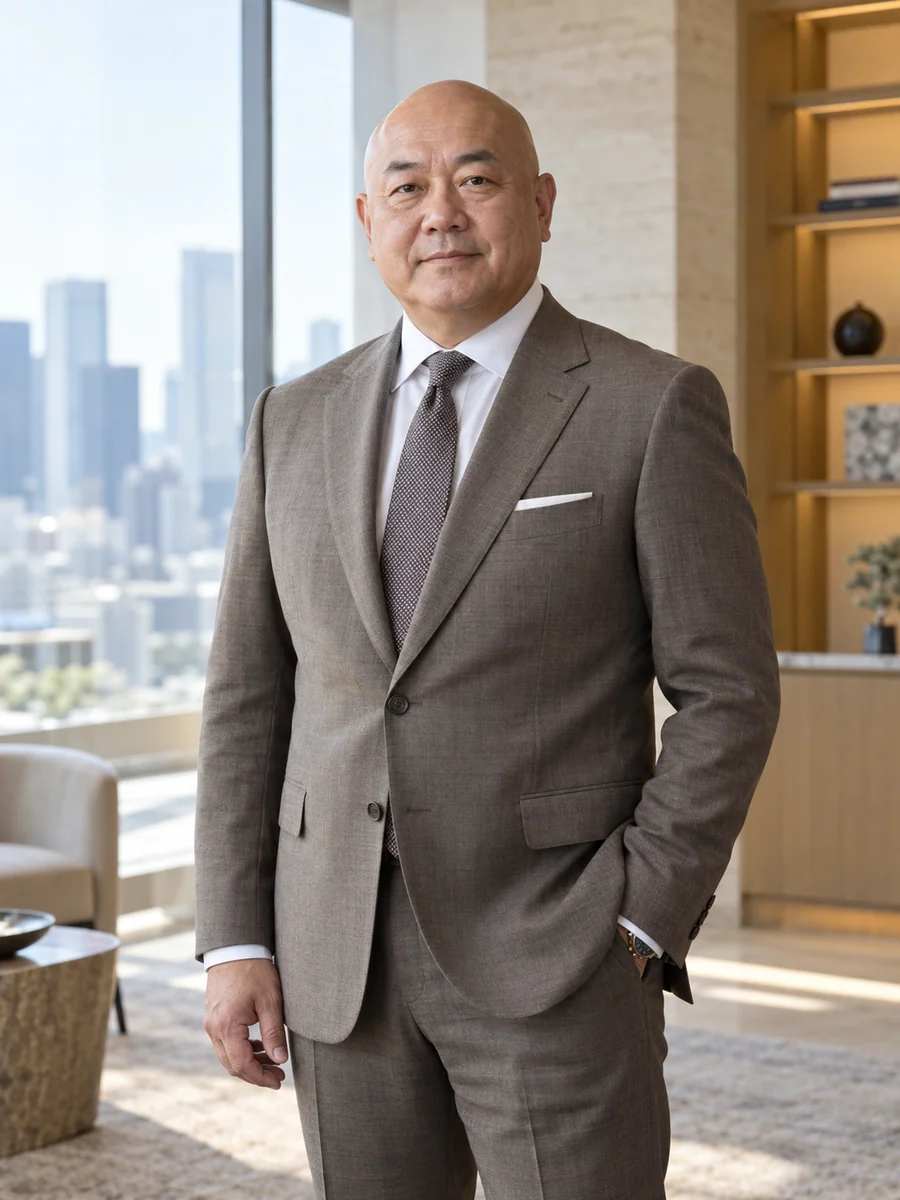
In my own words
I ask an insurance dataset to carry its history with it. What we know after a claim closes may be useful for learning, but it cannot be treated as information available when the claim first arrived. A policy change also has a history of being recorded, distinct from the date to which it refers. I want our data to make those differences inspectable before anyone relies on a retrospective result to justify a future decision.
Tadashi Mizukura
Career
Chapters of accountability
2019 — present
Chief Data Officer
Soravane Assurance
Preserve information history behind insurance evaluation, policy changes and claims reporting.
2012 — 2019
Director of insurance data
Soravane Assurance
Make the precision and provenance of insurance evidence visible across analytical uses.
2004 — 2012
Head of claims information
Soravane Assurance
Maintain claims-event reporting and correct an owned overstatement about final resolution.
1997 — 2004
Engagement Lead
Kiyoremi Analytics
Lead analytical assignments that distinguish a completed file from the history of institutional knowledge.
1990 — 1997
Statistical Analyst
Kiyoremi Analytics
Examine how the sequence of recorded information affects the question an extract can answer.
Education
Formation
- Bachelor of applied statisticsTsunavelle Institute of Statistics1990
Working languagesJapanese · English