Prepared for boards, nomination committees & search advisers

File No. CSO-006

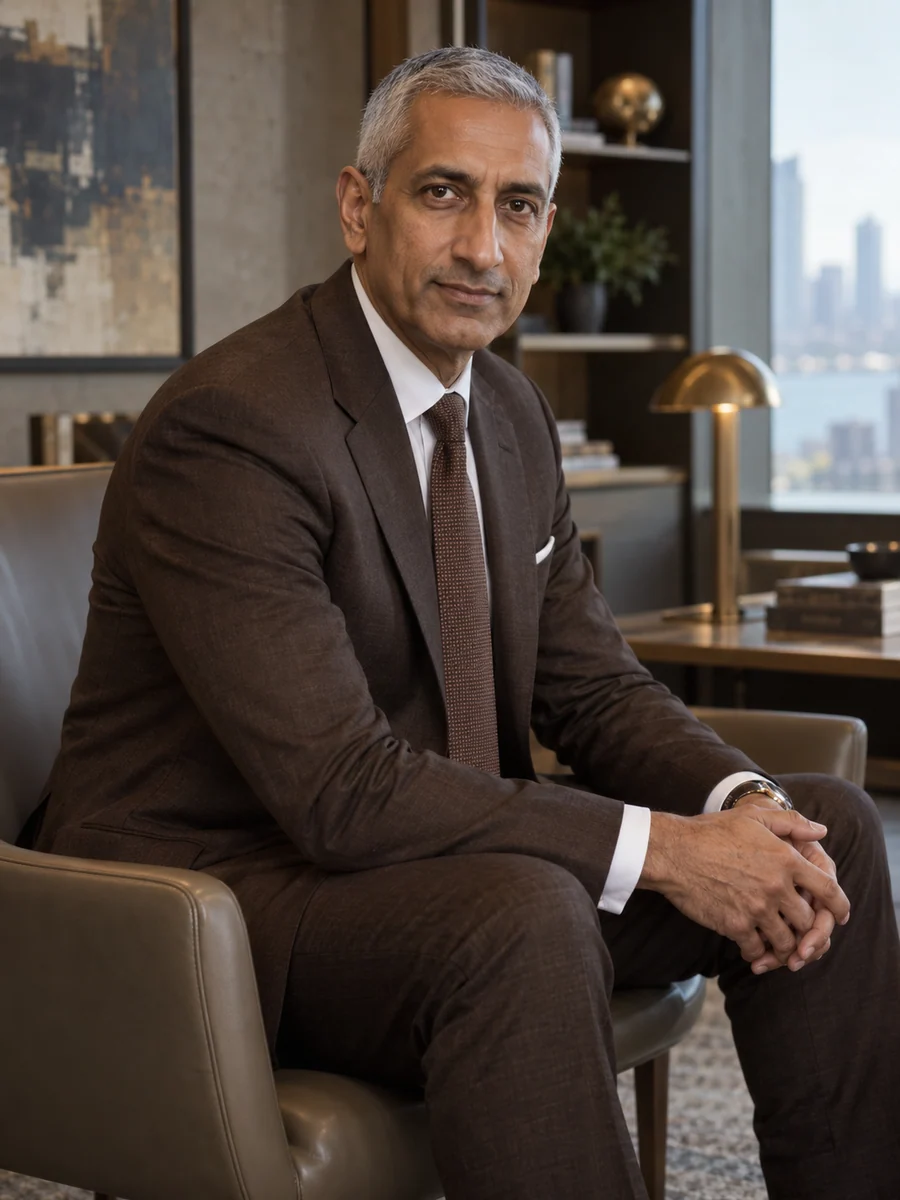
Portrait of Raphael Laurier
Raphael Laurier

Raphael Laurier

Portfolio breadth matters only when the underlying dependencies are different.

SubjectRaphael Laurier
PositionChief Strategy Officer
BaseCanada
LanguagesEnglish, French
StatusI would consider a discussion about pharmaceutical portfolio choices where a new category, market or transaction needs a clearer account of the dependence it changes.

Summary

I began in healthcare business research, where a large part of the work involved making a complicated market understandable to someone deciding where to invest attention. A category was useful: it let a reader see an unfamiliar activity in relation to something already known. Over time I learned that the same convenience could become a weakness. Once the category appeared in a portfolio chart, people could forget the dependencies that had been compressed into its label. My career has increasingly concerned the questions needed to bring those dependencies back into the decision.

Portfolio breadth matters only when the underlying dependencies are different.

I examine the gap between the way a pharmaceutical portfolio is described and the commercial dependencies that hold it together. Nine brands can share a purchasing route. Two markets can depend on one distributor. An early development activity and an established medicine may both appear as a line on the same chart without providing comparable evidence. My work asks what the collection actually changes for the business, while preserving the professional judgements that a commercial account cannot make.

At the fictional Vaurenne Therapeutics, I lead thirty-eight strategy colleagues through five direct reports. My C$9.6 million delegated 2026 function expense is distinct from the company’s C$860 million 2025 revenue and its 1850-person workforce. I coordinate the strategic account and present it in an executive capacity. Scientific, medical, quality, safety, regulatory and capital decisions remain with their responsible owners. The size of the business matters, but it does not make every decision inside it part of my personal authority.

This record follows an analyst into advisory leadership, portfolio planning and corporate strategy. It includes the nine-brand classification I got wrong, a geographical expansion with a shared channel, a stage-of-development distinction, an acquisition we declined and the support needs of a smaller established portfolio. Every person, company and outcome is invented. The purpose is to show the kind of evidence a leader could prepare when explaining a strategic contribution through choices rather than the number of activities listed beneath a title.

An acquisition added categories without removing a shared buyer dependence

In 2023 a proposed portfolio carried C$84 million in trailing annual revenue, with 45% tied to the same institutional purchasing group. I recommended declining despite the appeal of new therapeutic-area labels. We retained C$1.7 million in diligence expense and did not describe the decision as a measured loss avoided.

I corrected a diversification story built on nine brand names

My 2008 classification treated nine brands as evidence of broader exposure before identifying that six shared one institutional procurement route. The research and reclassification cost C$620,000. I distinguish that mistake in the commercial account from any judgement about the medicines themselves.

The number of initiatives did not describe their stage of evidence

A 2021 portfolio review separated fourteen initiatives into nine early development activities and five established-medicine extensions. C$1.3 million in analysis supported a more qualified strategic description. The count did not become a claim that fourteen products were available, equivalent or likely to succeed.

Current focus

I am considering how a portfolio retains its less visible dependencies when it is summarised for a decision. The work includes shared buyers and channels, differences in development stage and the support requirements of established activities. A useful account should remain intelligible without flattening those distinctions into a single count or treating a strategic interpretation as a medical conclusion.

Conversations I welcome

I would consider a discussion about pharmaceutical portfolio choices where a new category, market or transaction needs a clearer account of the dependence it changes. A first-board conversation would require a suitable remit, preparation, conflict review and employer agreement. This invented profile offers no actual pharmaceutical or advisory service; a real leader should use verified experience and an authorised route for an appropriately bounded introduction.

Exhibit ATrack record

ItemMeasureFigure
01Strategy colleaguesFive direct reports at October 2026; company workforce 185038
02Delegated strategy expense2026 function budget; no implied medical, regulatory or capital authorityC$9.6 m
03Years in healthcare business strategyCareer began August 1989; board presentations since September 2017 are executive exposure37

Exhibit BStatement of approach

I want a portfolio discussion to show what its categories conceal. Different medicine names, countries or development stages may still rely on the same purchasing route, distributor or specialist capability. I ask which dependency has actually changed before describing the collection as broader. That question should improve the strategic account without substituting a commercial interpretation for medical, scientific or regulatory judgement.

Signed — Raphael Laurier

Exhibit CSelected matters

Matter 01Ref. CSO-006-M01

The new therapeutic categories carried a familiar purchasing dependence

In 2023 we assessed an acquisition whose portfolio carried C$84 million in trailing annual revenue. Its therapeutic-area labels differed from much of our existing business, making the proposal attractive as a diversification story. The commercial review found that 45% of the proposed portfolio revenue was tied to the same institutional purchasing group already important to our own portfolio. The labels had broadened, but a substantial part of the buyer dependence had not. I wanted that distinction inside the acquisition decision rather than left as a qualification beneath it.

Marc Auvrenay, our fictional corporate development head, argued that the therapeutic breadth still had strategic value. He did not dispute the concentration; he believed the new categories justified accepting it. That was a serious alternative, not a careless enthusiasm for a transaction. I disagreed about the weight the proposal placed on diversification. The case needed to explain why the additional dependence was acceptable on its own terms, rather than imply that a different set of medicines automatically reduced the exposure we already carried.

I recommended declining the proposal after C$1.7 million in diligence expense. The responsible decision-makers accepted that recommendation. Specialist teams retained the assessment of the products, their quality, scientific evidence, permissions and contractual position. I did not interpret the commercial concentration as evidence that a medicine was unsuitable or that a purchasing relationship would fail. The strategic question was whether this transaction provided the kind of breadth we were seeking at that point in the portfolio's development.

We gave up access to the new categories and accepted that diligence expenditure would not lead to an acquisition. That consequence mattered. It would be easy to turn a declined transaction into a story in which nothing was lost because a risk had been discovered. Here the alternative retained genuine appeal, and the review cost remained real. I do not claim that the decision prevented a quantifiable future loss; the counterfactual is not available in this fictional record.

The case explains how I use a portfolio map. It should identify the mechanism through which a transaction changes the business, including the dependence it adds or leaves intact. A different category can still be worthwhile. It simply needs a reason more precise than the visual impression of another colour on the acquisition slide.
Matter 02Ref. CSO-006-M02

Two proposed markets still relied on one distribution group

Our 2016 international expansion assessment covered two markets and modelled C$135 million in annual sales at maturity. The model attributed 56% to one proposed distribution group. The geographical presentation made the opportunity look spread across two settings, while the commercial route concentrated a substantial part of the undertaking in the same counterpart. I wanted the strategy discussion to retain both facts. The sales estimate was prospective, and no part of this case treats it as achieved revenue or evidence that product permissions were settled.

The expansion sponsors preferred preparing both markets together. They expected the joint approach to make the opportunity more meaningful to the distributor and reduce repeated preparation. I understood that argument: working through the same group could offer practical advantages as well as concentration. My concern was that geographical breadth had been used as a shorthand for greater independence. If the programme depended on one relationship for more than half the modelled sales, the institution needed to choose that dependence consciously.

I supported commercial preparation for one market first, with C$2.4 million in assessment and preparation expense. The second remained an option for later consideration. Local professional teams retained the medical, regulatory, contractual and operating assessments required for the actual business. My recommendation did not establish that either market could be entered or prescribe how a medicine should be supplied. It concerned the scale of commercial commitment we were ready to prepare while examining the proposed channel relationship more closely.

The choice gave up the simultaneous launch ambition and some of the simplicity of a combined negotiation. It also required us to explain why a smaller immediate undertaking could still fit a broader long-term direction. The sponsors' objection remained relevant; preparation in sequence could carry duplicated effort. I did not claim that the selected approach removed distributor dependence or proved that one market was intrinsically preferable. It made the initial undertaking proportionate to the evidence we were prepared to use.

For my public record, the useful distinction is between location and dependence. A map can show two countries correctly while saying little about the counterpart through which the business expects to reach them. I want a strategic account that allows both the attraction of the route and its concentration to survive the presentation.

Matter 03Ref. CSO-006-M03

Fourteen initiatives were not fourteen equivalent portfolio positions

In 2021 our strategic portfolio summary placed fourteen initiatives in a single row of progress cards. Nine were early development activities and five concerned extensions of established medicines. The format made the collection easy to count and difficult to interpret. Readers could see breadth without seeing how much evidence sat behind each part. I did not want a convenient unit of presentation to imply that fourteen activities represented fourteen comparable products, revenue streams or prospects of success.

The programme sponsors worried that separating the groups would make the earlier work appear less valuable. Those activities represented possible future directions, and they wanted the corporate account to show the effort behind them. I agreed that early work deserved a place. The disagreement concerned what its place should mean. Treating different stages as equivalent did not respect the early activities; it asked them to support a claim they could not yet substantiate and obscured the established work's different responsibilities.

We spent C$1.3 million on portfolio analysis and revised the strategic description to show the nine early activities separately from the five established-medicine extensions. Scientific and medical teams retained their evidence assessments, with regulatory and financial colleagues responsible for their own conclusions. I did not assign clinical probabilities or convert the early activities into a valuation. The change made the institution's business account more precise about the type of work it was considering and the uncertainty that remained.

We gave up a simple fourteen-item headline. The new presentation took longer to explain and did not offer one aggregate measure that could be carried unchanged into every conversation. That was the cost of preserving an important distinction. It was still possible to discuss the portfolio as a whole, but the discussion had to make clear which conclusions concerned established activities and which concerned options under development. The count remained a count of initiatives, not a substitute for their evidence.

The outcome I can claim is a clearer strategic account. This fictional case does not report a product approval, clinical result or subsequent commercial success. It shows how a CSO can help a decision-maker interpret the collection without assuming the authority of the specialists who determine what each activity can responsibly claim.

Matter 04Ref. CSO-006-M04

I counted nine brands before examining their shared buying route

In 2008 I endorsed a portfolio description that used nine brand names as evidence of diversification. I had examined the differences between the categories but had not given equal attention to the route through which institutions purchased them. A later review found that six relied on one procurement route. The original account was not arithmetically wrong: there were nine names. It was strategically incomplete because I had allowed that count to stand in for a more demanding explanation of independent commercial exposure.

Camille Dervelune, our fictional portfolio research lead, challenged the classification. Colleagues responsible for the brands argued that their different histories, uses and market positions should not disappear into one concentration measure. They were right about the need to preserve those differences. My response was to retain the product distinctions while withdrawing the inference that each name represented a separate buying dependence. The correction concerned our business description, not an assessment of whether the medicines were appropriate or valuable.

I supported C$620,000 in additional research and reclassification. The work brought the common procurement route into the strategic discussion and changed the way we explained the nine-brand portfolio. Commercial and professional owners retained their respective assessments. We did not prescribe a clinical substitution, alter a product claim or assume that a shared route meant an inevitable loss. The evidence established a connection that my earlier account had overlooked, not a prediction of what the counterpart would do.

The correction cost money and made my earlier recommendation less persuasive. It also disappointed colleagues who had used the breadth story in their own planning. I could not ask them to accept the revised interpretation while presenting myself as the person who had discovered a problem belonging entirely to someone else. The original classification was mine to challenge before I supported it. Keeping that responsibility visible is part of why the case belongs in this record.

I learned to ask which differences matter to the decision at hand. Product distinctions can be real while a commercial dependency remains shared. A useful portfolio account needs room for both. The lesson was not to distrust every count, but to avoid letting a count answer a question that requires an explanation of relationships.

Matter 05Ref. CSO-006-M05

The smaller portfolio still needed a complete support account

A 2025 review considered a smaller established portfolio with C$26 million in annual revenue. Its annual support-cost estimate was C$4.2 million. Because the portfolio attracted less growth attention, the initial strategy discussion treated that support work as a secondary issue while considering longer-term options. I wanted it brought into the main account. Relative size did not remove the work required to maintain the business, and a possible future transaction did not by itself change present responsibilities.

Some colleagues wanted to focus immediately on disposal options. They argued that management attention spent examining a small portfolio would delay the larger strategic choices. I accepted that attention was limited and that ownership options deserved examination. My concern was the implicit assumption that the current support undertaking could be made residual while those options remained unresolved. The commercial direction and the existing work had to be considered together, with the relevant professional owners explaining what the latter required.

I supported keeping the C$4.2 million annual support estimate visible in planning while the long-term options were reviewed. This was not a margin calculation formed by subtracting that amount from C$26 million revenue: the estimate did not represent all costs or a complete accounting period analysis. Medical, quality, safety, regulatory, operational and contractual judgements remained with qualified owners. My contribution was to prevent the strategic description from implying that a smaller revenue line had become a negligible institutional undertaking.

The choice retained management work that the disposal argument hoped to reduce. It did not settle the eventual ownership question, and it did not promise uninterrupted supply or a particular transaction outcome. We kept planning for the responsibilities that existed while examining what might change them. That required a more patient account than a simple decision to prioritise growth assets and move on. The smaller portfolio's needs had to remain visible even when they were not the centre of the company's ambition.

I use the case to explain that a strategy includes the activities whose future is still being decided. A portfolio review should show the cost and attention attached to that interval. Otherwise an option in the future can be mistaken for a change that has already released the institution from work in the present.

Exhibit DCareer history

  1. 2017 — present

    Chief Strategy Officer

    Vaurenne Therapeutics

    Examine portfolio breadth through dependencies, evidence stages and the resources attached to established activities.

  2. 2010 — 2017

    Vice President of corporate strategy

    Vaurenne Therapeutics

    Connect geographical and portfolio choices to their commercial routes and the limits of prospective evidence.

  3. 2003 — 2010

    Head of portfolio planning

    Vaurenne Therapeutics

    Take continuing responsibility for the portfolio account, including correction of an owned nine-brand classification error.

  4. 1996 — 2003

    Engagement Director

    Orvanel Health Advisory

    Lead healthcare business research and recommendations within a defined advisory remit.

  5. 1989 — 1996

    Healthcare Business Analyst

    Orvanel Health Advisory

    Learn to reconcile commercial definitions and preserve the limits of a healthcare market comparison.

Exhibit EFormation

  • Bachelor of business administrationValcerin School of Management1989

Exhibit FReferences

Raphael accepted that our nine-brand description had given the names too much weight. The correction made the shared purchasing route visible without turning it into a judgement about the medicines.
Camille DerveluneFictional portfolio research lead; colleague on the 2008 classification review
I supported the acquisition’s wider therapeutic reach. Raphael kept the institutional buyer concentration in the decision, including the cost of declining after diligence.
Marc AuvrenayFictional corporate development head; counterpart in the 2023 acquisition assessment

Exhibit GPublished views

CorrespondenceNext steps

An invitation

Contact

I would consider a discussion about pharmaceutical portfolio choices where a new category, market or transaction needs a clearer account of the dependence it changes. A first-board conversation would require a suitable remit, preparation, conflict review and employer agreement. This invented profile offers no actual pharmaceutical or advisory service; a real leader should use verified experience and an authorised route for an appropriately bounded introduction.

Open to
  • Board appointments
  • Speaking invitations

office@raphaellaurier.example