Intan SantosoLeadership review 2026

Leadership review

Intan Santoso

Chief Strategy Officer · Singapore / Southeast Asia

An insurance growth strategy must explain the obligation that remains when the sales relationship ends.

Open to
  • Board appointments
  • Speaking invitations
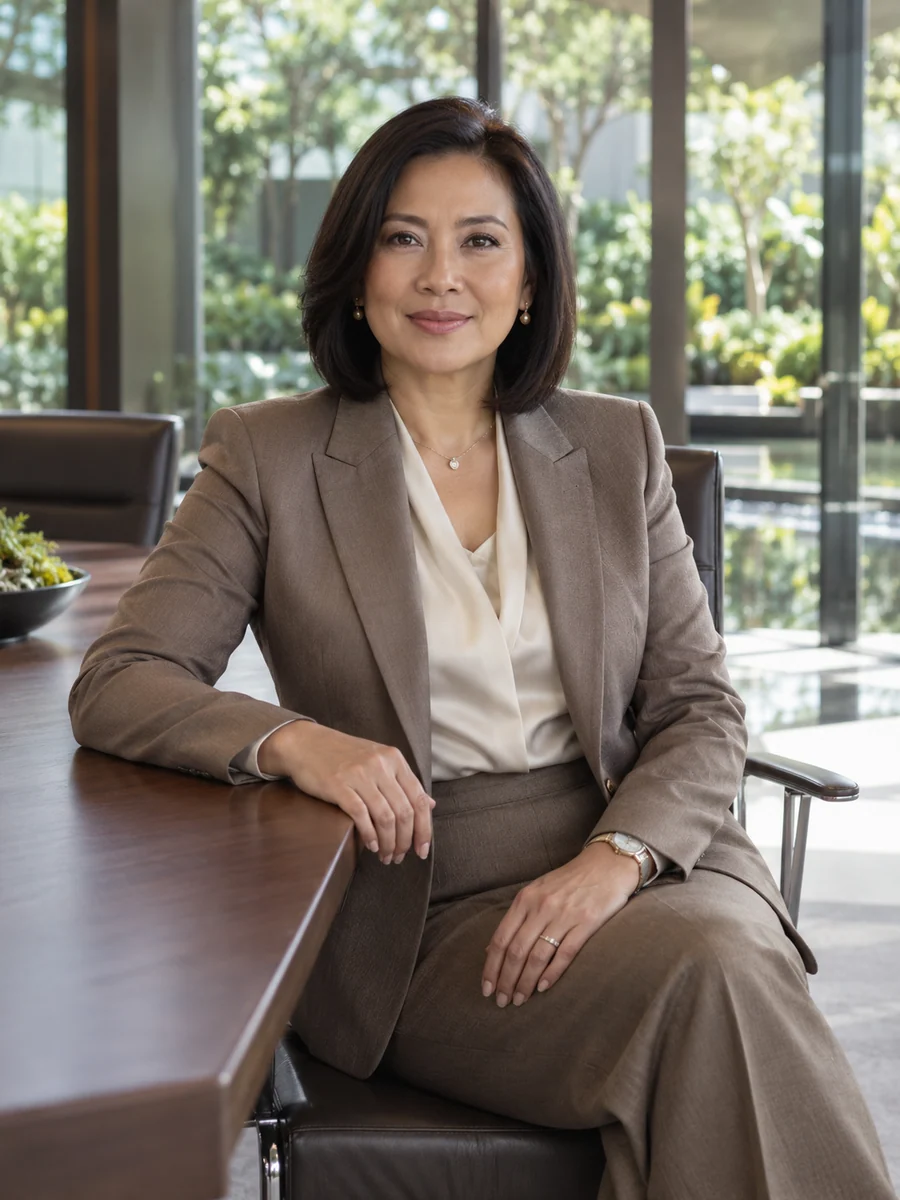
Portrait of Intan Santoso

An insurance growth strategy must explain the obligation that remains when the sales relationship ends.

I examine the continuing commitment behind an insurance growth proposal. A distributor may introduce the customer, a campaign may explain the offer and a partnership may define a commercial period. The insurer still needs to understand what it will be responsible for when that period changes. My work connects the appealing growth account with the less visible account of what remains, so that the institution can consider both before making a commitment.

At the fictional Suraveth Assurance in Singapore, I lead forty-eight strategy colleagues through five direct reports with S$8.8 million delegated 2026 expense. The group recorded S$1.85 billion gross written premium in 2025 and has 2300 employees. These company measures do not describe my personal authority or establish profitability. Underwriting, actuarial assessment, claims, reserving, compliance, operations and capital sit with their own leaders. I coordinate the strategic case and the dependencies it needs to make clear.

My career began in advisory analysis in 1992 and moved through distribution planning into corporate strategy. The decisions here include an acquisition declined, an agency assumption corrected, servicing retained after new-business activity ended, a narrower partnership proposal and an embedded offer postponed. The organisations and results are invented. Their purpose is to show how an insurance leader could explain a consequential choice through the relationship, the responsibility and the commercial possibility given up, instead of relying on the size of a premium projection alone.

The end of new sales did not close the responsibility account

In 2021 we stopped seeking new business in two niche products that had produced S$46 million gross written premium in 2020. The choice retained S$7.2 million in planned servicing expense over two years. That was an operating plan, not a claims reserve, policy cancellation or transfer of obligations.

I corrected a distribution measure I had made too persuasive

A 2009 account counted 900 listed agencies as productive outlets. Only 480 had produced business during the preceding twelve months; 420 had not. S$650000 supported reassessment, and I withdrew the productivity assumption without claiming that inactive relationships had no possible future value.

The premium opportunity depended on a relationship still unresolved

The 2016 acquisition review involved S$320 million trailing gross written premium, 35% from a partner contract expiring within eighteen months. We declined after S$2.6 million in diligence. I retained the renewal possibility and the opportunity forgone, without calling the decision a quantified loss avoided.

Current focus

I am examining how strategy makes the period after a commercial arrangement visible. The useful questions concern responsibility, evidence of continuing access and the difference between a projection and a negotiated commitment. I want the institution to understand what remains unresolved even when the growth headline is compelling, and to hear the responsible specialists before it treats an attractive distribution relationship as a complete insurance proposition.

Conversations I welcome

I would welcome a discussion about the strategic dependence inside an insurance partnership or a business proposition whose continuing responsibilities need clearer explanation. A first-board conversation would require employer permission, preparation, conflicts and time to be examined. This demonstration describes no actual insurance or advisory service. A real introduction should use an approved contact route and avoid sending policyholder details or confidential transaction material as a public first step.

Highlights

I learned to read the responsibility account alongside the growth proposal.

48

Strategy colleagues

Five direct reports at October 2026; specialist insurance authorities remain separate

S$8.8 m

Delegated strategy expense

2026 function remit, not premium volume, claims reserves or investment authority

34

Years examining commercial propositions

Career began August 1992; executive board presentations since September 2019

A letter from the chief strategy officer

Dear reader,

Portrait of Intan Santoso

I ask what the insurer remains responsible for after the campaign, partnership or new-business programme has finished. Distribution can change faster than the obligations created through it. A strategy should make that difference understandable before it celebrates the reach of an arrangement or the premium it might produce. I work with the relevant owners to connect the commercial opportunity with the continuing commitment, without treating strategy as a substitute for underwriting or professional assessment.

I came to insurance strategy through an interest in the relationship between a commercial arrangement and what it leaves behind. A partnership can be described through its launch, duration and sales potential. The insurer also needs an account of the responsibilities that remain when the arrangement changes. I learned that the second account can receive less attention precisely because it does not fit as neatly into the growth presentation. My work has increasingly been to keep both accounts in the same decision.

Intan Santoso

Chief Strategy Officer
Strategic priorities

Where I focus my leadership.

Performance

What the priorities delivered.

Priority outcome 01

A smaller partnership proposition retained a different relationship

In 2023 a distribution partner proposed a three-year exclusive arrangement with modelled annual gross written premium of S$180 million. An alternative two-year nonexclusive proposition carried S$110 million in modelled annual premium. Neither figure was business already written. The larger proposal made a persuasive growth account, but I wanted the decision to explain how dependence on the partner and responsibilities after the arrangement ended would be addressed. Duration and exclusivity were strategic choices, not merely terms attached to a sales projection. Adrian Vellison, our fictional partnership director, favoured the larger arrangement. Exclusivity could justify more partner attention and a stronger launch effort. Reducing the commitment might weaken precisely the commercial support that made the opportunity attractive. I agreed that the alternative could not simply borrow the larger proposal's advantages. My concern was that the strategic account treated premium potential as though it settled the quality and durability of the relationship, without adequately describing what the insurer would continue to own after the commercial period. We selected the two-year nonexclusive proposition for further negotiation and committed S$4.8 million to strategic, legal and operating preparation. This was not an executed agreement or an issued-business result. Underwriting, actuarial, compliance, claims and capital owners retained their assessments. My team coordinated the comparison and made the continuing responsibility a visible part of the negotiation mandate. The shorter period did not itself eliminate dependence or settle every question about the arrangement. The choice gave up the larger modelled premium opportunity and some of the partner commitment associated with exclusivity. It also required us to explain why the smaller proposition deserved further work on its own terms. I did not present the S$70 million difference as a cost saving or a measured revenue loss. It was a difference between projections for different proposed relationships, with the actual commercial outcome still unresolved. The useful consequence was a more exact negotiating brief. The institution could see the growth possibility it was pursuing and the obligations that still needed owners, instead of asking one premium number to stand for the whole strategy. In a real account I would verify the proposal status and permissions before publishing any terms. This invented case illustrates strategic comparison, not legal advice or a claim that a particular contract structure is universally preferable.

Priority outcome 02

An acquisition volume depended on a contract nearing its end

The 2016 acquisition candidate reported S$320 million in trailing gross written premium. Thirty-five percent came through one distribution partner whose contract was due to expire within eighteen months. The business had an attractive customer proposition, and the acquisition sponsors expected the relationship to continue. I wanted the investment account to distinguish the existing premium volume from the commercial access on which part of its continuation depended. The historical figure was real within the fictional record; renewal remained an assumption. The transaction sponsors argued that a new owner could strengthen the relationship and that declining before renewal gave up an opportunity to shape it. Waiting for every dependency to be settled could mean the business was no longer available on comparable terms. That was a legitimate strategic objection. I did not argue that the partner would certainly leave or that the business had no value without it. I argued that the proposed case had not established enough about the continuing relationship to support the commitment being sought. After S$2.6 million in diligence, we declined the proposal. The expense described investigation and professional work, not a purchase price or a quantified loss avoided. Qualified financial, actuarial, underwriting, legal and risk colleagues retained their assessments. My contribution was to prevent the trailing premium figure from becoming an unqualified account of durable access, and to make the dependence explicit in the strategic recommendation. Declining had a cost beyond the diligence expense. We gave up the chance to acquire a proposition the sponsors believed could be developed, and the partner might have renewed under another owner. The decision did not prove the sponsors wrong about that possibility. It reflected what the institution was prepared to commit on the evidence then available. A later favourable outcome elsewhere would not retrospectively turn an unestablished assumption into established evidence at our decision date. I retain this case because an insurance acquisition can look familiar when described by product labels and premium volume while containing a less familiar distribution dependency. The question is not whether every uncertainty can be removed. It is whether the decision account states which relationship must continue for its argument to hold, who can assess that expectation and what the buyer is choosing to accept. The example makes no claim about an actual insurer, counterparty or completed transaction.

Priority outcome 03

Ending new-business pursuit retained a funded servicing plan

In 2021 we decided to stop seeking new business in two niche products that had generated S$46 million gross written premium in 2020. The strategic proposal initially concentrated on the activity the company would no longer pursue. I asked for a second account: the service responsibilities associated with business already written. A change in sales direction did not make those responsibilities disappear from our planning. I wanted the decision to show what continued, who owned it and what resources the operating plan retained. The commercial sponsors wanted a clear announcement that the group was moving effort towards other propositions. They worried that a substantial continuing expense plan would make the exit look indecisive. Their concern was understandable: a strategy must actually change resource use, not keep every old activity indefinitely. My objection was to treating the end of new-business pursuit as though it described the entire consequence. The insurer needed a deliberate account of the continuing work, even when the growth narrative had moved elsewhere. We retained S$7.2 million in planned servicing expense over two years. That figure was an operating plan. It was not a claims reserve, an assessment of ultimate liabilities, a cancellation of cover or a transfer of obligations. Claims, actuarial, finance, compliance and operating colleagues remained responsible for their professional work and the applicable commitments. My team made the distinction clear in the strategic record so that the end of sales activity did not become a misleading shorthand for the end of the business's responsibilities. The selected direction gave up a cleaner short-term expense story. It also required management to explain the work that continued after the product no longer featured in the growth programme. I did not claim that the two-year plan fixed the duration or total cost of every remaining obligation. Planning assumptions would need revision as the responsible owners assessed the actual work. A finite budget period is not evidence that all responsibilities end on its final date. The consequence was a more credible account of withdrawal from new-business pursuit. The institution could discuss the future proposition while retaining the people and processes needed for existing business. I would use authorised, verified information in a real public case and avoid policyholder details. This fictional example is about strategic honesty when a programme changes direction; it does not prescribe treatment of any policy or substitute for specialist insurance judgement.

Priority outcome 04

I had counted listed agencies as productive outlets

In 2009 I helped prepare a distribution account that described 900 listed agencies as productive outlets. The list was accurate as a list, but the productivity claim was not supported by the same evidence. Ratri Wicaksari reviewed the activity definition and found that 480 had produced business during the preceding twelve months, while 420 had not. I had allowed the larger number to make the distribution footprint sound more commercially active than the observation period established. Some colleagues argued that the inactive relationships were still valuable and could resume production. They did not want an activity measure to erase the investment already made in the network. I agreed with that concern. The correction was not to declare 420 agencies worthless or to assume that the previous year predicted every future year. It was to stop using the full list as though it established current productive reach. I needed to separate relationship presence, observed activity and future potential in the account I had helped promote. I withdrew the 900-outlet productivity assumption and supported S$650000 in reassessment. The revised material retained all 900 listed relationships but identified the 480 active during the defined twelve-month period. Distribution and operating leaders kept responsibility for the relationships and their development. My remit was the strategic interpretation. I did not claim that correcting a presentation by itself increased premium, improved underwriting results or reactivated any agency. The change made our growth story less immediately impressive. It also required colleagues to revisit an account they had already used, and it exposed my own part in making the original description persuasive. I could have treated the problem as a technical definition that someone else should have caught. Instead, I accepted that a strategist has responsibility for the inference carried by a number, especially when the number makes a preferred proposal easier to support. The later acquisition and partnership work drew on this lesson. A relationship's existence, activity and continuation are separate propositions, even when a summary combines them. I now ask what period and definition support the measure before letting it represent durable commercial access. All figures and colleagues here are invented. A real account would need authorised network data and care not to identify individual intermediaries through a public discussion of their activity.

Priority outcome 05

A fast purchase journey did not finish the proposition design

In 2025 an embedded-insurance proposal gave considerable attention to a short purchase journey. The commercial case described how conveniently a customer could add the offer within a partner's transaction. In the after-sale review, four of six defined service scenarios had an agreed owner and two did not. I asked the sponsors to resolve the missing responsibilities before the customer launch. A simple point of purchase did not establish a complete account of what would happen when the customer needed help later. The launch sponsors argued that the remaining scenarios could be resolved alongside the initial rollout. They were concerned about losing the partner's campaign window and the effort already invested in the integration. I did not dismiss that cost. A delay could make a commercially sensible proposition harder to recover. My concern was that the strategic presentation allowed the smooth purchase experience to stand for readiness across a relationship whose later stages had not yet been fully assigned. We postponed the customer launch pending an ownership agreement. S$1.9 million had been committed to preparation. That amount was not reported as a loss avoided, and the postponement did not establish that every aspect of the proposal was unsound. Product, claims, service, technology and compliance leaders retained their assessments. My contribution was to keep the unresolved after-sale responsibility visible in the decision about whether the overall proposition was ready to be introduced. The choice gave up the planned campaign window and left the commercial opportunity uncertain. We could not assume the partner would offer an equivalent later moment or that all preparation would transfer unchanged. I wanted those consequences stated alongside the reason for the delay. A more careful decision account should not make a postponement look costless merely because its rationale concerns the customer. It should explain both the unfinished responsibility and the opportunity that waiting may reduce. I draw no conclusion here about the validity of a policy, the treatment of a claim or a regulatory requirement. The six scenarios were an invented planning exercise, not a universal insurance checklist. The case illustrates how strategy can connect acquisition of the customer with the relationship that follows, while leaving professional and operating judgements with their proper owners. A real public explanation would need verified status and permission to describe the partnership.

Year in review

A career, chapter by chapter.

  1. 2019 — present

    Chief Strategy Officer

    Suraveth Assurance

    Connect partnership and growth choices with the continuing responsibilities they create for the insurer.

  2. 2012 — 2019

    Director of corporate strategy

    Suraveth Assurance

    Examine the durability of commercial access inside portfolio and acquisition propositions.

  3. 2006 — 2012

    Head of distribution strategy

    Suraveth Assurance

    Clarify the evidence behind distribution measures and correct an owned agency-productivity assumption.

  4. 1999 — 2006

    Engagement Manager

    Meraluni Strategy Partners

    Lead strategic assessments while distinguishing advisory scope from clients’ insurance decisions.

  5. 1992 — 1999

    Strategy Analyst

    Meraluni Strategy Partners

    Learn to separate relationship presence, observed activity and continuing commercial rights.

Stakeholder voices

What those I have served alongside say.

Intan changed the agency account when the activity evidence contradicted the impression created by the list. She retained the possible value of dormant relationships without continuing to call them productive outlets.
Ratri WicaksariFictional distribution-analysis lead; colleague on the 2009 agency reassessment
I favoured the larger exclusive proposal. Intan made the commercial upside and the responsibilities after the partnership period part of the same negotiation discussion.
Adrian VellisonFictional partnership director; counterpart on the 2023 distribution proposal

Outlook

Perspectives on what comes next.

An invitation

Contact

I would welcome a discussion about the strategic dependence inside an insurance partnership or a business proposition whose continuing responsibilities need clearer explanation. A first-board conversation would require employer permission, preparation, conflicts and time to be examined. This demonstration describes no actual insurance or advisory service. A real introduction should use an approved contact route and avoid sending policyholder details or confidential transaction material as a public first step.

Open to
  • Board appointments
  • Speaking invitations

office@intansantoso.example