The person behind the perspective · 2026
The operating facts that changed my financial judgement
I grew up in Jamshedpur in a Parsi family and now live in Panaji. My early interest in commerce came from seeing how the same purchase looked different to the person using an item and the person paying for it. That observation was a starting point, not a professional qualification. I completed a full-time Bachelor of Commerce at the fictional Khevazri Commerce College in May 1994 and joined Vemzatri Equipment Services that July. I do not claim an additional chartered-accountancy credential. My career developed through operating finance roles in which qualified specialists retained the responsibilities appropriate to their work.
Vemzatri employed thirty-four people and recorded ₹7 crore FY1995 revenue. As an accounts assistant, I checked supporting records and prepared entries for a manager's approval. I worked alone under the accounts manager's approval, without authority over spending. The practical lesson was that a complete document could still leave a question about the underlying transaction. An equipment movement, supplier invoice and customer assignment needed to be understood together. I learned that discipline slowly, through routine work rather than an invented early mandate to transform the enterprise. It remains relevant when a well-presented management account seems more settled than the operating facts beneath it.
In June 2000 I became a fleet-cost analyst. The business had sixty-one employees and ₹16 crore FY2001 revenue. I led three colleagues within ₹42 lakh annual function expense, reporting to the finance manager. The role brought me closer to hire, maintenance and transport decisions. I began to see how an average cost could conceal the specific expense of supplying a particular brief. Existing equipment was not interchangeable simply because it belonged to the same broad category. A contract that required external hire needed its own account, including crew and movement costs that a summary might distribute too generously across the whole business.
I moved to Tevqalri in September 2006 as finance operations manager. The company then employed seventy-six people and earned ₹29 crore FY2007 revenue. Seven colleagues and ₹93 lakh annual function expense sat within my remit under the controller. I worked across the handover between operating records and financial review. Farida's colleagues could explain why a unit remained in use or why a substitute would not meet a specification. My task was to make that evidence available in the relevant decision, without turning finance into an engineering approval function. The relationship strengthened my account but did not remove the need for separate professional judgements.
From January 2013 I was financial controller. Tevqalri had 104 employees and ₹49 crore revenue by FY2017. My later remit covered eleven colleagues and ₹1.8 crore FY2019 function expense under the then CFO. In 2019 I approved a planning account that combined continuing-activity cash with the sale of a vacant administrative office. The total receipts were real, but I let a one-off event support an argument about next year's repeatable spending capacity. The resulting capital programme needed revision and the company incurred a ₹16 lakh review. That was my error in management interpretation; I do not rewrite it as a statutory reporting restatement that the fictional record does not establish.
I took the CFO role in September 2021. Sixteen finance colleagues now report through three leads, and my accountability is to Anil as CEO. The family, employee and fund ownership interests create different perspectives on spending and returns, but I hold no personal equity and no statutory directorship. I present financial matters to the board when required. That exposure should be described accurately rather than converted into a claim that I have served as a director, chaired an audit committee or independently assured the accounts I help prepare.
Recent choices have sharpened the distinction between a label and its consequence. A prominent assignment could not be called profitable when identifiable direct costs exceeded its fee. Fully depreciated equipment still needed support or replacement. A damage claim did not become available cash merely because we had submitted it. A depot proposal retained obligations that the closure headline omitted. These decisions gave management a clearer basis for choosing, not proof that every subsequent result improved. I remain interested in outside-board work, but I have not yet registered in the IICA databank in this fictional preparation record. My current role, unfinished preparation and provisional time capacity would all need examination before an appointment discussion could become substantive.
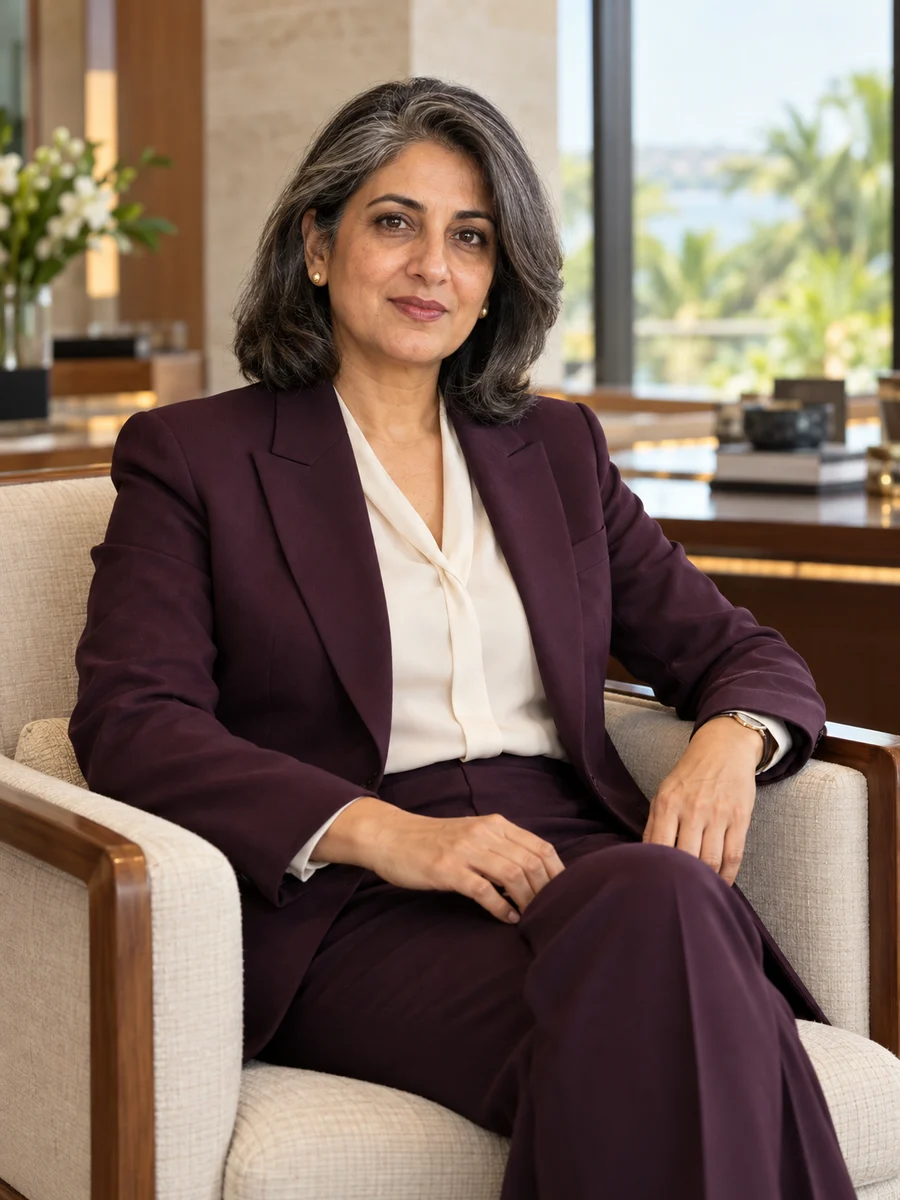
In my own words
A number can be accurate and still answer the wrong planning question. I ask what produced it, what obligations sit beside it and whether the same conditions will exist when we make the next commitment. Finance should preserve those differences in a form the people running the business can use. That includes a fair account of my own approval mistakes.
Roxana Verqazli
Education
Formation
- Bachelor of CommerceKhevazri Commerce College1994
Working languagesEnglish · Hindi · Gujarati