Chief Executive Officer India
The account history behind my decisions
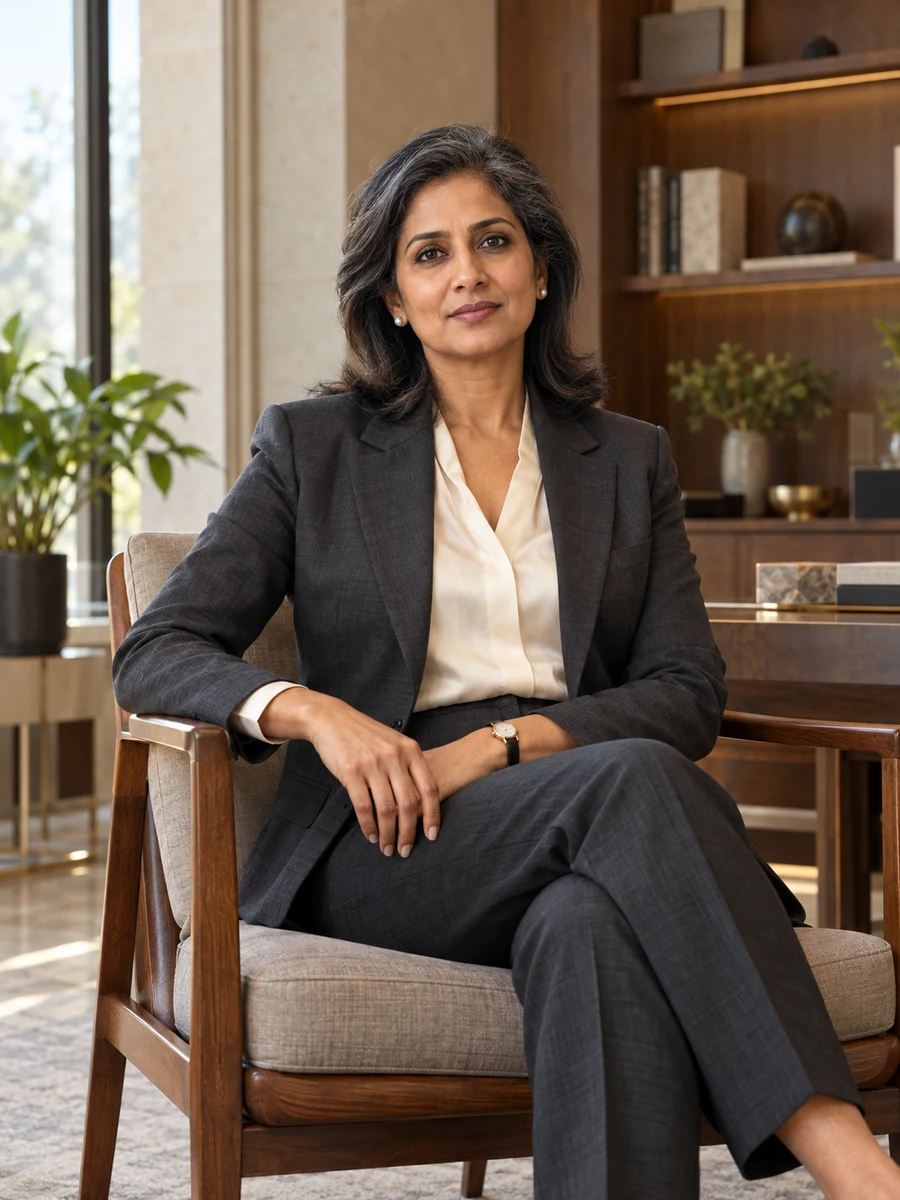
I grew up in Navsari and moved to Vadodara for my first full-time job after completing a commerce degree in May 1996. My first desk at Nerqulta Invoice Operations had a calculator, a pile of remittance copies and an unusually patient supervisor. I was responsible for proposing where receipts belonged, not for approving adjustments. That distinction was explained to me after I treated an amount that happened to match as sufficient evidence. The error was corrected before posting, but the lesson remained: arithmetic agreement is a starting point for an explanation.
By 2002 I was managing a team that investigated accounts across several business sellers. Some apparent late payments were amounts already received with incomplete references. Other balances represented deductions that the sales department had verbally accepted but never documented. I resisted describing all of them as collection failures. The argument was not popular because it complicated a simple performance report. It also exposed weaknesses in our own handovers. I began taking a small sample of accounts into weekly meetings and asking colleagues to explain what happened in ordinary language before showing the ageing table.
Those meetings taught me to distinguish disagreement about a debt from disagreement about its paperwork. In one account, a customer accepted the delivery but disputed the freight charge. In another, the quantity itself was contested. Combining both under a generic dispute label produced the wrong escalation. I developed short investigation records that showed the disputed element, the amount still accepted and the person authorised to decide. The form mattered less than the conversation it required between sales, dispatch and finance. I also learnt that a service provider can make a problem worse by sounding more certain than its client.
I joined Vazrenki Receivables Services in April 2008 to build a practice around these account explanations. The company was then a small founder-owned operation. I brought experience in investigation, but I had to learn commercial pricing and staff planning. A client willing to pay per invoice was not necessarily willing to pay for several hours spent finding the history of an old deduction. We initially absorbed too much of that work. I changed the proposals to separate routine matching from unresolved commercial cases, with an agreed allowance and an escalation route when the evidence was absent.
My promotion to chief operating officer in April 2014 enlarged the problem. I became responsible for utilisation, service quality and the annual operating budget across several teams. I could no longer rely on personally knowing each difficult account. I introduced a weekly review of cases closed without sufficient explanation, alongside the familiar open-case report. That measure revealed apparently efficient work being returned by clients. We adjusted training and supervisor capacity rather than simply asking analysts to close fewer cases. I also learnt to discuss the cost of a service honestly with commercial colleagues before blaming delivery for an unattractive margin.
I became chief executive in April 2020. The immediate concern was continuity: colleagues needed secure access to records, clients needed reliable contacts and the company needed a realistic view of incoming fees. Later, we moved to employee-and-founder ownership through a minority employee share arrangement. I am an executive shareholder but not a statutory director. Our board appoints and supervises me through the chair. That arrangement has made me careful about separating my executive reporting from the judgement directors must exercise for themselves. Presenting a case is not the same as having governed its approval.
Today I spend substantial time on the commercial boundary of our work. I will approve investigation capacity where the client can identify a decision owner. I am less willing to accept a large queue whose only instruction is to recover everything. Our FY2025–26 revenue was ₹34 crore, with 186 employees, and I report both the quality of the work and the economics of producing it. My colleagues know me for asking what was surrendered to obtain an improvement. A faster response can cost specialist attention elsewhere; a clearer contract can lose a prospect. My next chapter should use that experience in a business prepared to examine those costs openly, with financial discipline and respect for the people whose records we handle.
Open to Board appointments · Executive opportunities
Languages / English · Gujarati · Hindi
A leadership conviction
I do not regard a customer's overdue balance as a complete account of their behaviour. A payment can be missing, misapplied or withheld for a reason our own client has not resolved. My responsibility is to make those distinctions commercially useful without allowing investigation to become an excuse for inaction.
- FY2025–26 service revenue
- ₹34 crore
- Enterprise revenue, not client receivables
- Employees
- 186
- Vazrenki Receivables Services
- Operating career
- 30 years
- June 1996 onwards
Education & credentials
- Bachelor of Commerce
- Sairun Commerce College · 1996
Perspectives from colleagues
Meher brought the client departure into the same paper as the contribution improvement. That made the repricing decision possible to assess without a second explanation from finance.
When I asked for more callers, she asked which question those callers would be able to answer. We built a smaller investigation service and finally knew where the client's authority was missing.