Celeste CampbellChief Marketing Officer

Executive summary / Personal profile

A policy's promise is kept at the clinic counter
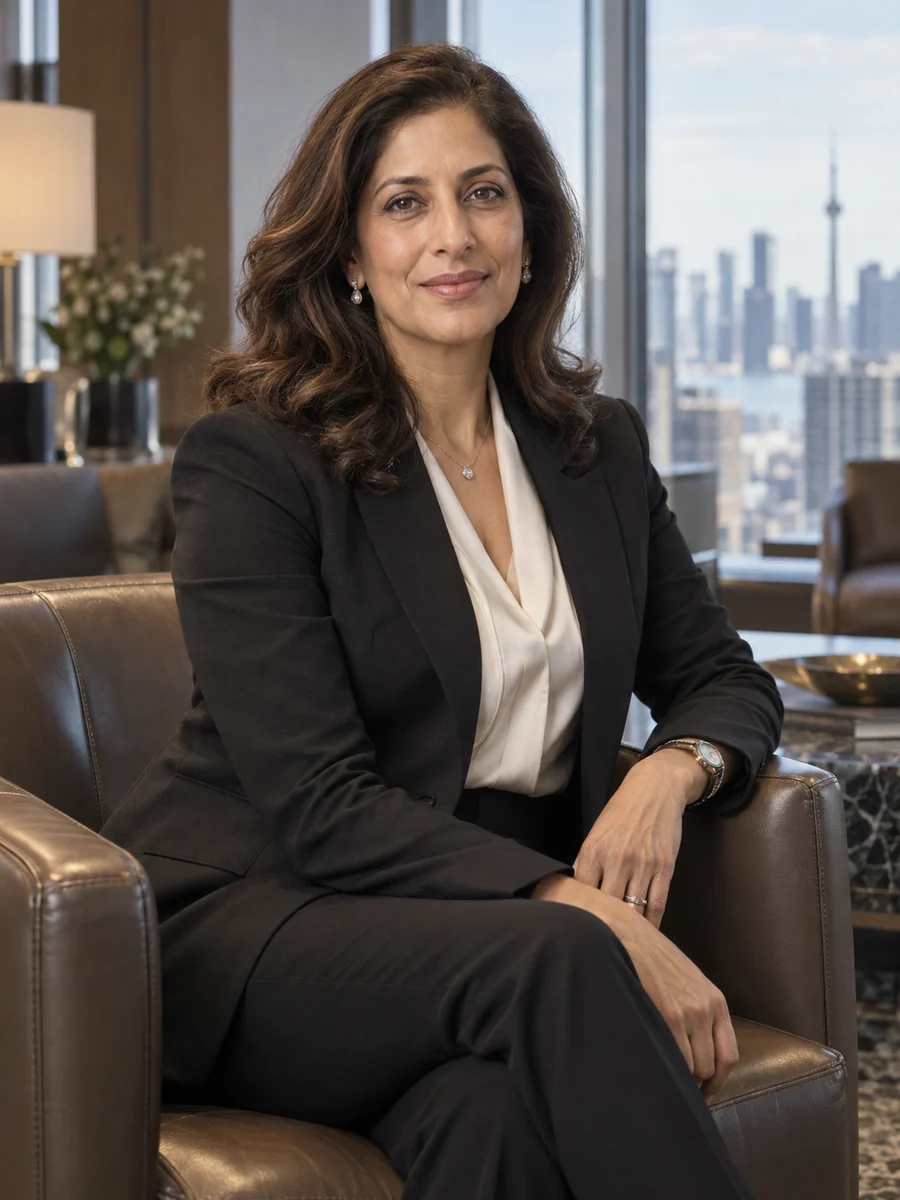
Portrait of Celeste Campbell

Chief Marketing Officer Canada

Pet owners should learn what their cover excludes while they are still choosing it, not from a claim decision.

Open to Board appointments

Start a conversation

01 / Leadership approach

A pet owner rarely reads a policy until an animal is ill and a veterinary bill is waiting at the counter. I would rather lose a sale than let that moment be the first time someone learns what we exclude. Marketing makes promises on the company's behalf, so I work most closely with the people who must keep them: claims, underwriting and the brokers and clinic staff who answer the follow-up questions.

02 / Areas of responsibility

  • Renewal increases explained pet by pet
  • Exclusions understood before the first claim
  • Channel economics across direct, broker, clinic and employer sales
  • French-language marketing created in Quebec
Gross written premium
C$96M
Year ended December 2025
Insured dogs and cats
118,000
At December 2025; pets, not households
Annual marketing budget
C$11.4M
2025; excludes broker commission

Evidence from practice

Explaining a 17 per cent renewal increase without changing anyone's cover by default
Claims cost per insured pet rose 19 per cent during 2023, driven by higher veterinary fees, more specialist referrals and an ageing population of insured dogs.
Reviewing veterinary records before the first claim instead of after it
In 2022, 15 per cent of first-year claim decisions at Tamberlow were declines for pre-existing conditions.
Ending an online-only discount that undercut our brokers
From 2021 Tamberlow offered a 10 per cent discount to customers who bought directly on our website.
The complete case record ↗

I judge an insurance brand by what customers understood before their animal fell ill, not only by how many of them bought the policy.

I am chief marketing officer of Tamberlow Pet Insurance Company, a Saskatoon-based insurer of dogs and cats. We had 118,000 insured pets at the end of 2025 and wrote C$96 million of gross premium that year. Sallowbrook Mutual Insurance, a policyholder-owned property and casualty insurer in Regina, holds 70 per cent of our shares; founders and employees hold the rest. I lead 38 colleagues and a C$11.4 million annual budget across brand, acquisition, partner marketing with brokers, clinics and employers, customer research and the French-language work produced by our team in Sherbrooke.

I came to insurance from the other side of the veterinary counter. For six years I managed pet-food brands sold through clinics, and I saw how much an owner trusts the receptionist and the technician as well as the veterinarian. At Sallowbrook I then spent a decade marketing home, farm and auto cover through brokers, including renewals after hail-heavy summers, when every increase arrived alongside a neighbour's claim story. Both experiences taught me that customers form their lasting view of a company at the moment of need, long after the advertisement that first reached them.

Three recent decisions show how I work. We told renewing customers why prices were rising after the 2023 claims year and refused to move them quietly onto a higher deductible. We began reviewing new customers' veterinary histories before their first claim, accepting the cost and the early cancellations that followed. We also removed an online-only discount that had been undercutting the brokers who sell our cover. Each choice cost growth somewhere, and I report those costs to our board beside the results.

Renewal letters that gave the reason

After claims cost per insured pet rose 19 per cent in 2023, renewal premiums rose 17 per cent on average. Each letter showed the pet's own increase and three lower-cost options. Retention fell to 82 per cent against an 85 per cent forecast, and complaints settled at 2.1 per thousand renewals.

Exclusions known before the first claim

A review of veterinary records within 30 days of purchase costs about C$1.2 million a year. Pre-existing-condition declines fell from 15 to 6 per cent of first-year claim decisions, while cancellations in the first 60 days rose from 6 to 9 per cent.

One price in every channel

Ending a 10 per cent online-only discount raised our direct acquisition cost from C$148 to C$171 a policy. New policies written through about 140 brokerages rose from 6,100 to 8,000 in 2025.

Current focus

I am preparing the 2026 renewal communications with our pricing and claims teams, and checking whether customers who chose a higher deductible in 2024 understood what that choice meant when they eventually claimed.

Conversations I welcome

I would consider a first independent board seat at a member-owned financial institution or a consumer-facing insurer in Western Canada, with about twenty-two days a year available, subject to the consent of Tamberlow's chief executive and board and a review of our partner relationships.

The leadership record

Trusted with consequential decisions.

Formation

  • Bachelor of commerce, marketing majorRennickvale University · 1998
Celeste brought the renewal letter to the board before the rates were final. She wanted directors to approve the explanation as well as the price, and she reported the lost renewals afterwards without softening them.
Priya HaldermannChief executive officer, Tamberlow Pet Insurance Company
The full record ↗

Contact

I would consider a first independent board seat at a member-owned financial institution or a consumer-facing insurer in Western Canada, with about twenty-two days a year available, subject to the consent of Tamberlow's chief executive and board and a review of our partner relationships.

  • Board appointments