Skip to website
Faiz QevtalriChief Financial Officer
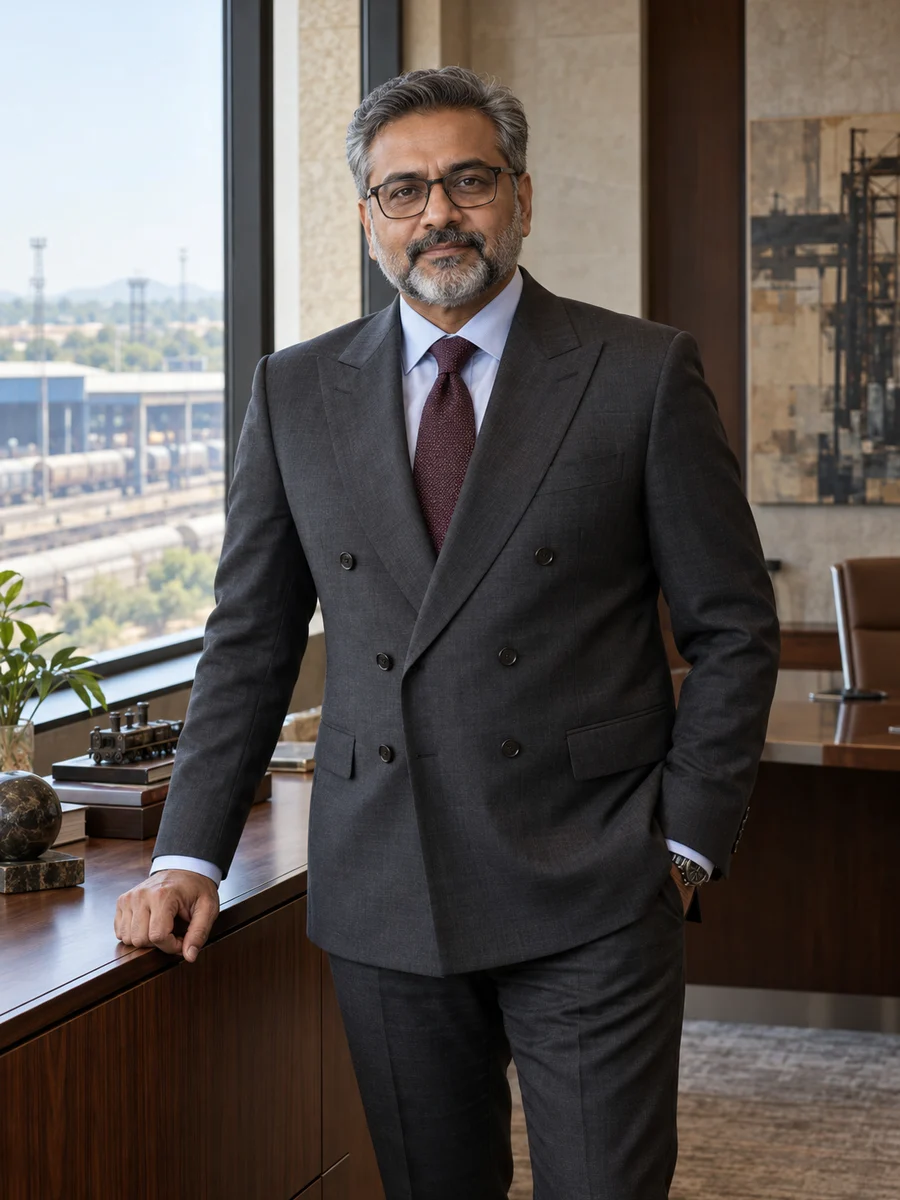
Portrait of Faiz Qevtalri

Chief Financial Officer · India

FaizQevtalri

Show what belongs inside the financial commitment

I grew up in Lucknow and completed a Bachelor of Commerce at the fictional Velqazmi College of Commerce in May 1994.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations
  • Executive opportunities

Show what belongs inside the financial commitment

The proposal I supported in 2017 showed a 23% margin on ₹10 crore of possible work. Only ₹8.2 crore had an authorised commercial basis. The remaining ₹1.8 crore was proposed variation work, with ₹50 lakh of estimated associated cost. Removing both from the comparison left ₹1 crore contribution against ₹8.2 crore base revenue, about 12.2%. The mathematics of the first proposal was correct; the implied certainty of its scope was not. I had allowed a discussion to look like an agreed commitment.

I am Faiz Qevtalri, fictional CFO of Temqozri Wagon Services in Bilaspur. Our regional refurbishment and mobile repair business employs 291 people and records ₹182 crore FY2026 revenue. I lead twenty-four finance colleagues, including Meera, our controller, and report to Arun, our CEO. I grew up in Lucknow and entered commercial accounting in 1994 before moving closer to workshop decisions. My experience concerns the financial account of service work; it does not confer authority to certify rail equipment or operate a railway.

The questions I bring to management are concrete. Does the margin depend on scope still being negotiated? Does the value recorded for equipment in our custody establish ownership? What cash is committed to contract security before working resources are funded? Is a repeat job new business or work needed to put an earlier service right? These distinctions affect the choices an enterprise can responsibly make, even when the headline figures appear orderly.

The base scope remained visible beneath the proposed variation

The authorised ₹8.2 crore scope carried ₹7.2 crore estimated cost. The additional ₹1.8 crore proposal and ₹50 lakh cost stayed separate until their commercial basis could be established.
Custody values were separated from company ownership

A ₹22.4 crore internal replacement-value list included ₹9.6 crore of customer-owned components and ₹12.8 crore of company-owned items. Neither total was presented as an audited carrying value.

The security cash remained inside the service decision

A ₹3.6 crore bank cash-margin commitment was considered alongside working resources. The chosen ₹2.5 crore service programme implied ₹6.1 crore combined cash commitment, subject to the actual funding and instrument terms.

Current focus

I am improving how workshop and mobile-service managers read a combined financial account without losing their own responsibility. Internal work can be useful for assessing a unit, but it must not become a second external sale when management considers the whole enterprise. The latest reporting change retained those two views explicitly.

Conversations I welcome

I welcome finance-leadership and advisory conversations involving regional engineering services. I am also exploring a first statutory board contribution, with twenty-two days provisionally available. In this fictional career I passed the IICA databank proficiency assessment in February 2026 after registering in September 2025; company-specific fit and independence still require their own review.

A workshop can hold equipment it does not own and discuss work the customer has not authorised. My responsibility is to prevent either fact from becoming a convenient financial assumption. I once supported a margin proposal that depended on additional scope still under discussion. The lesson was to make the boundary of the calculation visible before management committed resources against it.

Faiz Qevtalri

Chief Financial Officer

Areas of stewardship

Where accountability has been mine.

  1. IAuthorised scope and contract margins
  2. IICustody values and ownership boundaries
  3. IIISecurity cash and working resources
  4. IVRemedial work and internal service reporting

Selected work

Decisions, and what they changed.

I

Removing an unagreed variation from the margin I had supported

In 2017 I supported a refurbishment proposal with ₹10 crore possible revenue and ₹7.7 crore estimated cost, implying a 23% contribution margin.

The full account

II

Reclassifying a custody list before it became an asset-capacity claim

In 2021 an internal workshop list carried ₹22.4 crore of replacement values for components and related items held across our facilities.

The full account

III

Choosing a service programme with its security cash included

A 2022 service opportunity required a bank performance-security facility with a ₹12 crore nominal amount and ₹3.6 crore cash margin under the proposed terms.

The full account

In the words of others

Trusted by those who appoint.

In this fictional account, Faiz returned to the margin proposal he had supported and separated the authorised work from the proposed variation. The revised discussion showed why the more attractive percentage depended on a commercial premise that management still needed to resolve before committing additional resources.
Arun QevsartiFictional CEO, Temqozri Wagon Services
The invented custody review preserved our responsibility for customer-owned components without presenting their replacement value as company purchasing power. Faiz helped us retain the useful operational record while changing the financial claim made from its total.
Meera QezvartiFictional financial controller, Temqozri Wagon Services

The journal

Perspective, set down with care.

An invitation

Contact

I welcome finance-leadership and advisory conversations involving regional engineering services. I am also exploring a first statutory board contribution, with twenty-two days provisionally available. In this fictional career I passed the IICA databank proficiency assessment in February 2026 after registering in September 2025; company-specific fit and independence still require their own review.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations
  • Executive opportunities

office@faizqevtalri.example