Skip to website
Mathew VezqavniChief Financial Officer
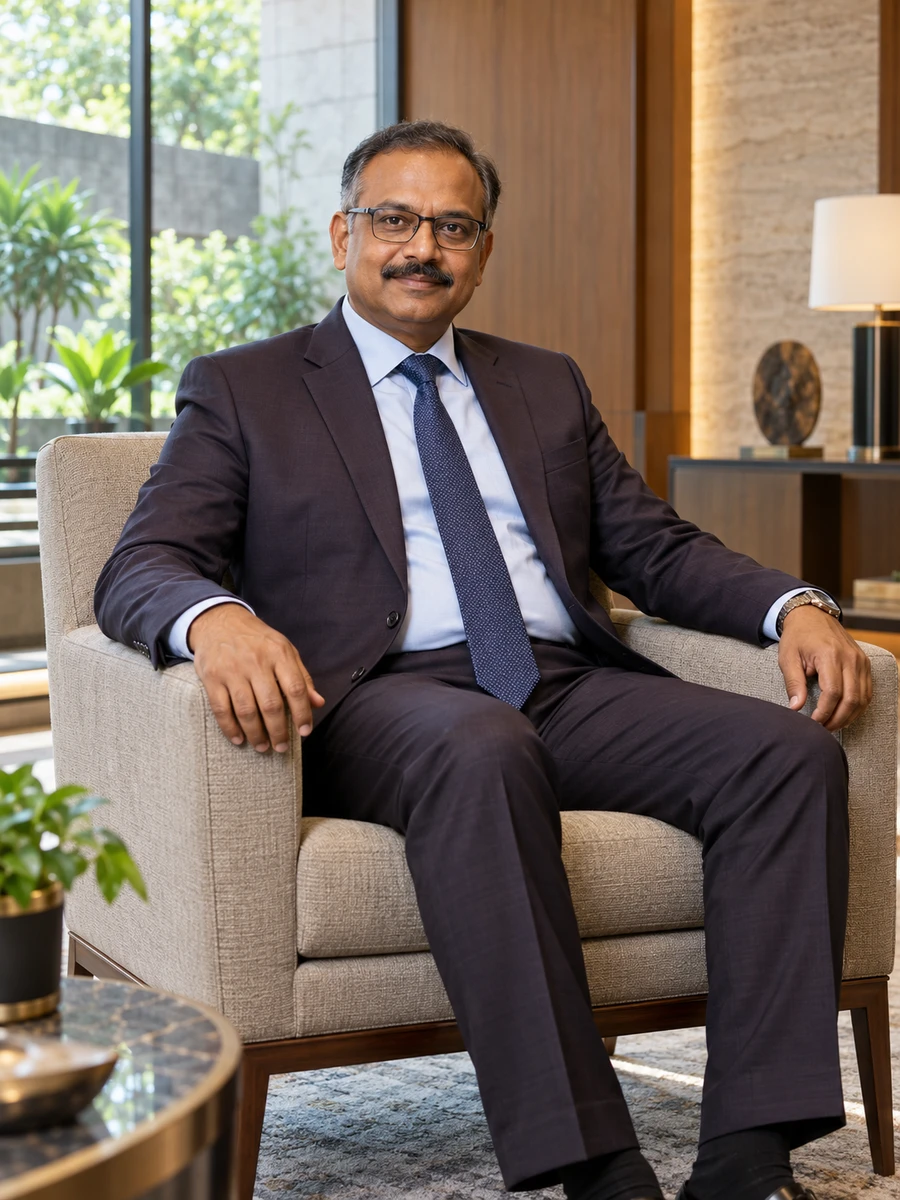
Portrait of Mathew Vezqavni

Chief Financial Officer · India

MathewVezqavni

A busy battery fleet still has to earn its days

I grew up in Mangaluru and studied commerce because I wanted to understand how an ordinary business knew whether its activity was paying for the obligations behind it.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

A busy battery fleet still has to earn its days

In 2020 I approved a management dashboard that treated ₹12.6 crore of quarterly collections as though it all represented earned rental activity. Asha Dezqarthi's reconciliation separated ₹9.4 crore of earned amounts from ₹3.2 crore of refundable customer deposits. The money had arrived, but the customer obligation had not disappeared. I had allowed a useful cash view to carry an income meaning it could not support.

I am Mathew Vezqavni, the fictional CFO of Nezqamvi Mobile Power in Ranchi. We rent mobile battery units and provide temporary-power project services. Eighteen finance colleagues work through three leads within my ₹2.4 crore annual function expense. The company's 230 employees and ₹72 crore FY 2026 revenue describe the enterprise, while its 30 MWh fleet figure describes rated storage energy. None of those measures should be mistaken for my personal spending authority or a promise of energy delivered to a customer.

My work concerns the financial meaning of a fleet that can look busy before its economics are clear. A unit can be allocated to a job while moving between sites, waiting without a billable entitlement or undergoing service. A resale assumption can make a current charge look comfortable without evidence that the expected proceeds will exist. A commercially attractive rental can carry movements and obligations the first margin account has omitted. The cases retain the choices and the costs of correcting those accounts.

Collections kept their customer obligation

The ₹3.2 crore refundable-deposit component stayed separate from ₹9.4 crore earned amounts. We corrected the management account before statutory closing and incurred ₹27 lakh of review expense, without claiming new cash recovered.

Allocated days were not all invoiceable days

The 31,500 scheduled unit-days separated into 24,400 billable days, 3,100 movement days, 2,500 unpaid-hold days and 1,500 service days. The classification changed the expansion discussion without pretending that a calendar count measured delivered energy.

The residual estimate affected a future charge

A ₹30 crore carrying amount with five years remaining produced a different prospective illustration when estimated residual proceeds moved from ₹12 crore to ₹4.8 crore. The assumption needed evidence before the lower charge could be defended.

Current focus

I am working on an operating and finance account that shows how a fleet earns, what remains payable or refundable, and which asset assumptions need review before another investment is approved.

Conversations I welcome

Selected discussions about rental economics, finance controls and a possible first outside board contribution, subject to preparation, employment and relationship review.

29 years

Finance career

June 1997 to October 2026; fictional continuous chronology

18 colleagues

Finance team

Three leads; ₹2.4 crore annual function expense

₹72 crore

Enterprise revenue

FY ending March 2026; not personal spending authority

30 MWh

Fleet storage energy

120 units at 250 kWh each; nameplate, not delivered output

I want finance to explain what the fleet has actually earned and what the business still owes. Scheduling, cash collection, income and asset value each describe part of that account. They become misleading when a convenient operating number is allowed to stand in for the rest.

Mathew Vezqavni

Chief Financial Officer

Areas of stewardship

Where accountability has been mine.

  1. ICash receipts with their obligations intact
  2. IIFleet days that have a commercial meaning
  3. IIIAsset estimates that can be explained
  4. IVRental contribution after the whole commitment

Selected work

Decisions, and what they changed.

I

I let a collections dashboard imply that customer deposits had been earned

In 2020, as finance director, I approved a management dashboard showing ₹12.6 crore of quarterly collections under a rental-performance heading.

The full account

II

A full allocation calendar contained seven thousand days that were not billable

The FY 2026 fleet review showed 31,500 scheduled unit-days.

The full account

III

A convenient residual estimate could not decide the remaining annual charge

A 2024 review examined a battery-asset cohort with a ₹30 crore carrying amount and five remaining years in the illustration used for planning.

The full account

In the words of others

Trusted by those who appoint.

In this fictional account, Mathew asked us to separate paid demand from the resource occupied in serving it. He did not describe the deferred acquisition as money saved, and he kept the commercial cost of waiting in the discussion.
Leena TevqarmiFictional CEO and current manager, Nezqamvi Mobile Power
This demonstration quote reflects my role as the fictional controller who challenged his dashboard. Mathew retained the collection result but corrected the income inference, acknowledged his approval and supported the work needed to explain the customer obligation.
Asha DezqarthiFictional financial controller and colleague, Nezqamvi Mobile Power

The journal

Perspective, set down with care.

An invitation

Contact

Selected discussions about rental economics, finance controls and a possible first outside board contribution, subject to preparation, employment and relationship review.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

office@mathewvezqavni.example