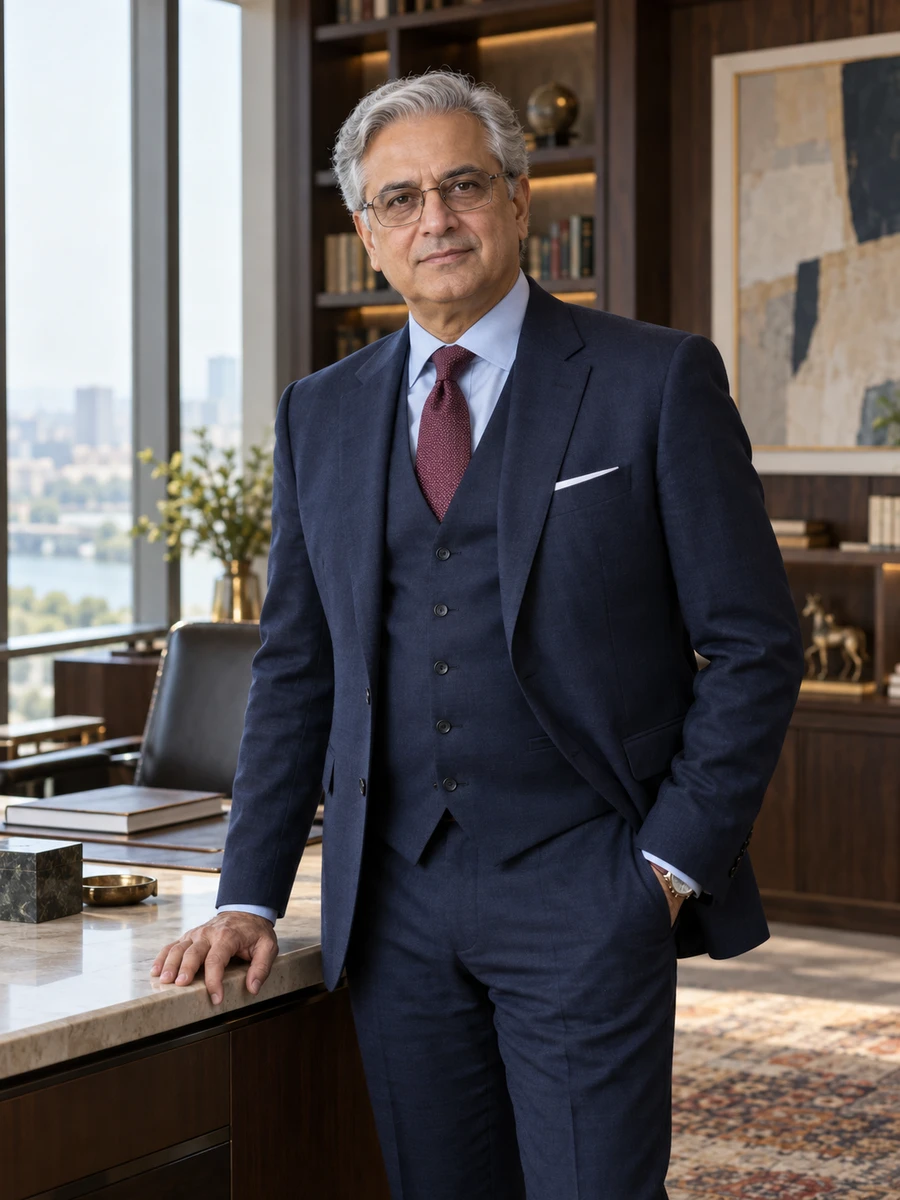
I am the chief strategy officer of Navqetri Writing Stores in Surat. We are a fictional retailer and institutional wholesaler of premium pens, refills and notebooks, with eighteen showrooms and 260 employees. I lead fourteen strategy colleagues through three leads within ₹4.2 crore annual function expense. The company's ₹118 crore revenue is context for that work, not a P&L delegated to me.
My thirty-seven years began in consumer research. Over time I became more interested in the distinction between a persuasive account of demand and a commitment a company can actually rely on. A customer may return without being obliged to buy. A franchise partner may fund a shop while we still carry stock and support. A product can leave the catalogue while its owner still needs a compatible refill.
In 2020 I put ₹42 crore of repeat-customer revenue into a contracted-recurring category for a proposed acquisition. Only ₹14 crore related to defined current agreements; ₹28 crore came from discretionary reorders. I owned the classification. We corrected the paper, deferred the ₹112 crore proposal and funded ₹54 lakh of commercial diligence. Neither category justified treating future revenue as unconditional. The account retains my error rather than presenting the correction as an insight I had from the start.
A minimum changes the royalty account
A proposed licence called for the greater of ₹24 lakh annually or 8% of defined sales. At ₹2 crore sales, ₹24 lakh is an effective 12%, not 8%. We declined the broad rollout commitment and funded a separate six-location research programme under distinct pilot terms.
Someone still had to finance the stock
Ten proposed franchise partners would fund ₹9 crore of fitout, but Navqetri would retain ₹3.2 crore inventory funding and forecast ₹76 lakh annual support. The board limited the first wave to three, subject to qualified terms; the ten-location proposal did not become ten opened stores.
The exit decision had a continuing customer
Retiring six slow-selling fountain-pen models left a reviewed cohort of 12,000 historical unit sales. A ₹1.2 crore parts and service-planning budget supported a commercial route through March 2032. The sales cohort is not a count of active users or an accounting provision.
Current focus
Commercial strategy that gives decision-makers a clear view of contractual dependence, retained investment, shared capacity and obligations after an exit. I want the proposed benefit to travel with the conditions needed to make it credible.
Conversations I welcome
A first outside non-executive contribution after relevant preparation and relationship review. I hold 0.6% within employee ownership, have no statutory seat and offer twenty-three provisional days. Fictional databank registration is complete; proficiency assessment remains unfinished.