The investment account contained two different kinds of movement. We had received ₹6 crore of coupons, and the unsold portfolio's valuation had risen by ₹4 crore. In 2021 I put the ₹10 crore total into a management paper as cash supporting an ₹8 crore discretionary office refit. The addition was correct; the description was not. No disposal had converted the valuation movement into a receipt. I had allowed an attractive investment result to answer a question about available funding that it could not answer on those facts.
I withdrew the recommendation and supported a ₹5.2 crore commitment considered against the identified ₹6 crore cash source. The bounded account left ₹0.8 crore in that source, not an estimate of the company's total liquidity or claims resources. A separate ₹21 lakh presentation-review expense remained visible. Permissions, accounting treatment and capital and risk assessment were separate questions, not settled by identifying cash. The mistake required a clearer account and my own acknowledgement, rather than a claim that the finance team had generated additional money by correcting the paper.
I grew up in Ludhiana and completed commerce at the fictional Qezvemi Commerce College in May 1992. That July I joined Nevqetri Process Equipment, an industrial exporter, as an accounts assistant. The firm had seventy-four employees and ₹12 crore revenue for FY ending March 1993. I was one of six accounts colleagues without direct reports or delegated spending. The work introduced me to the difference between an invoice, a receipt and the currency in which a commitment would eventually be settled.
In July 1998 I became treasury manager. Nevqetri employed 180 people and recorded ₹58 crore revenue for FY ending March 1999. Eight colleagues worked within ₹63 lakh annual function expense under the finance head. I learned to make currency and timing assumptions explicit before an operating sponsor treated a planning figure as a fixed price. Treasury responsibility also required coordination with people who understood the underlying commercial arrangement. A rate calculation could be precise without describing when payment was due or what the company was actually obliged to buy.
I joined Zhevqerni in September 2005 as financial controller. The fictional insurer employed 210 people and recorded ₹280 crore gross written premium for FY ending March 2006. Nineteen finance colleagues worked through three leads within ₹2.6 crore annual expense under the CFO. Moving into insurance required me to learn the difference between financial presentation and the professional judgements supporting underwriting, claims, actuarial work and investments. Written premium was a measure of business, not a convenient synonym for revenue or a balance available for unrelated spending.
From April 2013 I was finance director, a management designation without a statutory appointment. Zhevqerni had 350 employees and ₹730 crore gross written premium for FY ending March 2014. Twenty-eight colleagues worked through four leads within ₹4.8 crore annual function expense under the CFO. The role brought more responsibility for connecting operating proposals with their financial consequences. I became interested in what was lost when a detailed account became a short executive recommendation: the currency could disappear, a conditional amount could become certain, or a supplier price could omit the work the company retained.
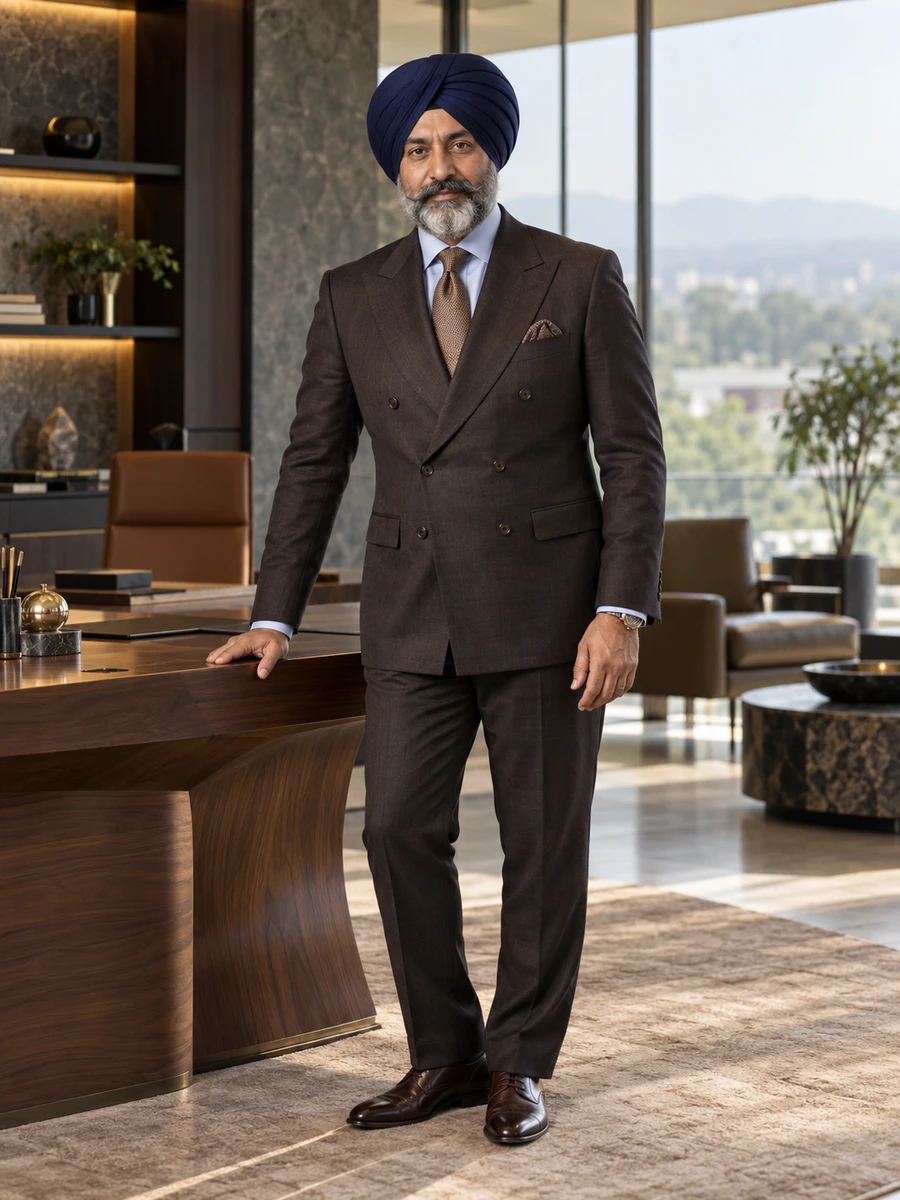
I became CFO in January 2020. Today thirty-eight colleagues work through five heads within ₹7.2 crore annual function expense, reporting to CEO Helen Vezqetri. Chief actuary Sanjay Tezqemri and other professional owners retain their mandates. The eighteen-branch insurer has 463 employees, ₹1,120 crore gross written premium for FY ending March 2026 and ₹2,260 crore assets at that March. A founder holding company owns 61%, a corporate investor 24% and employees 15%, including my 0.8%. I have no statutory seat.
Recent work has included a foreign-software commitment, a founder-affiliated records-service comparison, a cash-stress discussion and a proposed executive incentive scorecard. These cases do not turn financial clarity into a claim that finance owns every operating or professional decision. They show how a recommendation can change when its assumptions and retained obligations remain visible. Some outcomes are proposals still requiring review, and I keep that status rather than present a funded design exercise as an implemented policy.
I am based in Chandigarh and work in English, Hindi and Punjabi. Databank registration was completed in May 2026 and proficiency assessment in August in this fictional account. A first outside appointment would still require employer agreement, qualified eligibility and conflict review, and a realistic assessment of twenty-three provisional days. I would bring financial questions into collective judgement while learning the receiving enterprise and accepting that a clear calculation is only one part of a sound decision.