Skip to website
Mathew Vezqavni

A leadership monograph

Mathew Vezqavni

A busy battery fleet still has to earn its days

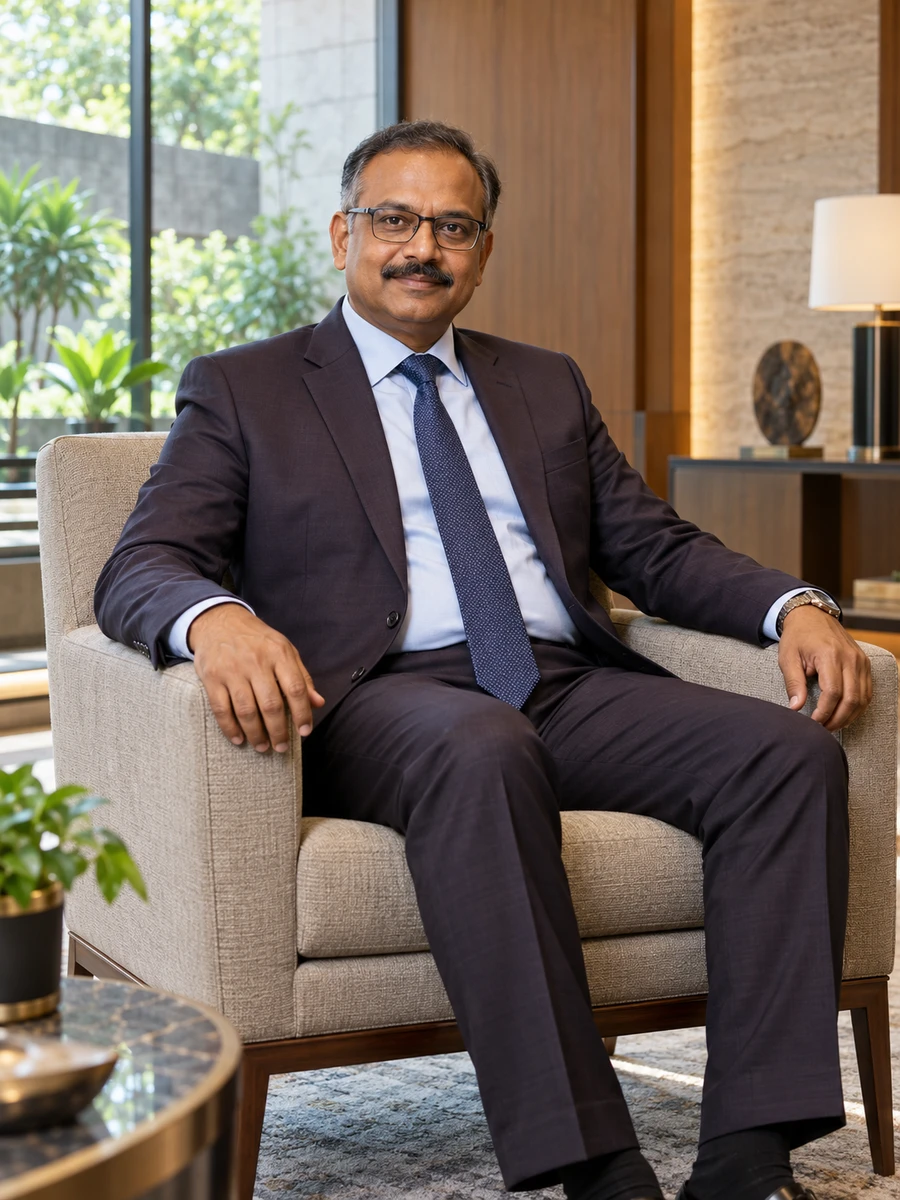
Portrait of Mathew Vezqavni

Chief Financial Officer · India · Volume I · 2026

A busy battery fleet still has to earn its days

In 2020 I approved a management dashboard that treated ₹12.6 crore of quarterly collections as though it all represented earned rental activity. Asha Dezqarthi's reconciliation separated ₹9.4 crore of earned amounts from ₹3.2 crore of refundable customer deposits. The money had arrived, but the customer obligation had not disappeared. I had allowed a useful cash view to carry an income meaning it could not support.

I am Mathew Vezqavni, the fictional CFO of Nezqamvi Mobile Power in Ranchi. We rent mobile battery units and provide temporary-power project services. Eighteen finance colleagues work through three leads within my ₹2.4 crore annual function expense. The company's 230 employees and ₹72 crore FY 2026 revenue describe the enterprise, while its 30 MWh fleet figure describes rated storage energy. None of those measures should be mistaken for my personal spending authority or a promise of energy delivered to a customer.

My work concerns the financial meaning of a fleet that can look busy before its economics are clear. A unit can be allocated to a job while moving between sites, waiting without a billable entitlement or undergoing service. A resale assumption can make a current charge look comfortable without evidence that the expected proceeds will exist. A commercially attractive rental can carry movements and obligations the first margin account has omitted. The cases retain the choices and the costs of correcting those accounts.

Collections kept their customer obligation

The ₹3.2 crore refundable-deposit component stayed separate from ₹9.4 crore earned amounts. We corrected the management account before statutory closing and incurred ₹27 lakh of review expense, without claiming new cash recovered.

Allocated days were not all invoiceable days

The 31,500 scheduled unit-days separated into 24,400 billable days, 3,100 movement days, 2,500 unpaid-hold days and 1,500 service days. The classification changed the expansion discussion without pretending that a calendar count measured delivered energy.

The residual estimate affected a future charge

A ₹30 crore carrying amount with five years remaining produced a different prospective illustration when estimated residual proceeds moved from ₹12 crore to ₹4.8 crore. The assumption needed evidence before the lower charge could be defended.

Current focus

I am working on an operating and finance account that shows how a fleet earns, what remains payable or refundable, and which asset assumptions need review before another investment is approved.

Conversations I welcome

Selected discussions about rental economics, finance controls and a possible first outside board contribution, subject to preparation, employment and relationship review.

Chapter I

Preface

I grew up in Mangaluru and studied commerce because I wanted to understand how an ordinary business knew whether its activity was paying for the obligations behind it. At the fictional Nevqarthi Commerce College, where I graduated in May 1997, the statements were orderly. My first job introduced the less orderly records from which a rental business had to build them: equipment movements, customer acknowledgements, deposits, repair accounts and amounts that had arrived before their purpose was clear.

I joined Tezqermni Equipment Leasing in June 1997 as an accounts assistant. The invented firm had forty-four employees and ₹7.2 crore revenue for FY ending March 1998. I reported to the branch accountant, with no staff or spending delegation. I learned to follow a receipt back to the obligation it related to instead of treating the bank entry as a complete explanation. A customer might have paid for a period, provided a deposit or settled a separate charge. The distinction influenced what the company had earned and what it still needed to account for.

In March 2004 I became branch finance manager. Tezqermni then employed 110 people and recorded ₹26 crore revenue for FY ending March 2005. Seven colleagues worked within my ₹54 lakh annual function expense. The role gave me responsibility for connecting a branch's activity with its finance account. A machine could be reserved but not yet dispatched, returned but not yet inspected, or available operationally while the customer terms still required clarification. I wanted the record to preserve those differences before a convenient summary reached management.

I joined Nezqamvi in September 2011 as financial controller. At that stage the company supplied temporary-power equipment and project services; the present mobile-battery fleet was not already in place. It had seventy-five employees and ₹19 crore revenue for FY ending March 2012. Nine finance colleagues worked within a ₹1.1 crore annual function envelope. The move broadened my responsibility from a branch to company controls, while keeping me close to the practical evidence of equipment deployment. Finance needed to understand the service events without taking over technical decisions about what could be safely used.

The finance-director appointment followed in January 2018. It was a functional title and did not carry a statutory board seat. Nezqamvi had 184 employees and ₹51 crore revenue for FY ending March 2019. I led fifteen colleagues within ₹1.8 crore annual expense and reported to the chief executive. The business wanted faster management reporting as its activities expanded. I supported a concise collections dashboard because it appeared to give a timely view of performance. In 2020 I allowed that view to imply that all the money received had been earned.

Asha's reconciliation separated the ₹12.6 crore quarter into ₹9.4 crore earned amounts and ₹3.2 crore refundable deposits. I had approved the dashboard and needed to correct its interpretation. We revised the management account before statutory closing and spent ₹27 lakh on review and the supporting record. That did not recover cash or establish that money had been stolen. It restored the customer obligation to an account in which I had allowed receipt to imply income. The mistake mattered because a management number can shape decisions before it appears in a formal statement.

I became CFO in June 2022. Eighteen colleagues now work through three leads within ₹2.4 crore annual function expense. I report to CEO Leena Tevqarmi, and Asha is the financial controller. The current company has 230 employees and recorded ₹72 crore FY 2026 revenue, comprising ₹47 crore rentals and ₹25 crore project services. Founder shareholders own 44%, the growth investor 41% and the employee vehicle 15%. My 0.1% holding is within that vehicle. I present finance matters to the board through the CEO but have not become a statutory director.

The battery fleet has made some distinctions more important, not less. Its 120 units each have a 250 kWh nameplate rating, giving 30 MWh of storage energy. That is not a measure of annual customer delivery or a statement of power output. A scheduled unit-day is also not automatically a billable day. The fleet review separated movements, unpaid holds and service periods from the 24,400 days supporting the rental account. The resulting picture complicated a proposed expansion, but it was more useful than treating every occupied calendar cell as evidence of earning demand.

I also work on the assumptions behind asset values and contract contribution. A residual estimate should not be defended because the resulting expense is convenient, and a rental margin should include the movements and obligations the agreed service actually requires. Qualified accounting and technical owners retain their assessments. My responsibility is to make the financial recommendation clear about the evidence it uses and the questions it cannot settle. I work in English, Kannada and Hindi. A first outside board role would require preparation and a relationship review beyond this executive record, including my employee equity and a realistic provisional allowance of twenty-two days a year.
Chapter II

A Philosophy of Leadership

I want finance to explain what the fleet has actually earned and what the business still owes. Scheduling, cash collection, income and asset value each describe part of that account. They become misleading when a convenient operating number is allowed to stand in for the rest.

Mathew Vezqavni

Chapter III

Areas of Practice

  1. ICash receipts with their obligations intact
  2. IIFleet days that have a commercial meaning
  3. IIIAsset estimates that can be explained
  4. IVRental contribution after the whole commitment

Chapter IV

Selected Work

§ 1

I let a collections dashboard imply that customer deposits had been earned

In 2020, as finance director, I approved a management dashboard showing ₹12.6 crore of quarterly collections under a rental-performance heading. The operating team wanted a timely account before the full closing process, and I regarded the bank reconciliation as a strong basis for it. Asha Dezqarthi questioned the meaning of the total. Her review separated ₹9.4 crore of earned amounts from ₹3.2 crore of refundable customer deposits. Receipt was established; earning the whole amount was not.

I had approved the presentation and needed to correct its interpretation. The commercial sponsor argued that the money had genuinely arrived and that changing the heading would make a strong collection quarter harder to communicate. I agreed that the cash result was real, but not that it could carry an income conclusion. We retained the collections view and added the purpose and continuing obligation beside each component. The customer deposits did not become available performance merely because management preferred a single number.

The correction reached the management account before statutory closing. We incurred ₹27 lakh for review and the supporting record, with the responsible accounting process retaining authority over formal treatment. No cash recovery, theft or lost customer money is claimed. The bank balance had not changed because the presentation was corrected. What changed was the meaning management was entitled to take from it and the evidence required before a receipt appeared in an earned-activity discussion.

The immediate cost included revisiting a dashboard I had promoted as a faster route to clarity. Finance had to explain why a reconciled cash total could still support the wrong conclusion. I would now define the decision a management measure is intended to support before approving its layout and timing. A timely number can be valuable, but its speed does not remove the obligation to say what it represents. The lesson was personal: I had checked that the total was real more carefully than I had checked the inference it invited.

§ 2

A full allocation calendar contained seven thousand days that were not billable

The FY 2026 fleet review showed 31,500 scheduled unit-days. Commercial colleagues used the busy calendar to support a ₹16 crore proposal for twenty additional battery units. The existing fleet comprised 120 units, giving 43,800 nominal unit-days in a 365-day year. I asked for the scheduled days to be connected to the contractual earning event before interpreting them as evidence that the fleet needed to expand. A cell occupied in a planning calendar was not necessarily a day the customer had agreed to pay for.

The review separated 24,400 billable days, 3,100 movement days, 2,500 unpaid-hold days and 1,500 service days. The latter three groups totalled 7,100, and all four reconciled to 31,500. The nominal 43,800-day capacity was a calendar illustration, not a claim that every unit could be deployed safely or continuously. These counts also said nothing by themselves about power output or delivered energy. Operations and engineering retained those assessments.

The commercial head argued that additional units would reduce scheduling pressure and allow the team to pursue opportunities it was turning away. I asked which pressure reflected paid demand and which might be reduced by handling movement and hold periods differently. The CEO deferred the ₹16 crore acquisition proposal and approved ₹1.1 crore for calendar, logistics and commercial review. That expenditure funded investigation and revised arrangements, not a promise that every unpaid day could become revenue.

We kept the expansion option open for a further evidence-based decision. The result was not ₹16 crore saved, because the investment had not been approved and could still be proposed later. Nor did we claim a measured utilisation improvement before the review had produced one. I would establish the earning-state definitions when a unit enters the fleet, so that growth discussions do not begin from a schedule whose apparent fullness finance must later reinterpret. A rental business needs enough equipment to serve demand, but the financial case should distinguish earning demand from the resource consumed in getting ready to serve it.

§ 3

A convenient residual estimate could not decide the remaining annual charge

A 2024 review examined a battery-asset cohort with a ₹30 crore carrying amount and five remaining years in the illustration used for planning. The account assumed ₹12 crore residual proceeds. On a simple straight-line prospective basis, that left ₹18 crore over five years, or ₹3.6 crore annually. The asset team wanted to retain the assumption because an earlier supplier indication had referred to a possible repurchase route. I asked what evidence supported the proceeds under the actual conditions attached to that route.

Qualified technical and accounting owners reviewed condition, remaining-use assumptions and the available commercial evidence. The supplier indication was conditional and was not a binding cash receipt for the amount in our model. The reviewed residual estimate became ₹4.8 crore. Holding the stated ₹30 crore carrying amount and five remaining years constant for the comparison, the prospective annual illustration became ₹5.04 crore: ₹25.2 crore divided by five. The ₹1.44 crore increase was an expense illustration under those assumptions, not an immediate cash payment or a new loss of physical capacity.

Some managers preferred a slower change because the higher charge made the rental economics less comfortable. I rejected choosing the residual assumption from the expense we wanted the business to report. The responsible accounting process determined the actual treatment and any additional assessments required; the numerical example did not prescribe a universal policy or settle every asset's condition. We retained the comparison in the management account with its scope and evidence stated.

The consequence was a less favourable forward cost view and a requirement to revisit pricing and investment assumptions. It did not establish that the assets would ultimately be sold for exactly ₹4.8 crore. That remained an estimate requiring future review. I would ask for the commercial conditions behind a residual figure when the original investment paper is prepared, rather than wait until the figure has become part of the expected margin. A finance leader should be able to explain why an estimate is credible without first explaining why the preferred result needs it.

§ 4

The deployment promise contained more movements than the quoted margin

A 2023 twelve-month project proposal showed ₹8.4 crore service revenue and ₹7.1 crore defined direct costs, implying ₹1.3 crore contribution before company overheads, financing and tax. The customer scope required repeated movements between work areas, but the cost model had included fewer relocations than the service team expected. The sales sponsor wanted to preserve the quote because the account was commercially important. I asked operations to describe the agreed deployment sequence before finance defended the margin.

The revised direct-cost forecast was ₹8.3 crore, an increase of ₹1.2 crore. At the original price, the defined contribution would have been ₹0.1 crore, not ₹1.3 crore. That difference did not arise from an accounting allocation of corporate overhead. It came from work the proposal required but the first model had not fully included. Engineering and service owners retained responsibility for deployment suitability and safe handling; finance did not reduce their scope to make the quote fit.

We returned to the customer with the sequence and the cost consequence. After negotiation, the customer accepted ₹9.1 crore for the agreed scope. Forecast contribution on the ₹8.3 crore cost view was therefore ₹0.8 crore. The commercial team gave up the earlier opening price and accepted a more difficult negotiation, while the business retained responsibility for the service it had described. This was an amended agreement before delivery, not a retrospective attempt to charge for work already promised without qualification.

The completed period recorded ₹9.1 crore earned service revenue and ₹8.55 crore defined direct costs, leaving ₹0.55 crore contribution on that boundary. We kept the ₹0.25 crore shortfall against the revised contribution forecast in the review. That amount was not net profit, and the remaining company costs were not silently treated as zero. I would bring the deployment sequence into the first commercial model next time. The case showed that finance can help preserve a viable agreement without claiming that a corrected forecast makes execution certain or that a larger contract price is value created on its own.

§ 5

The delivered energy was the wrong quantity for the input-energy cost

A defined twelve-project review in 2025 recorded 1,000 MWh of purchased input energy and 820 MWh delivered within the stated customer measurement boundary. The planning account had costed the input-energy component by applying a uniform illustrative ₹6 per kWh to the delivered quantity. That produced ₹49.2 lakh. Applying the same rate to the purchased quantity produced ₹60 lakh, matching the energy component examined in the review. The ₹10.8 lakh difference exposed a mismatch between the quantity being costed and the cost being described.

The commercial team wanted to use the delivered measure because it related directly to the customer's service. I agreed that it mattered, but the supplier-energy expense arose from the input quantity. Engineering colleagues cautioned that the 180 MWh difference could not simply be labelled battery conversion loss. Auxiliary loads, measurement boundaries and changes in stored energy also required consideration. Finance kept that qualification rather than using the ratio to announce a universal efficiency figure.

We revised the project-cost account to use the appropriate measured quantity for this energy component and asked the responsible technical owners to explain the remaining boundary questions. On the limited figures, ₹60 lakh divided by 820,000 delivered kWh is approximately ₹7.32 per delivered kWh. That is an allocation of the reviewed input-energy cost, not a customer tariff, a complete service cost or a technical performance certification. Demand charges, taxes, transport and other costs were outside this particular illustration and still needed their own treatment.

The correction reduced the apparent contribution of the reviewed work. It did not prove that every project should be repriced by the same amount or that the entire energy difference could be removed. I would agree the cost and measurement boundaries before the first proposal model is circulated. Familiar units make a calculation look straightforward, but the financial question is which quantity actually gives rise to the expense. A CFO can insist on that connection while leaving physical interpretation with the people qualified to assess it.

Chapter V

Essays

An invitation

Contact

Selected discussions about rental economics, finance controls and a possible first outside board contribution, subject to preparation, employment and relationship review.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

office@mathewvezqavni.example