Prepared for boards, nomination committees & search advisers

File No. CFO-006

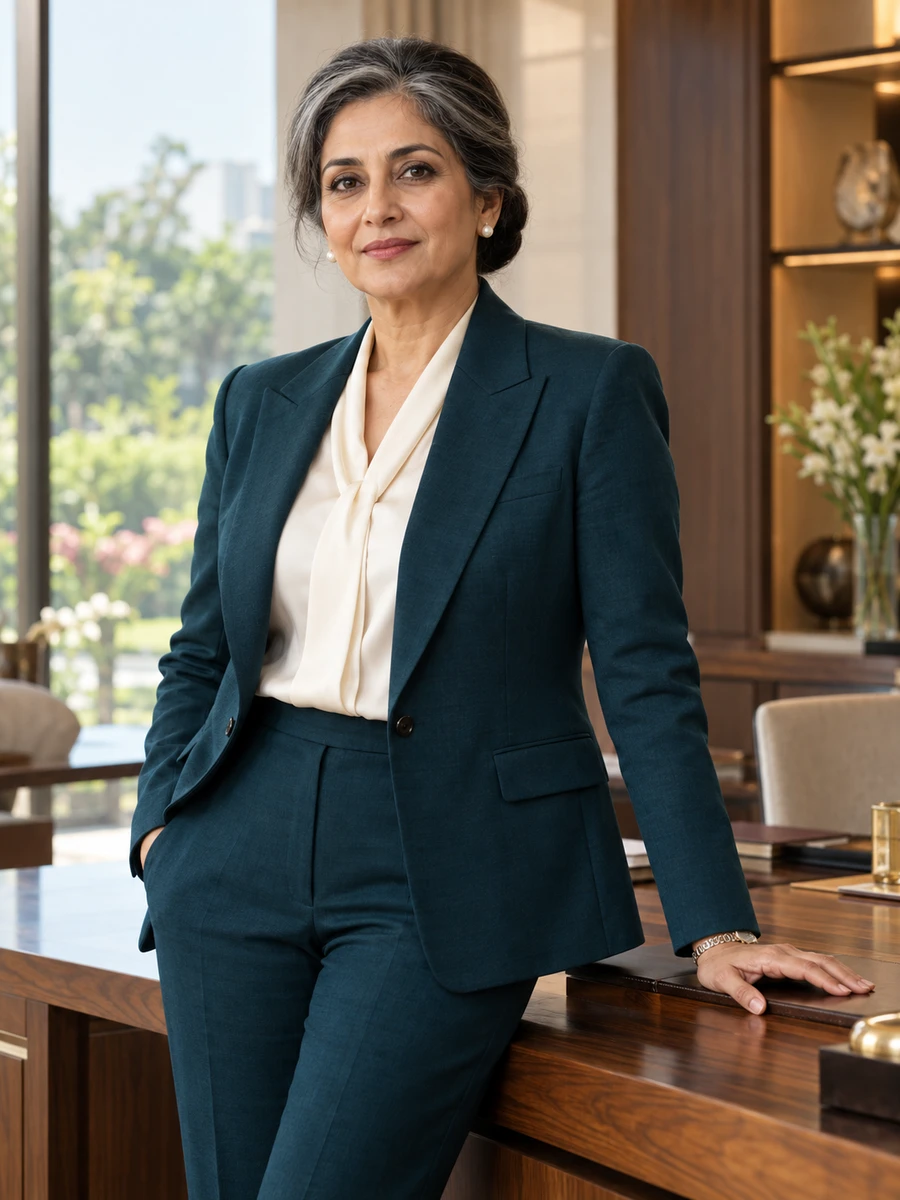
Portrait of Farida Zevqani
Farida Zevqani

Farida Zevqani

The receipt is not the whole financial story

SubjectFarida Zevqani
PositionChief Financial Officer
BaseIndia
LanguagesGujarati, English, Hindi — working proficiency
StatusA first board role involving research or subscription services, subject to fit and consent.

Summary

I once accepted a management sales measure that grouped recurring subscriptions with one-off commissioned studies. The total described business we had won, but its label encouraged a different conclusion: that the same demand could be expected to return. When ₹3.6 crore of project work appeared inside a ₹24 crore annualised recurring measure, I needed to correct the account I had previously allowed. The recurring component was ₹20.4 crore. That did not cancel the project sales or restate statutory revenue. It changed what the number could responsibly support in the next planning discussion.

The receipt is not the whole financial story

A ₹12 crore subscription receipt can arrive before most of the service has been delivered. A research line can appear loss-making after allocated costs even though closing it would leave the company worse off. A cheaper annualised database price can require a much longer commitment than the research plan supports. Those are the distinctions I want finance to make before a reassuring number becomes an executive decision. I am Farida Zevqani, CFO of the fictional Qevmori Financial Research in Surat.

Our 460 colleagues serve 57 institutional clients through research subscriptions and commissioned economic and financial-scenario studies. Revenue for FY ending March 2026 was ₹186 crore. I lead 31 finance colleagues through four managers, with ₹4.6 crore FY 2026–27 function expense and a separate ₹80 lakh capital programme. Rohan is CEO and Anita leads research. We do not lend, take deposits, hold client investments, issue credit ratings or provide personal investment recommendations. My finance role supports the research enterprise; it does not decide which economic conclusion the research should reach.

My career began in publishing accounts in 1993. It taught me to follow the relationship between a customer's payment and the work that remains to be done. I now bring that habit to subscription recognition, supplier commitments, portfolio economics, currency sensitivity and the distinction between recurring demand and a successful one-off study. The cases include a management metric I had allowed to become too broad. I would rather correct that account while keeping the commercial achievement visible than defend a label that asks the next year's budget to rely on work nobody has yet purchased.

₹12 crore received; ₹3 crore earned in the reviewed quarter

For a defined twelve-month service cohort beginning 1 January 2022, the reviewed policy recognised ₹3 crore through March and retained ₹9 crore as a contract liability. The figures exclude GST and describe this cohort, not every research contract or the company's entire revenue.

A reported line loss did not equal avoidable cash cost

A ₹7.2 crore research line carried ₹4.9 crore avoidable cost and ₹3.5 crore allocated costs that would remain after closure. Its reported ₹1.2 crore loss concealed a ₹2.3 crore contribution toward those continuing costs. That was a decision comparison, not proof the line should remain forever.

The annualised price had a three-year condition

We chose a ₹3.6 crore one-year data licence over a ₹9 crore three-year commitment while research needs remained unsettled. The ₹60 lakh first-year premium was real; the uncommitted later years were not automatically cash savings.

Current focus

Subscription obligations, supplier-option costs, avoidable versus allocated expenditure, currency scenarios and honest distinctions between recurring and project demand.

Conversations I welcome

A first board role involving research or subscription services, subject to fit and consent. Fictional IICA registration May 2026; assessment not yet passed, no exemption. No statutory seat; 26 provisional days.

Exhibit ASelected matters

Matter 01Ref. CFO-006-M01

Keeping nine months of service beside the cash already received

A defined subscription cohort paid ₹12 crore for twelve months of continuing research service beginning 1 January 2022. In the March review, the cash receipt appeared beside a commercial account that treated the full amount as the quarter's achievement. The sales result was real, but the accounting question was when the promised service had been delivered. The cohort's reviewed policy treated performance as occurring evenly across the twelve-month term. Amounts in this case exclude GST.

The commercial team wanted the receipt to support an ambitious quarter-end earnings story. I understood the attraction: the customers had paid, the collection risk for that amount had reduced, and the team had done difficult selling work. I asked the controller and qualified advisers to keep those facts separate from recognition. For this cohort, three months of service supported ₹3 crore revenue through March, while ₹9 crore remained a contract liability for the service ahead. Other contract types required their own assessment.

I supported that presentation and asked the operating plan to show the continuing delivery obligation. The decision did not return ₹9 crore to customers or imply that the cash was held in a separate restricted bank account. It meant that the earnings account should not move ahead of performance simply because billing and collection had occurred earlier. Rohan accepted the lower recognised amount in the quarter's discussion while preserving the commercial team's contribution in its proper measure.

The practical cost was a less impressive immediate earnings story and more work explaining the relationship among sales, cash and service. I would have established those measures before the campaign began, so the team did not encounter the distinction only after celebrating collection. Finance should not use accounting language to diminish a genuine sale. It should prevent that achievement from being asked to prove a different event that has not yet happened.
Matter 02Ref. CFO-006-M02

Paying more for one year rather than buying three years we could not yet justify

In 2023 a data supplier offered a three-year licence for ₹9 crore, compared with ₹3.6 crore for a single year. The annualised comparison made the longer agreement appear ₹60 lakh cheaper per year. Research leadership was still reconsidering the scope of the product that used the data, and the contract did not provide the cancellation flexibility the initial business paper assumed. The question was whether the discount justified committing before the future need was clear.

Procurement colleagues preferred the three-year agreement because the lower annualised price was certain on the offered terms. Anita argued that the research direction might change substantially after the next cycle. I asked for the alternatives to show their actual obligations rather than compare only annual averages. The shorter agreement cost ₹3.6 crore for the first year; the longer one committed ₹9 crore across three. The remaining ₹5.4 crore was not a saving under the shorter choice, because future data needs and prices were still unknown.

I recommended the one-year licence and accepted its ₹60 lakh first-year premium against the longer offer's ₹3 crore annualised amount. Rohan approved the recommendation with a review before the next renewal. We did not claim that research would certainly change direction or that the supplier's longer contract was unreasonable. It was an appropriate offer for a customer able to support that commitment, and we could not yet do so.

The consequence was higher near-term cost in exchange for a shorter obligation, not free flexibility. The research team also had to use the review period to clarify its needs rather than postpone the same uncertainty indefinitely. My correction for the next procurement was to involve finance before the annualised saving became the headline. Once that number had been repeated, the discussion sounded like finance opposing a discount when the real disagreement concerned how much future need the company was prepared to purchase.

Matter 03Ref. CFO-006-M03

Testing closure against the costs that would actually leave

A research line generated ₹7.2 crore annual revenue in the FY 2024 review. Its report included ₹4.9 crore avoidable costs and ₹3.5 crore allocated central costs, showing a ₹1.2 crore loss. A proposal to close the line described that loss as a financial improvement available to the company. The problem was that the ₹3.5 crore central cost would remain over the decision period; allocating it elsewhere would not make it disappear.

I initially found the reported loss persuasive. Anita challenged whether the proposed saving described any actual reduction in resources. We rebuilt the comparison around the costs that closure could change. The line contributed ₹2.3 crore toward continuing central costs before those allocations. That did not prove it was strategically valuable or the best use of research capacity, but it did mean that closure could remove contribution while leaving the common expense behind.

We recommended a six-month continuation with a specific commercial and research review instead of immediate closure. The CEO accepted the recommendation. Over that subsequent six-month period, the line produced ₹3.4 crore revenue against ₹2.5 crore avoidable costs, a ₹90 lakh contribution before common costs. This was not ₹90 lakh net profit, and the shorter period could not simply be compared with the earlier annual result as evidence of improvement. The result informed the next decision rather than settling the line's future permanently.

Keeping the line also consumed people and attention that could have served another proposal. That opportunity cost belonged in the review even though it was not an invoice we could eliminate. My lesson was to begin with the actual choices: close, continue, change scope or redeploy capacity. A reporting allocation can help describe the enterprise, but it should not silently become a claim about cash released or resources avoided when management chooses a different course.

Matter 04Ref. CFO-006-M04

Showing the currency assumption before it settled the research budget

The FY 2026–27 planning discussion included a US$1 million data purchase. At an assumed ₹84 per dollar, the rupee amount was ₹8.4 crore before taxes and fees. A sensitivity at ₹94 produced ₹9.4 crore, a ₹1 crore difference for the same dollar amount. These were deliberately stated planning assumptions, not current exchange quotations or predictions of where the currency would trade. The initial budget summary had made the lower figure look like a settled cost.

Research colleagues wanted to preserve product scope and argued that a sensitivity should not automatically reduce investment. Treasury colleagues wanted the exposure visible before the company made customer and supplier commitments on different assumptions. I agreed with both concerns. I asked the paper to separate the research choice, the contractual currency exposure and the range of rupee outcomes. Any hedging or payment arrangement required the proper treasury, legal and qualified advisory review; I did not treat a spreadsheet sensitivity as a completed risk-management action.

Rohan accepted a budget discussion that retained both scenarios and required a fresh assessment before the supplier commitment. We did not claim to have avoided ₹1 crore loss or saved the difference. The higher amount was not an expense already incurred, and the lower amount was not a binding supplier price in rupees. The useful change was that the decision-maker could see how the same research plan depended on a financial assumption that the research team did not control.

The cost was a less simple approval discussion and additional coordination before commitment. I would now show the currency basis beside the first rupee figure, including exclusions and the date or status of the assumption. A CFO should not let a convenient conversion acquire more certainty as it travels through successive presentations. The purpose of the sensitivity was to improve the choice, not to turn finance into a forecaster of exchange rates.

Matter 05Ref. CFO-006-M05

Removing one-off studies from a recurring-demand measure without erasing the sales

In 2025 a management dashboard showed ₹24 crore as annualised recurring demand for a selected sales portfolio. The figure included ₹3.6 crore of one-off commissioned studies. Those studies were valid commercial wins, but no corresponding repeat purchase had been contracted. I had previously accepted the broad dashboard label because it made the portfolio easier to summarise. The planning discussion revealed that colleagues were interpreting it as evidence of a more durable revenue base than the contracts supported.

Sales colleagues objected that removing the studies would make their achievement look smaller. They had won substantial work, and some customers might return. I agreed that the business should recognise that contribution. I asked the team to distinguish the value of the won project from the evidence that it would recur. The revised recurring component was ₹20.4 crore, with ₹3.6 crore shown separately as one-off commissioned work. The total remained ₹24 crore within the management measure.

This was a correction to a planning dashboard, not cancellation of contracts, a cash outflow or a restatement of statutory revenue. Finance and the appropriate people owners reviewed future performance definitions without retrospectively treating valid project sales as misconduct. Rohan supported showing both categories and asked any assumed repeat demand to carry its own basis in the next forecast. We did not set the probability of repetition to zero; we stopped describing an uncontracted possibility as though it had the same standing as the recurring component.

The consequence was a less flattering recurring-demand headline and a more honest starting point for planning capacity. My own error belonged in the explanation. A useful commercial measure should not require the sales team to guess which meaning finance will give it later. I would now define the measure, its exclusions and the decision it is meant to support before using it in incentives or budgets. Precision should preserve real achievement while preventing that achievement from proving a future purchase it cannot establish.

Exhibit BStatement of approach

Before a number decides the argument, I ask what it represents and what would change if we chose differently. An accurate total can still answer the wrong question.

Signed — Farida Zevqani

Exhibit CFormation

  • Bachelor of CommerceQemzuri Commerce College1993

Exhibit DReferences

As CEO, I saw Farida preserve the commercial achievement while correcting the recurring-demand label. She explained her own earlier acceptance of the measure instead of making the sales team carry the whole mistake.
Rohan QelvathiChief Executive Officer, Qevmori Financial Research — fictional colleague
I lead research alongside Farida. In the line review, she changed the financial comparison when I asked which costs would actually leave. That gave us a decision to examine together without asking finance to determine the research conclusion.
Anita QezthariHead of Research, Qevmori Financial Research — fictional colleague

Exhibit EPublished views

CorrespondenceNext steps

An invitation

Contact

A first board role involving research or subscription services, subject to fit and consent. Fictional IICA registration May 2026; assessment not yet passed, no exemption. No statutory seat; 26 provisional days.

Open to
  • Board appointments
  • Speaking invitations

office@faridazevqani.example