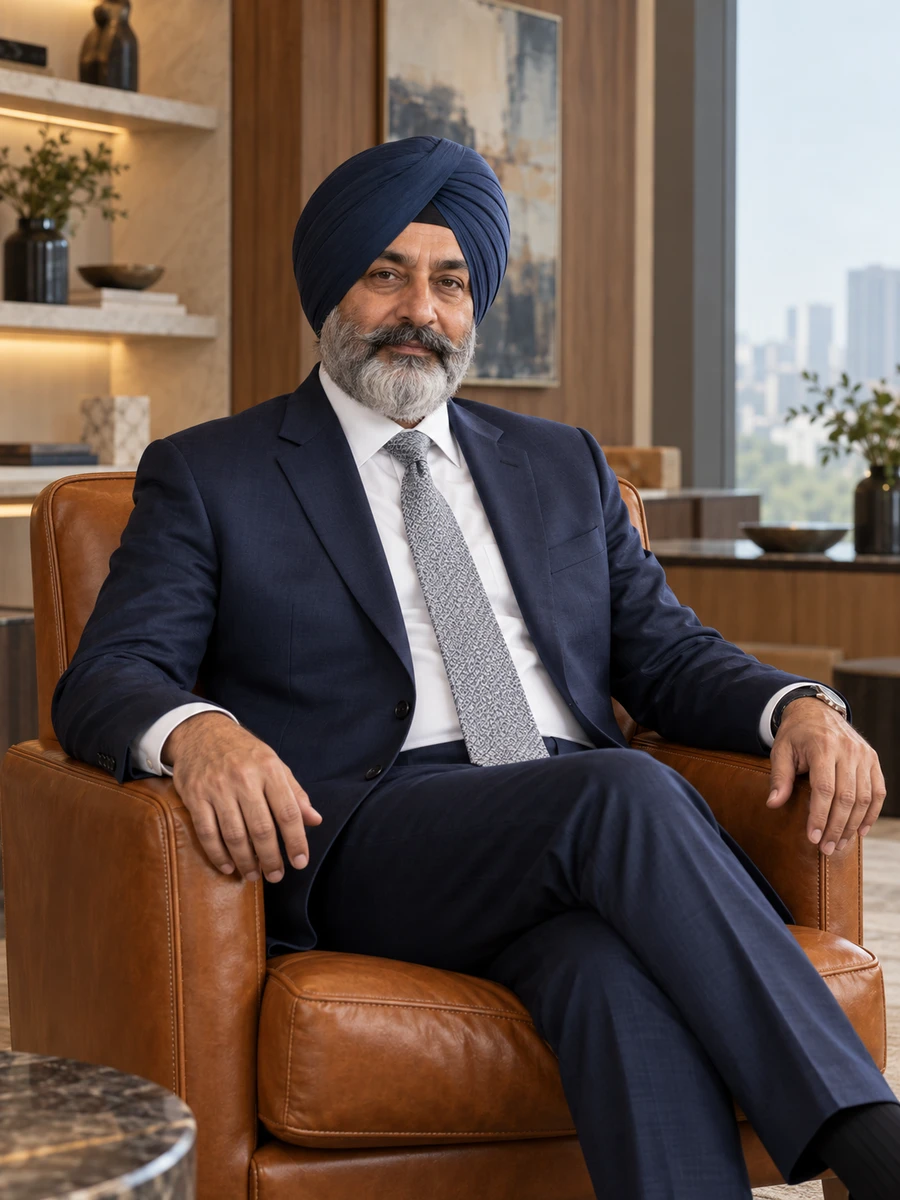
Daler ZevqatiChief Financial Officer
Portrait of Daler Zevqati

Chief Financial Officer · India

DalerZevqati

Know what the number is entitled to describe

I grew up in a Sikh family in Amritsar and completed accounting at Zevqemi College of Commerce in June 1991.

Open to
  • Board appointments
  • Speaking invitations

I lead finance for a digital-preservation business by keeping billable units, service duration and commercial responsibility explicit before a persuasive total becomes the decision.

I am CFO of Qevsuli Preservation Systems in Surat. We support institutional collections through digitisation, workflow software and repository services. I lead twenty-two finance colleagues through three managers and report to the CEO. The enterprise's ₹132 crore FY 2026 revenue is separate from my ₹3.7 crore FY 2026–27 function expense and from the authority held by technical, contractual and client owners.

My career began in print-services accounts in Amritsar. The relationship between a job, the unit priced and the invoice looked routine until the quantities described different things. That lesson followed me into technology, where file counts, software terms and years of service can make the commercial account appear simpler than the work it actually covers.

The cases include a billing counter I had approved, an indefinite-access proposition we declined, a consortium account we narrowed, usage credits we chose not to prepay and a settlement discount we examined against its funding alternative. They retain corrections, costs and commercial limits. I want the reader to see what each financial comparison establishes and what remains outside it.

The file counter was not the contract's billing unit

Twelve invoices charged 1.48 million image files at ₹5, totalling ₹74 lakh before tax. The agreed eligible count was 1.02 million pages, or ₹51 lakh. We issued ₹23 lakh credits and corrected the control I had supported; the excluded duplicates and blanks were not billable under those particular terms.

Five years of costs did not support an indefinite promise

A ₹6 crore upfront proposal relied on a ₹4.9 crore estimate for only its first five years. We declined indefinite-access wording and agreed a defined five-year ₹7.4 crore service with renewal and export responsibilities. The longer future did not become funded merely because the initial period looked affordable.

The combined programme was larger than our own contracted work

A ₹42 crore consortium programme comprised separate customer contracts: ₹16 crore for Qevsuli and ₹26 crore for partners. Our management account stated both scopes clearly. Removing the combined amount from our own order headline was not a ₹26 crore loss of revenue we had earned.

Current focus

I am strengthening the way commercial measures reach management decisions. We need a usable definition beside the total, including the billing object, service term, contracting entity and assumptions behind a volume commitment. Finance works with project and technical owners so the record describes the actual promise rather than a convenient proxy.

Conversations I welcome

I am interested in a first outside board contribution after assessing the specific need, relationships and capacity. I have no statutory seat. Fictional IICA registration began in May 2026 and the proficiency assessment was passed in September 2026; those preparation facts do not determine appointment eligibility or independence. Twenty-six days is a provisional external allowance.

22

Finance colleagues through three managers

₹3.7 crore FY 2026–27 function expense

₹132 crore

Company revenue for FY ending March 2026

₹14 crore operating profit across three service lines

35 years

Print-service accounts to technology finance

Five continuous appointments beginning July 1991

I want the amount in a financial paper to remain attached to what it represents. An image file is not necessarily the page a contract allows us to bill. A five-year cost estimate cannot price an indefinite service promise. A consortium's combined programme is not automatically our company's order book. Finance should make those distinctions useful to the decision, including when correcting them reduces a headline or exposes an assumption I had previously accepted. Precision in the calculation matters, but it cannot repair an incorrectly defined unit, period or responsibility.

Daler Zevqati

Chief Financial Officer

Areas of stewardship

Where accountability has been mine.

  1. IDefining the unit before trusting the invoice
  2. IIFunding a service for the period actually promised
  3. IIIKeeping consortium and company scope distinct
  4. IVComparing volume commitments and cash timing

Selected work

Decisions, and what they changed.

I

Correcting the billing counter I had accepted

In 2022 a review of twelve digitisation invoices showed that the quantity used for billing did not match the relevant agreements.

The full account

II

Replacing an indefinite-access offer with a funded service term

A 2023 proposal offered repository access indefinitely for ₹6 crore upfront.

The full account

III

Keeping our sixteen-crore contract distinct from a forty-two-crore programme

A 2024 consortium opportunity was described internally as a ₹42 crore programme.

The full account

In the words of others

Trusted by those who appoint.

Daler made us reconsider the duration of the promise rather than argue about a margin that covered only its first five years. The resulting offer was more explicit about the service and the decisions that would follow.
Nandita QavmuriCEO, Qevsuli Preservation Systems; fictional colleague
He kept the production count useful while correcting its use in billing. He also acknowledged his approval of the earlier control, which made the review about fixing the account rather than finding someone else to blame.
Arun QazvuniHead of Projects, Qevsuli Preservation Systems; fictional colleague

The journal

Perspective, set down with care.

An invitation

Contact

I am interested in a first outside board contribution after assessing the specific need, relationships and capacity. I have no statutory seat. Fictional IICA registration began in May 2026 and the proficiency assessment was passed in September 2026; those preparation facts do not determine appointment eligibility or independence. Twenty-six days is a provisional external allowance.

Open to
  • Board appointments
  • Speaking invitations

office@dalerzevqati.example