Deeksha VeqthariChief Financial Officer
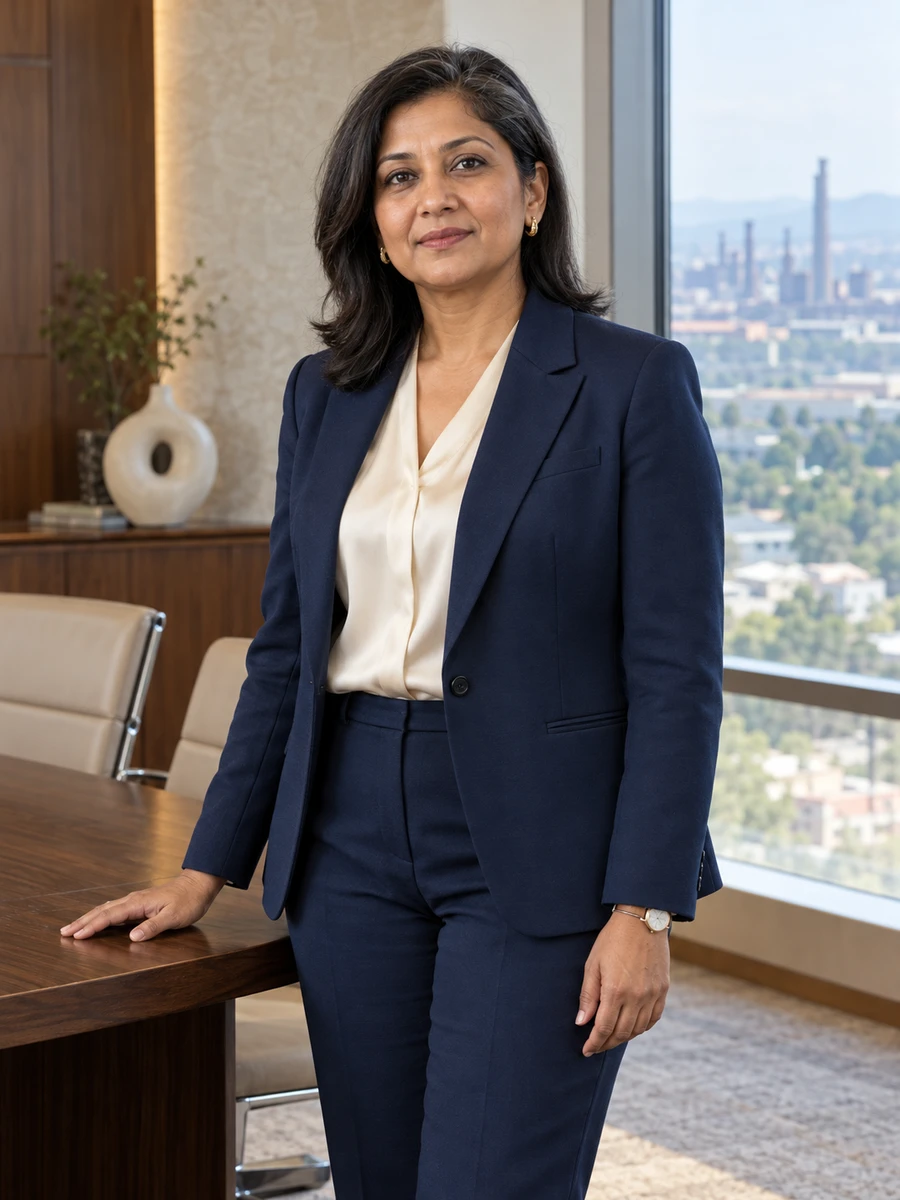
Portrait of Deeksha Veqthari

Chief Financial Officer · India

DeekshaVeqthari

Follow the cash to the obligation it still carries

The kiln equipment quotation was ₹9.8 crore, and I had supported a proposal that allowed it to stand for the project cash requirement.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

Follow the cash to the obligation it still carries

I lead finance at Zevqoshi Kiln Furniture in Rourkela, an industrial ceramic-support manufacturer with 680 employees and plants here and in Sambalpur. For FY ending March 2026, company revenue was ₹264 crore, EBITDA ₹31.2 crore and operating profit ₹18.6 crore. My function has 38 colleagues through four heads and ₹7.8 crore annual expense. I report to CEO Anand Tezqoshi, with no direct equity or statutory appointment. Nisha Nevzuri leads operations and the technical teams retain their release responsibilities.

My career began in cost analysis in 1999. In 2019, as head of planning, I endorsed a kiln proposal framed around a ₹9.8 crore equipment quotation. The project also needed ₹1.4 crore of civil work, ₹1.1 crore of grid connection and ₹0.7 crore of startup cash, bringing its requirement to ₹13 crore. The additional ₹3.2 crore needed approval and the project was delayed nine weeks. That was a failure in the cash account I supported, not a reason to imply that all the expenditure had the same accounting treatment.

My later decisions examine customer advances that must support fulfilment, invoice funding that retains contractual recourse, refinancing whose lower rate does not recover its fee and product contributions measured against scarce kiln space. I work with colleagues to distinguish a cash receipt from economic freedom and a financial model from the operating judgement it supports. The cases retain costs, uncertainty and authority boundaries rather than turn every correction into an achieved increase in profit.

The equipment quote left ₹3.2 crore of project cash outside the proposal

Civil work, grid connection and startup needs took the cash requirement from ₹9.8 crore to ₹13 crore. I owned the incomplete framing, with additional approval and a nine-week delay. The amounts describe project cash, not a claim that every item should be capitalised.

Receiving invoice finance did not remove the contract's recourse

The proposed ₹12 crore invoice pool offered ₹10.8 crore advanced and ₹1.2 crore held back before fees. The agreement retained recourse after thirty days overdue. We limited the pilot to ₹6 crore face value and ₹5.4 crore advanced, without describing financing as complete credit-risk transfer.

Half a percentage point could not recover the refinancing fee

For ₹24 crore over at most two remaining years, a 0.5-point rate reduction could save no more than ₹24 lakh even before principal amortisation. The proposed fee was ₹36 lakh. We declined; the fee exceeded that upper bound, without needing to claim an actual ₹36 lakh net saving.

Current focus

I am making the relationship between a financial amount and its remaining conditions easier to see in manufacturing proposals. That includes the cash needed beyond an equipment quote, fulfilment following a customer advance, recourse retained after financing and the production resource behind a contribution figure. A clearer model can improve the decision account, but its commercial and operating results still need to be demonstrated separately. I want finance to preserve that distinction while helping colleagues choose a practical course.

Conversations I welcome

I would consider an initial outside-board discussion where manufacturing finance and operating economics could add to the existing skills. My fictional IICA record shows March 2026 registration and a September assessment pass, without an exemption. I have no statutory seat or direct holding. Twenty-four provisional days, employer consent and a qualified review of relationships would need to fit the proposed responsibilities before I could accept them.

38

Finance colleagues through four heads

₹7.8 crore annual function expense

27 years

Manufacturing finance from cost analysis onward

Continuous career beginning July 1999

680

People in the manufacturing enterprise

Rourkela and Sambalpur plants; ₹264 crore FY 2026 revenue

I want a proposal to show the obligation that arrives with its cash. A machine quotation is only part of making a kiln project usable. A customer advance arrives before the work it must help fund. An invoice-financing payment can leave credit exposure with the manufacturer. I have approved an incomplete project cash account, and that experience makes me cautious when a precise number appears to settle a decision whose scope is still unfinished.

Deeksha Veqthari

Chief Financial Officer

Areas of stewardship

Where accountability has been mine.

  1. IComplete project cash requirements
  2. IILiquidity after customer commitments
  3. IIIFunding with retained contractual exposure
  4. IVFinancing and contribution comparisons in context

Selected work

Decisions, and what they changed.

I

Reopening a kiln proposal whose equipment price was not its cash requirement

In 2019, as head of planning, I endorsed a kiln proposal framed around a ₹9.8 crore equipment quotation.

The full account

II

Keeping the fulfilment behind customer advances inside the dividend discussion

In 2022 the company had ₹22 crore in bank cash, including ₹8.5 crore of customer advances.

The full account

III

Retaining the recourse behind an invoice-financing receipt

In 2023 a proposed invoice-financing arrangement covered ₹12 crore face value, with ₹10.8 crore advanced and ₹1.2 crore held back before fees.

The full account

In the words of others

Trusted by those who appoint.

Deeksha kept the fulfilment requirement beside the bank balance when the dividend was discussed. She explained the planning reservation without calling it a legal restriction or presenting a smaller distribution as new profit.
Anand TezqoshiCEO, Zevqoshi Kiln Furniture; fictional colleague
Deeksha asked which kiln resource limited the product choice before ranking the unit contributions. She kept demand and production requirements in the discussion rather than letting one ratio become the whole operating plan.
Nisha NevzuriOperations Head, Zevqoshi Kiln Furniture; fictional colleague

The journal

Perspective, set down with care.

An invitation

Contact

I would consider an initial outside-board discussion where manufacturing finance and operating economics could add to the existing skills. My fictional IICA record shows March 2026 registration and a September assessment pass, without an exemption. I have no statutory seat or direct holding. Twenty-four provisional days, employer consent and a qualified review of relationships would need to fit the proposed responsibilities before I could accept them.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

office@deekshaveqthari.example