Deeksha VeqthariLeadership review 2026

Leadership review

Deeksha Veqthari

Chief Financial Officer · India

Follow the cash to the obligation it still carries

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations
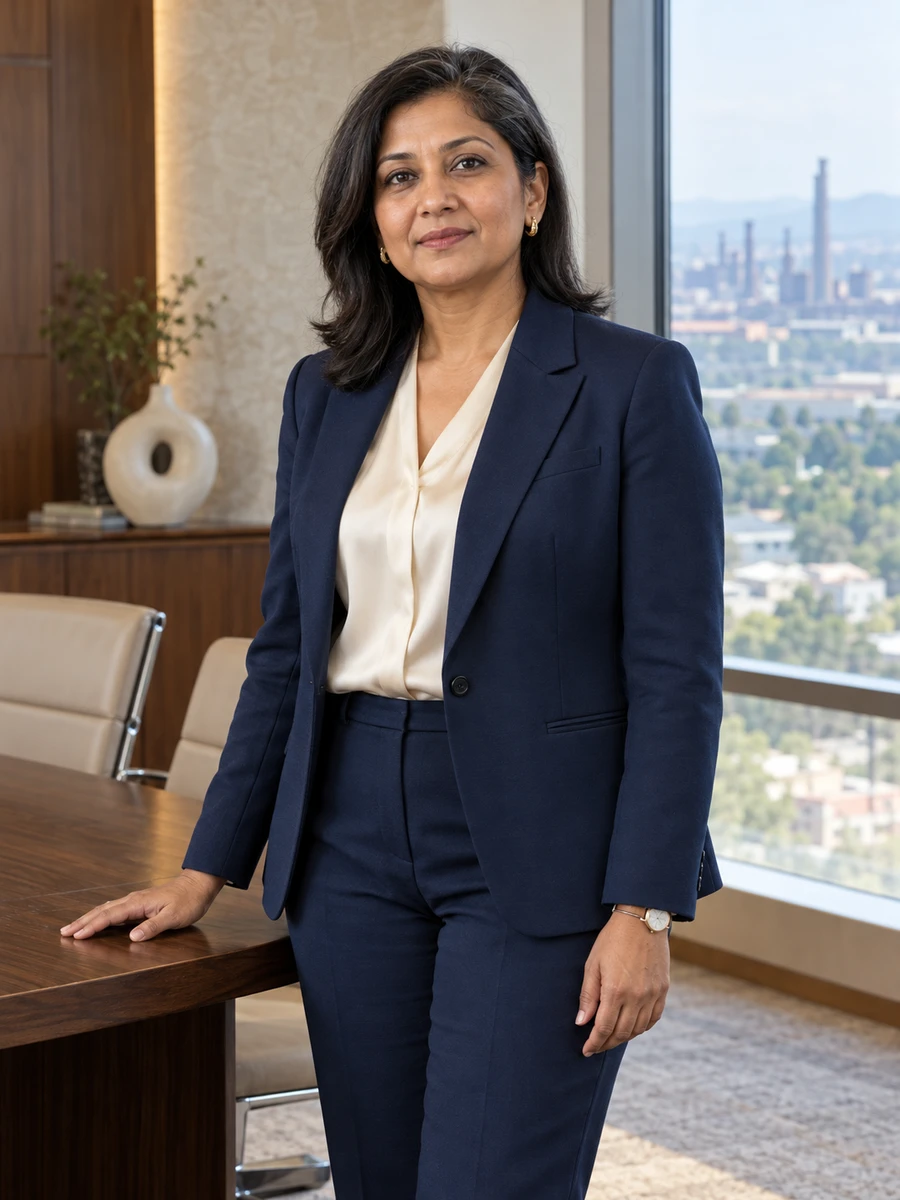
Portrait of Deeksha Veqthari

Follow the cash to the obligation it still carries

I lead finance at Zevqoshi Kiln Furniture in Rourkela, an industrial ceramic-support manufacturer with 680 employees and plants here and in Sambalpur. For FY ending March 2026, company revenue was ₹264 crore, EBITDA ₹31.2 crore and operating profit ₹18.6 crore. My function has 38 colleagues through four heads and ₹7.8 crore annual expense. I report to CEO Anand Tezqoshi, with no direct equity or statutory appointment. Nisha Nevzuri leads operations and the technical teams retain their release responsibilities.

My career began in cost analysis in 1999. In 2019, as head of planning, I endorsed a kiln proposal framed around a ₹9.8 crore equipment quotation. The project also needed ₹1.4 crore of civil work, ₹1.1 crore of grid connection and ₹0.7 crore of startup cash, bringing its requirement to ₹13 crore. The additional ₹3.2 crore needed approval and the project was delayed nine weeks. That was a failure in the cash account I supported, not a reason to imply that all the expenditure had the same accounting treatment.

My later decisions examine customer advances that must support fulfilment, invoice funding that retains contractual recourse, refinancing whose lower rate does not recover its fee and product contributions measured against scarce kiln space. I work with colleagues to distinguish a cash receipt from economic freedom and a financial model from the operating judgement it supports. The cases retain costs, uncertainty and authority boundaries rather than turn every correction into an achieved increase in profit.

The equipment quote left ₹3.2 crore of project cash outside the proposal

Civil work, grid connection and startup needs took the cash requirement from ₹9.8 crore to ₹13 crore. I owned the incomplete framing, with additional approval and a nine-week delay. The amounts describe project cash, not a claim that every item should be capitalised.

Receiving invoice finance did not remove the contract's recourse

The proposed ₹12 crore invoice pool offered ₹10.8 crore advanced and ₹1.2 crore held back before fees. The agreement retained recourse after thirty days overdue. We limited the pilot to ₹6 crore face value and ₹5.4 crore advanced, without describing financing as complete credit-risk transfer.

Half a percentage point could not recover the refinancing fee

For ₹24 crore over at most two remaining years, a 0.5-point rate reduction could save no more than ₹24 lakh even before principal amortisation. The proposed fee was ₹36 lakh. We declined; the fee exceeded that upper bound, without needing to claim an actual ₹36 lakh net saving.

Current focus

I am making the relationship between a financial amount and its remaining conditions easier to see in manufacturing proposals. That includes the cash needed beyond an equipment quote, fulfilment following a customer advance, recourse retained after financing and the production resource behind a contribution figure. A clearer model can improve the decision account, but its commercial and operating results still need to be demonstrated separately. I want finance to preserve that distinction while helping colleagues choose a practical course.

Conversations I welcome

I would consider an initial outside-board discussion where manufacturing finance and operating economics could add to the existing skills. My fictional IICA record shows March 2026 registration and a September assessment pass, without an exemption. I have no statutory seat or direct holding. Twenty-four provisional days, employer consent and a qualified review of relationships would need to fit the proposed responsibilities before I could accept them.

Highlights

The cash beyond the quotation changed my planning judgement

38

Finance colleagues through four heads

₹7.8 crore annual function expense

27 years

Manufacturing finance from cost analysis onward

Continuous career beginning July 1999

680

People in the manufacturing enterprise

Rourkela and Sambalpur plants; ₹264 crore FY 2026 revenue

A letter from Deeksha Veqthari

Dear reader,

Portrait of Deeksha Veqthari

I want a proposal to show the obligation that arrives with its cash. A machine quotation is only part of making a kiln project usable. A customer advance arrives before the work it must help fund. An invoice-financing payment can leave credit exposure with the manufacturer. I have approved an incomplete project cash account, and that experience makes me cautious when a precise number appears to settle a decision whose scope is still unfinished.

The kiln equipment quotation was ₹9.8 crore, and I had supported a proposal that allowed it to stand for the project cash requirement. In 2019 we still needed ₹1.4 crore of civil work, ₹1.1 crore of grid connection and ₹0.7 crore of startup cash. Together those items brought the requirement to ₹13 crore. The additional ₹3.2 crore required approval and the project lost nine weeks. I was head of planning, and the incomplete framing belonged in my account of the decision. The correction made the cash requirement clearer; it did not make the original proposal complete after the fact.

Deeksha Veqthari

Chief Financial Officer
Strategic priorities

Where I focus my leadership.

Performance

What the priorities delivered.

Priority outcome 01

Reopening a kiln proposal whose equipment price was not its cash requirement

In 2019, as head of planning, I endorsed a kiln proposal framed around a ₹9.8 crore equipment quotation. The account left out ₹1.4 crore of civil work, ₹1.1 crore of grid connection and ₹0.7 crore of startup cash. Those items brought the requirement to ₹13 crore. Operating colleagues had described work needed beyond the supplier's scope, but I had not assembled it into the proposal's funding account with sufficient care. The apparently precise equipment amount became a less complete statement about the enterprise's commitment. We reopened the proposal and obtained additional approval for ₹3.2 crore. The project was delayed nine weeks. I retained responsibility for the framing instead of describing every omitted item as a later change by another team. The amounts represented project cash requirements; they did not establish that every item should be capitalised or receive identical accounting treatment. That assessment remained a separate professional responsibility. The immediate correction was to show the resources required to make the proposed equipment usable in its operating setting. The consequence was more than an unfavourable variance in a report. Colleagues had planned around an incomplete funding account and needed a revised approval and sequence. We did not claim that identifying the omitted work created a saving or that the later approval recovered the delay. The supplier quotation could remain accurate for its own scope while our enterprise proposal was incomplete. Keeping that distinction visible made it possible to acknowledge the failure without inventing a fault in every underlying amount. I changed the planning review so operating requirements had to be reconciled with the cash account before the equipment figure became the headline commitment. Finance needed to ask what made the project usable, not only what was being purchased from the principal supplier. I still use quotations as evidence, but do not let their precision imply completeness. The case remains a decision I supported inadequately, with the additional funding and nine-week delay retained as consequences rather than converted into a success story about discovering a more accurate number.

Priority outcome 02

Keeping the fulfilment behind customer advances inside the dividend discussion

In 2022 the company had ₹22 crore in bank cash, including ₹8.5 crore of customer advances. Estimated fulfilment cash of ₹6.2 crore was expected in the following quarter. A proposed ₹5.5 crore dividend looked easier to support when the bank balance was discussed without that delivery account. Some owners favoured a distribution after a period of retained investment. Operating colleagues wanted the upcoming work and its cash needs visible before the balance was treated as evidence of room for another commitment. I recommended reserving ₹6.2 crore internally for fulfilment planning. The board reduced the proposed dividend to ₹2 crore. The reservation was a management planning decision, not a statement that the funds were legally restricted. It also did not establish that the remaining bank balance was freely distributable: other flows, requirements and professional assessments still mattered. My contribution was to make the obligation following the receipt part of the decision, while the board retained authority over the distribution. The lower dividend disappointed those who preferred the larger immediate payment. We accepted that trade-off and explained why a customer advance did not represent economic freedom from the work it was intended to support. The ₹3.5 crore difference in the proposed distribution did not create new profit. Nor did the reserve prove that fulfilment would occur at exactly the estimated cost. The plan needed updating as the work and its evidence developed, with uncertainty visible rather than hidden inside a reassuring opening balance. The case changed how I framed liquidity conversations. A receipt should arrive with an account of the cash demands still attached to the business, even when no legal restriction prevents spending it elsewhere. That does not mean all advances must be segregated under one universal formula. It means the enterprise should understand the consequences before making a competing commitment. Finance can support a distribution decision more usefully by explaining the relevant future work than by allowing the cash already in the bank to become a complete argument on its own.

Priority outcome 03

Retaining the recourse behind an invoice-financing receipt

In 2023 a proposed invoice-financing arrangement covered ₹12 crore face value, with ₹10.8 crore advanced and ₹1.2 crore held back before fees. Its specific contract retained recourse to our company after thirty days overdue. A treasury presentation described the proposal as releasing cash and transferring the customer credit risk. The first claim concerned liquidity; the second required a closer reading of obligations. Finance and commercial colleagues questioned whether the cash receipt could support such a broad statement about exposure under the actual terms. I withdrew the claim of complete credit-risk transfer and limited the pilot to ₹6 crore of invoices, with ₹5.4 crore advanced before fees and the corresponding retained balance. The pilot preserved a liquidity purpose while keeping the recourse condition in the decision and monitoring account. It did not settle the accounting classification by shorthand. The recognition and presentation questions required qualified assessment of the complete contract and applicable requirements, rather than a conclusion drawn from the word factoring or from one condition alone. The narrower programme gave up some immediate funding capacity and required a more careful explanation of what the arrangement achieved. Receiving an advance could still be useful without claiming that every obligation had moved to the funder. We retained the customer's payment exposure where the terms left it and did not label the held-back amount a fee. The ₹1.2 crore in the larger proposal was a holdback before fees; the charges needed their own account. Those distinctions prevented the funding story from becoming more favourable than the agreement supported. I learned to make cash movement and risk movement separate questions at the beginning of a funding discussion. A contract can change timing without transferring all the consequences of non-payment. The pilot was not proof that every later invoice would perform or that all financing arrangements have the same terms. It was a bounded decision under a particular fictional agreement, with monitoring and professional review still required. My role was to make that boundary intelligible before a receipt acquired the misleading meaning of a risk that had disappeared.

Priority outcome 04

Declining a lower fixed rate whose fee exceeded the possible interest benefit

In 2024 we considered refinancing a ₹24 crore loan carrying a 9% fixed rate, with 24 months remaining and principal declining through scheduled repayments. The alternative offered an 8.5% fixed rate and a ₹36 lakh fee. A lower rate was attractive in the initial discussion. The relevant question was how much interest the reduction could save over the actual remaining balance and term, rather than whether 8.5 was lower than nine. I asked the team to establish a generous upper bound before treating the offer as an economic improvement. Even if ₹24 crore remained outstanding for the full two years, a half-percentage-point reduction would save only ₹24 lakh. Actual principal amortisation would reduce that benefit further. The ₹36 lakh fee already exceeded the upper bound before considering payment timing. We declined the proposal. The reasoning did not require a claimed precise present-value result, because the stated terms were insufficient even under the favourable assumption that the balance did not fall. Both rates were fixed in this comparison, and the account made no prediction about future market rates. The decision gave up a lower headline rate and the appearance of a refinancing achievement. I did not report the unspent ₹36 lakh fee as an actual net saving, because declining the transaction also meant not receiving its interest reduction. The useful outcome was a rejected proposal whose economics did not support its headline advantage. Finance needed to explain that conclusion plainly enough for colleagues to assess the alternative without mistaking a percentage improvement for a benefit larger than the cost of obtaining it. The lesson was to keep the fee, remaining life and balance pattern beside the quoted rate. A different loan or set of terms might lead to a different decision; this case supplies no universal recommendation against refinancing. It shows why a simple bound can be more informative than an elaborate model built around an attractive headline. I wanted the team to understand which assumptions could change the conclusion and which could not, so a decision to retain the existing arrangement could be described as a considered choice rather than an absence of financial initiative.

Priority outcome 05

Changing the contribution comparison to include scarce kiln-position time

In 2025 a product comparison favoured item A because its contribution was ₹1,200 per unit against ₹900 for item B. The kiln resource was constrained, and the products used different amounts of it: A required six kiln-position hours per unit, while B required three. On that resource basis, the figures were ₹200 and ₹300 per position-hour respectively. The larger contribution per unit did not automatically identify the better use of the scarce capacity. Commercial colleagues valued the familiar unit measure, while operations wanted the resource consumption visible. We funded ₹42 lakh of costing work to incorporate the relevant kiln-position account into the comparison. I did not instruct the business to replace every A order with B. Demand, technical requirements, quality, product mix and existing customer commitments still constrained the decision. The contribution figures were commercial measures, not net profit or an account of every factory cost. The revised analysis supported a more useful discussion about allocation and quotations without claiming that a single ratio could select the entire production plan. The change made the commercial explanation less simple. A product that looked stronger by unit needed to be examined against the resource it consumed, and a product that looked weaker could become more attractive within a particular constraint. We did not claim an achieved margin increase from funding the model or assume that every available hour could be sold at the illustrated contribution. The work required ongoing collaboration with the people responsible for demand and production, whose evidence determined where the comparison was relevant. I learned to ask what limits the choice before deciding which denominator should lead the financial discussion. Per-unit contribution remains useful for some questions, but it cannot answer every capacity question when units require different resources. The case is not a universal product-ranking rule or a technical claim about kiln operation. It is an example of finance making the constraint visible and preserving the other conditions that management must weigh. The value lies in a better decision account; the resulting operating and financial outcomes still require their own evidence.

Stakeholder voices

What those I have served alongside say.

Deeksha kept the fulfilment requirement beside the bank balance when the dividend was discussed. She explained the planning reservation without calling it a legal restriction or presenting a smaller distribution as new profit.
Anand TezqoshiCEO, Zevqoshi Kiln Furniture; fictional colleague
Deeksha asked which kiln resource limited the product choice before ranking the unit contributions. She kept demand and production requirements in the discussion rather than letting one ratio become the whole operating plan.
Nisha NevzuriOperations Head, Zevqoshi Kiln Furniture; fictional colleague

Outlook

Perspectives on what comes next.

An invitation

Contact

I would consider an initial outside-board discussion where manufacturing finance and operating economics could add to the existing skills. My fictional IICA record shows March 2026 registration and a September assessment pass, without an exemption. I have no statutory seat or direct holding. Twenty-four provisional days, employer consent and a qualified review of relationships would need to fit the proposed responsibilities before I could accept them.

Open to
  • Board appointments
  • Advisory roles
  • Speaking invitations

office@deekshaveqthari.example