One period for the old and new asset
For a repowering review, I asked for eighteen-month exported energy on both sides of the decision. The new forecast included the transition gap, and the eventual 118 GWh result stayed below its 124 GWh forecast.
A leadership monograph
Harleen Mevqani
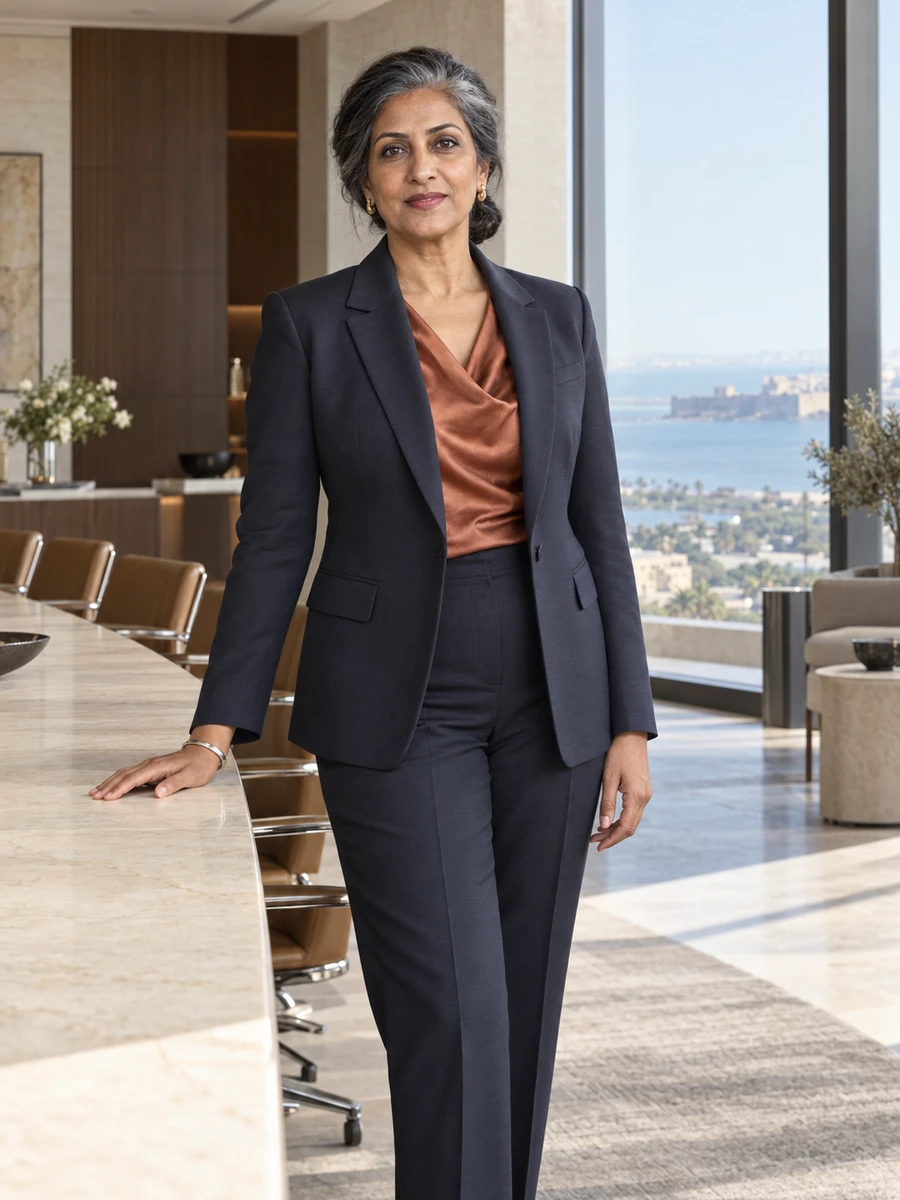
Chief Executive Officer · India · Volume I · 2026
Chapter I
I grew up in Amritsar and first became interested in the practical life of machines through mechanical engineering. At Neqvarthi Engineering College, where I completed my degree in June 1990, the drawing could explain how an assembly should work. My first job taught me how much a service response depended on circumstances outside that drawing. The part, the person, the route and the customer's operating window all had to meet before a repair became useful.
I joined the fictional Tezqorvi Rotating Services in July 1990 as a field-service engineer. The regional company employed seventy-six people and recorded ₹11 crore revenue for FY ending March 1991. I worked under senior engineers, without authority over staff or expenditure. Senior colleagues expected a clear account of what had been observed, which specialist had assessed it and what still prevented the next step. I learned that saying a component was available did not establish that the whole repair could proceed.
In March 1998 I became service manager. Tezqorvi had grown to 182 employees and ₹46 crore revenue for FY ending March 1999. Twenty-four colleagues worked within my ₹3.6 crore annual service expense. The role moved me from explaining a particular assignment to making commitments across several. We had to balance customer expectations, specialist capacity and the conditions at each site. A standard offer made the business easier to describe, but I could already see that a standard description needed an honest account of its limits.
I joined Vezqamri in June 2006 to lead wind operations. At that point the invented business had 148 employees, 62 MW of owned capacity and ₹51 crore annual revenue for FY ending March 2007. I led fifty-six operations colleagues within a ₹14 crore function envelope. The owner perspective changed the time horizon. The company carried obligations between planned maintenance visits and had to account for exported energy, service costs and the condition of its assets. Engineering and safety owners retained their decisions; my job was to organise an operating account that did not lose their constraints on its way to management.
The chief operating officer appointment followed in October 2013. Vezqamri then employed 276 people, owned 188 MW and reported ₹182 crore revenue for FY ending March 2014. Four operating heads and 154 employees sat within my remit, with ₹67 crore annual function expense. I reported to the chief executive. That position encouraged me to look for a coherent portfolio offer, and in 2016 I supported a response commitment whose simplicity outran the site work beneath it.
Planned shutdowns at a six-machine customer cluster occupied fourteen days during a strong wind period. Safiya's earlier challenge about the local resource pattern had not received sufficient weight in my approval. The review estimated 1.8 GWh of foregone generation against a stated operating counterfactual; it did not measure energy that had actually been exported. We accepted ₹1.4 crore in contractual customer credits and funded ₹1.8 crore of revised scheduling and service coverage. The credits were not a tariff-based valuation of the estimated lost energy. I needed to explain why a satisfactory annual availability measure had distracted me from when the machines were unavailable. Subsequent schedules considered resource periods and customer commitments together, without pretending that every maintenance outage could be eliminated.
I became CEO and an executive director in April 2021. Seven functional heads now report to me, and I report to the board through its separate chair, Uday Nezqorthi. The present 410-person company combines owned generation and services. Our FY 2026 revenue of ₹388 crore comprises ₹334 crore from generation and ₹54 crore from services. The ₹176 crore annual operating envelope and separate ₹98 crore capital programme are board-approved programmes with delegated responsibilities; they are not personal authority to spend any amount without further approval.
My later decisions have required a wider account of transition. We compared a repowering proposal over the same eighteen months as its old-asset alternative, accepted a result below forecast and kept the counterfactual separate from measured generation. We narrowed an access route when five agreements remained unresolved. We declined a more concentrated commercial offer and recorded the foregone contribution. We also kept a year of lower exported energy visible while examining its different causes. None of those decisions can be assessed only from the capacity at the end of the period.
I live in Bhavnagar and work in English, Punjabi and Hindi, with working Gujarati. I hold 0.2% equity through the employee vehicle and one executive directorship. My fictional databank registration dates to February 2026, with proficiency assessment still outstanding and no exemption asserted. A possible outside appointment would need to fit that continuing responsibility. I would bring experience of asking what a growth proposal leaves the enterprise carrying between its starting point and the future it describes, including the consequences of an operating promise I once made too easily.
Chapter II
I want the approval account to include the months in which the old asset has stopped and the new one has not yet earned. Capacity, access, customer commitments and a funded transition belong in the same leadership conversation. A better future machine does not make today's obligations disappear.
Harleen Mevqani
Chapter III
Chapter IV
§ 1
In 2016, as COO, I approved a common maintenance calendar across a contracted service portfolio. The arrangement simplified staffing and gave customers a concise annual availability account. Safiya Fezqarthi asked whether the local resource patterns justified using the same window at every site. I accepted the programme team's view that a consistent annual hours measure was sufficient for the commercial discussion. That was my decision, and it overlooked when the unavailable hours would occur.
At a six-machine customer cluster, planned shutdowns occupied fourteen days of a strong wind period. The subsequent review estimated 1.8 GWh of foregone generation against a stated operating counterfactual. That was not metered export, and weather and operating assumptions remained part of the estimate. The annual hours measure could still appear satisfactory while concealing a period with a different energy consequence. We had made the calendar easy to explain without adequately examining its value to that customer.
We accepted ₹1.4 crore in contractual customer credits. The credits followed the commercial arrangements; they were not a tariff-based valuation of the estimated 1.8 GWh. I also secured ₹1.8 crore for revised scheduling and service coverage. Operations, engineering and safety owners retained authority over the work itself. The correction did not mean moving maintenance into a period simply because a forecast looked attractive, or promising that every unavailable hour could be eliminated. It meant bringing the resource pattern, safe working conditions and customer commitments into the planning decision together.
The result was a different approval process and a real commercial cost, not proof of a precise amount of energy recovered later. The service programme became less uniform and required more coordination. I accepted that consequence because the apparent consistency had been purchased by ignoring a difference that mattered. In hindsight I would have asked Safiya to present the site-level objection before approving the common offer. The lesson was not that an hours measure is useless. It was that I had allowed one valid measure to stand in for the whole customer outcome.
§ 2
The 2022 investment review proposed replacing forty 0.8 MW machines, 32 MW in total, with twelve 4 MW machines totalling 48 MW. The development presentation led with a mature-year estimate of 150 GWh compared with 62 GWh for the existing fleet. Both figures were estimates, but they did not explain the transition. The proposal required dismantling, construction and commissioning before the replacement assets could earn. Finance asked for that interval to appear in the same period as the energy comparison.
I requested an eighteen-month account for both alternatives. Retaining the old assets was estimated to deliver 93 GWh over that period. The replacement path, including a seven-month transition gap and its ramp-up assumptions, forecast 124 GWh. Those figures made the relevant forecast difference 31 GWh over eighteen months, not a claim that the mature-year difference of 88 GWh would be available immediately. Qualified technical and commercial owners remained responsible for yield assumptions, site arrangements and the conditions for proceeding.
The board approved the ₹264 crore project in stages, with transition funding and review points stated. This was a specific multi-year investment approval, separate from the current annual capital programme quoted elsewhere in the profile. Development colleagues disliked the less dramatic opening comparison and the additional conditions. I regarded those as necessary to understand the commitment rather than as an argument against replacing old machinery.
The first eighteen months produced 118 GWh of metered export, six below the 124 GWh forecast. The old-asset counterfactual remained 93 GWh in the review. Subtracting it gives a modelled difference of 25 GWh, not a directly measured causal gain: we did not operate both alternatives on the same site. We retained the shortfall and examined its causes before the next stage. The larger installed capacity did not erase it. I would establish the common comparison period before selecting the presentation's headline, so that a compelling future annual figure does not become the account everyone is reluctant to revise.
§ 3
A 2023 access proposal offered a convenient consolidated route for work at a wind cluster. An aggregator had assembled twenty-six underlying agreements into one programme account. The project team wanted to approve the route and resolve remaining particulars during mobilisation. The land and operating review showed that five agreements still had unresolved use conditions. The aggregate proposal was useful evidence of work undertaken, but it did not establish that all twenty-six relationships were ready for the company's intended use.
I stopped the route approval while the responsible land and legal advisers examined the underlying circumstances with the parties. We did not describe the unresolved five as defective ownership or wrongdoing. The question was narrower: what use had actually been agreed, by whom, and what remained outstanding for this programme? Safiya supported a slower account because the operating plan depended on the route in practice, not merely its appearance on the project drawing. The delivery sponsor argued that the delay would disrupt the contractor sequence and increase cost.
Twenty-one agreements were subsequently clarified for the intended route conditions. Five remained unresolved. Qualified planners developed an alternative access arrangement using the cleared relationships, and we approved ₹4.2 crore of additional route work. The programme moved by ten weeks. Those costs were part of the decision, rather than a reason to describe the original aggregate signature as more conclusive than it was. No claim is made that the alternative settled every future use or conferred a wider right over neighbouring land.
The immediate result was a narrower supported access plan with five outstanding relationships kept outside it. I accepted the extra work and the disruption to the original schedule. The case changed what I ask to see when a portfolio proposal depends on many local agreements: the unresolved relationships need their own account before the combined number becomes an approval premise. Next time I would require that account before fixing the contractor sequence, reducing the pressure on local parties and advisers to treat a timetable as evidence that consent work was complete.
§ 4
In 2024 a commercial proposal would have placed ₹152 crore of projected annual generation receipts with one buyer in a forward plan totalling ₹400 crore. The 38% concentration made the offer consequential beyond its headline price. The buyer was not alleged to be insolvent or unreliable. The issue was the exposure our own portfolio would carry if payment or volume assumptions changed. Commercial colleagues favoured the larger commitment because it improved the immediate contract account and reduced the number of relationships to manage.
I asked finance and commercial owners to examine a narrower ₹96 crore commitment alongside other allocations. In the revised planning case, projected generation receipts were ₹384 crore and this buyer represented 25%. Forecast annual contribution was ₹8 crore lower than under the original proposal. That contribution difference was an estimate after the relevant operating assumptions, not the ₹56 crore difference between the two proposed buyer allocations and not a realised cash loss. The accounts needed to show those distinctions clearly.
The board accepted the narrower approach with the commercial conditions and review arrangements set by the responsible owners. It did not approve a general rule that every customer must remain below a universal percentage. We gave up an attractive forecast contribution and took on more contracting work. The company also retained exposure to its other buyers, grid conditions and the energy it could actually export; distributing the receipts did not eliminate those risks.
The subsequent FY 2026 generation revenue was ₹334 crore, below both planning cases. I kept that actual company result separate from the concentration choice and did not present the decision as having protected a measured sum of money. No buyer default or avoided loss is invented to vindicate the recommendation. The case records the exposure we were willing to accept and the opportunity we relinquished. For a similar offer, I would bring the portfolio concentration account into the first commercial review, before a favourable price and a single prospective relationship become the main story the board is asked to approve.
§ 5
The FY 2026 generation budget was 910 GWh, while metered export was 812 GWh. The 98 GWh shortfall prompted competing accounts. Operations pointed to the resource and grid conditions; the board wanted to understand the company's own asset performance. Some colleagues proposed leading the annual review with an availability measure that looked stronger than the export result. I wanted the useful operating measures retained, but not used to displace the energy outcome the enterprise had planned around.
A joint review allocated estimated contributions of 52 GWh to resource variation, 24 GWh to grid constraints and 22 GWh to asset unavailability within its stated method. The estimates summed to the 98 GWh difference, but their tidy reconciliation did not make them independently metered causal quantities. The method, assumptions and interactions were disclosed. Technical and grid specialists owned those assessments, while finance kept the metered export and revenue account distinct. We did not imply that the company controlled wind conditions or that every unavailable asset hour had the same energy consequence.
I presented the actual result before its explanation and asked for separate management responses where the company could act. The board did not receive a replacement budget that made 812 GWh look like the original commitment. We commissioned a ₹2.6 crore asset-review and operating-plan programme, with subsequent spending proposals subject to their own approval. That amount funded investigation and planning; it was not a claim that the 22 GWh asset estimate would all be recovered or that a particular repair had already produced a return.
The consequence was an annual account with an unfavourable result still visible. It gave the board a basis to distinguish what management could influence from what required a different planning assumption. I would improve the original budget's account of uncertainty and the review method before the next year begins. The lesson I retain is that explanation and accountability should strengthen each other. An executive can describe external circumstances accurately without using them to make the agreed outcome disappear, and can accept responsibility for the company's choices without claiming control over every factor in generation.
Chapter V
A service measure may be correctly calculated and still leave the economic consequence of timing outside the discussion. My maintenance-calendar error made that distinction expensive.
Read the essayA replacement asset may be better in a mature year while the journey to that year carries a different commitment. A common comparison period makes the board's choice more intelligible.
Read the essayAn attractive offer changes more than the contract register. It can alter the consequences of one relationship for the whole enterprise, even when there is no reason to question the buyer's conduct.
Read the essayAn invitation
Selected governance and executive discussions about asset transitions, service promises and accountable growth, subject to my continuing executive directorship and relationship review.
office@harleenmevqani.example