Refund operations and account resolution 6 min read
The practitioner
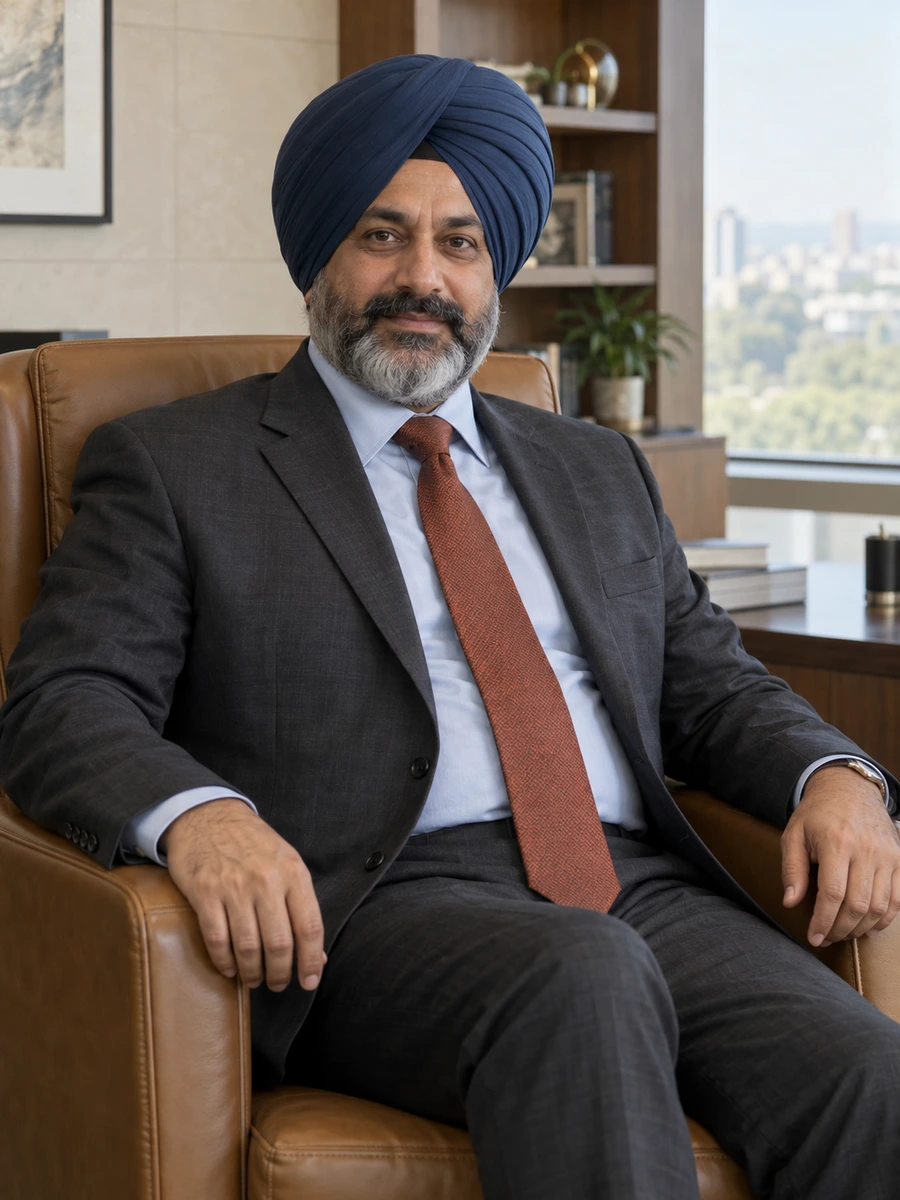
Jasdeep Ruvanpal
I completed a commerce degree at Garelvian College of Commerce in May 1993 and joined Doraveth Machinery Services in Ludhiana that July. The business coordinated repairs and replacement components for small workshops. I began as a service coordinator, arranging visits and checking whether the record matched what the technician and customer said had happened. A machine model, a serial number and an invoice could each identify part of a job without proving that the right work had been completed. I learnt to ask which physical event a status described before treating it as a basis for the next action.
Tavresh; March 2026, not delegated lending authority
Operations colleagues
284
Led through six managers
Regional offices
42
Four northern Indian states
I run equipment-finance operations by keeping the physical asset, the movement of money and the customer's account connected through evidence that another person can follow.
I am COO of Tavresh Equipment Finance in Ludhiana. We lend to small businesses acquiring workshop machinery and diagnostic equipment across four northern states. Our March 2026 loan portfolio was ₹2,180 crore, with 870 employees across 42 offices. I lead 284 operations colleagues through six managers. Credit approval, finance, compliance, technology and collections remain separate functions; my responsibility is the reliable execution and record of the work delegated to operations.
My career began at a machinery-services company, where a job could look complete in a register while the customer still waited for the right component or a usable service record. I moved into lending in 2000 and brought that attention to the difference between an administrative entry and a physical event. Branch, regional and central loan-operation roles followed before I became COO inApril 2021. The scale changed, but the need to trace a record back to the event remained.
The decisions here concern machine-identification evidence, the date used to start loan interest, custody of closed-account files and supplier refunds after cancelled orders. In each case, a plausible system status was insufficient. We delayed disbursements, corrected customer charges, paid more for accountable document custody and left unresolved refunds visible. I want a reader to understand the operational consequence of those choices, including the work that remained outside my authority to decide.
The machine behind the invoice
We held 62 proposed disbursements totalling ₹18.6 crore while equipment identifiers were checked against inspection records. Forty-three files later met the conditions to proceed; nineteen returned to credit and commercial teams for further decisions. A paperwork discrepancy was not labelled fraud merely because it delayed payment.
The date behind the interest charge
A review identified 86 accounts where an internal booking date had started interest before actual disbursement. Finance and compliance validated ₹11.8 lakh in excess charges, which were refunded. We changed the event used by the servicing process and tested it against bank evidence rather than treating the refund as the end of the correction.
The account behind a supplier refund
Thirty-one cancelled equipment orders required ₹8.4 crore of supplier refunds. By the review date ₹7.6 crore had arrived;24 account cases were resolved and seven still required follow-up, with ₹80 lakh of cash outstanding. Receipt, identification and application to a borrower account were reported as separate steps.
Current focus
I am improving the handovers where equipment evidence, bank events and account records meet. That includes the evidence a supplier must provide, the field checks that can change a release decision and the way an unresolved refund is owned after the original order has been cancelled.
Conversations I welcome
I could consider a first non-executive role in a service or equipment-related business where directors want stronger evidence of operating execution. Any appointment would require employer consent, conflict review and a realistic calendar. I have provisionally allowed twenty days a year, including preparation, without assuming that this would suit every board's needs.
Beyond the page
The record behind the perspective.
Formation
Bachelor of CommerceGarelvian College of Commerce · 1993
Jasdeep brought us the exact difference between the inspected machine and the financing record. We could make the credit decision without asking operations to guess what the change meant.
Harleen MevandarHead of credit, Tavresh Equipment Finance; colleague since 2017The full record ↗
Contact
I could consider a first non-executive role in a service or equipment-related business where directors want stronger evidence of operating execution. Any appointment would require employer consent, conflict review and a realistic calendar. I have provisionally allowed twenty days a year, including preparation, without assuming that this would suit every board's needs.