A transaction price cannot explain a service business until directors know which transactions qualify, which work remains and how a change will be resolved.
I want the margin in a proposal to survive the first invoice and the first month of operating work. That means knowing what is billable, whose cash is being reconciled and which costs continue when a project ends. Finance should make those distinctions visible early enough to change the decision. A clean presentation is useful only when it preserves the awkward facts beneath it.
Annual service revenue
₹124 Cr
Mirelva; year ended March 2026
Institutional clients
18
Loan administration and reconciliation support
Finance colleagues
47
Led through four managers
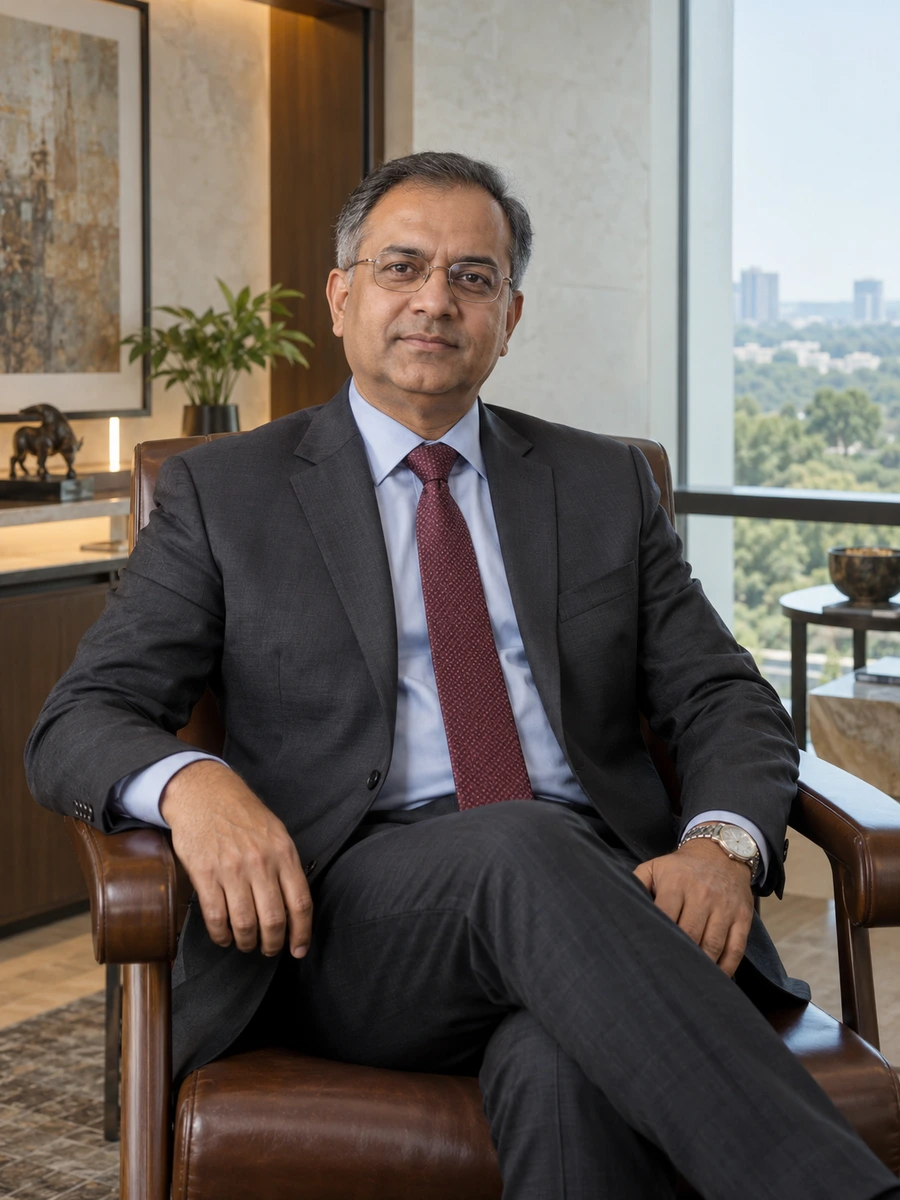
I lead finance for a loan-administration business where the definition of a billable account can matter more than the size of a contract announcement.
I am CFO of Mirelva Asset Services in Nagpur. We support eighteen financial institutions with account administration, reconciliation and reporting. Our 990 colleagues work across three cities, and revenue for the year ended March 2026 was ₹124 crore. We are a service provider: we do not lend, accept deposits or treat the collections we help clients reconcile as our own cash. That boundary is central to the way I read our numbers.
My route into this role began in the accounts team of a document-processing company. I learnt to connect a quoted transaction price with the work behind it, including the rework and exceptions that a simple volume measure missed. After moving to Mirelva in 2008, I built financial control around service contracts and later took responsibility for planning, cash and board reporting. I became CFO in April 2021, during the change to employee-majority ownership.
The decisions here explain my contribution more clearly than a list of finance activities. I challenged a contract model that counted dormant accounts as billable, removed client-owned balances from an internal cash view, recognised an agreed service credit and asked the board to consider the cash cost of software independently of its accounting treatment. In each case the correction made a proposition less attractive before it made the decision more dependable.
The account definition changed the margin
A proposal used 90,000 accounts at ₹120 a month. Only 74,000 met the draft billing definition. At that volume, annual revenue was ₹10.656 crore against ₹11.4 crore of recurring direct cost. The difference required a new price and a more candid discussion with the client.
A client balance was not our reserve
An internal dashboard combined ₹18.4 crore of company cash with ₹7.2 crore held in client-owned accounts. We corrected the view before a proposed ₹5 crore distribution went to shareholders. No client funds had entered our bank account; the error was in the decision report.
A credit before a collection claim
An overdue ₹1.1 crore service invoice included a substantiated ₹36 lakh service credit. I supported recognising the adjustment instead of treating the whole amount as collectible. The client later paid ₹68 lakh of the revised ₹74 lakh balance; the remaining ₹6 lakh stayed visible.
Current focus
I am linking bid assumptions, invoice definitions and operating-cost reviews so that a change agreed by one team cannot remain invisible to the others. The work includes separating recurring contract economics from mobilisation fees and ensuring that financial reports identify the legal owner of every cash balance they display.
Conversations I welcome
I would consider one external board contribution after employer consent and a conflict review. My present experience is as a finance executive presenting to directors, not as a director myself. An indicative eighteen days a year would need to be tested against the actual induction, preparation and meeting calendar.
Beyond the page
The record behind the perspective.
Formation
Bachelor of CommerceHiravren College of Commerce · 1995
Arvind asked us which accounts the client would pay for and which work would remain even if the count fell. That changed the bid discussion before we signed the contract.
Leena PorsadkarOperations head, Mirelva Asset Services; colleague since 2016The full record ↗
Contact
I would consider one external board contribution after employer consent and a conflict review. My present experience is as a finance executive presenting to directors, not as a director myself. An indicative eighteen days a year would need to be tested against the actual induction, preparation and meeting calendar.