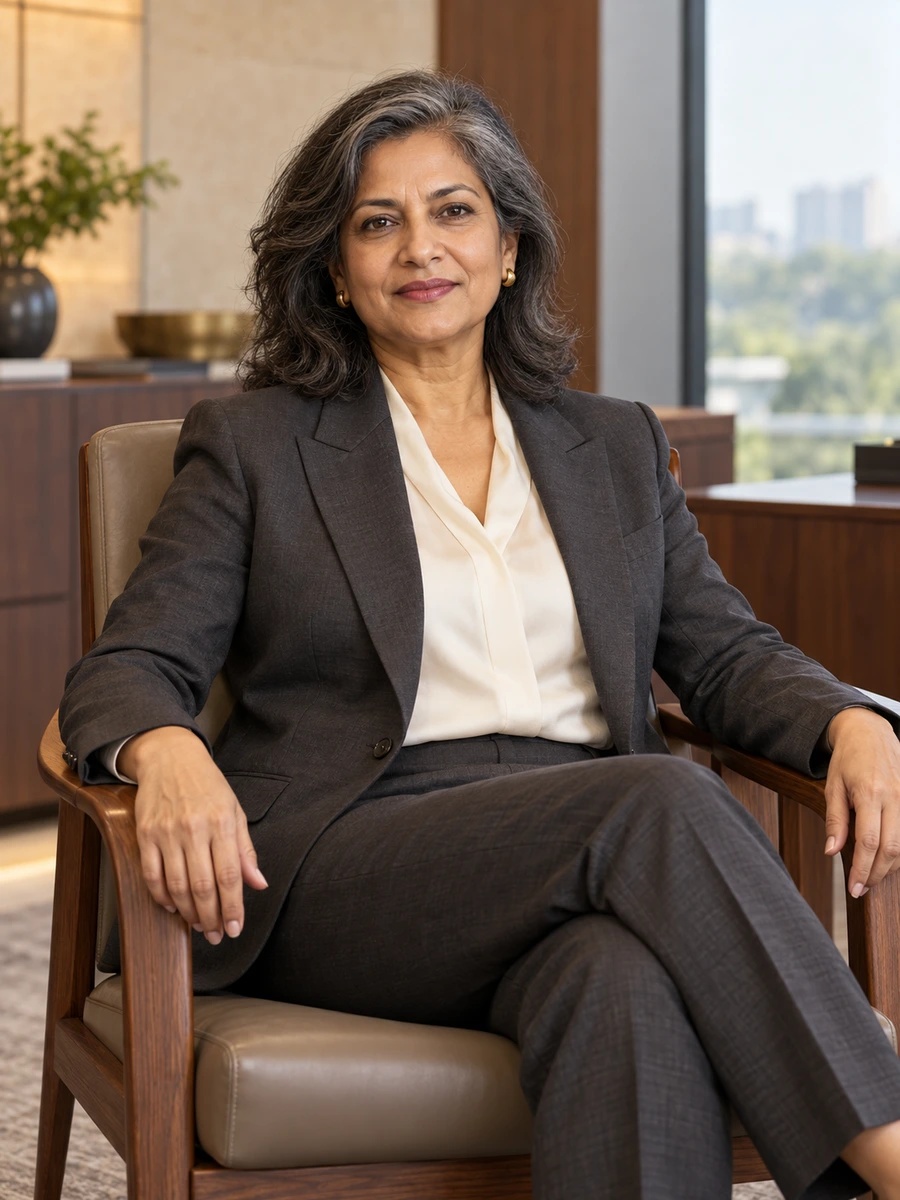
A life insurer inherits obligations that outlast its sales plans and leadership appointments. I want our growth decisions to account for the people who will still depend on them years later.
Leadership paper / 01
Life-insurance distribution5 min read
Lead for the years after the sale
Abstract
A large channel can be valuable and still require a different conversation about concentration, timing and the cost of alternatives.
I am Nandini Zheqari, chief executive of the fictional Vaqruni Life Assurance in Nagpur. I grew up in Guwahati and began in employee-benefit administration, where a record could remain important long after the person who created it had left. Life insurance later gave that observation a larger commercial meaning. A company can change its distribution plan, technology or leadership while the policyholder continues to rely on an undertaking made years before. I want those continuing responsibilities visible in decisions about growth.
Vaqruni has 580 employees and 24 branches. Total premium for the year ending March 2026 was ₹1,360 crore: ₹510 crore from new business and ₹850 crore from renewals. Assets under management of ₹4,860 crore are a separate measure and cannot be treated as spare operating cash. Three domestic corporate investors own 51%, 29% and 20%; I have no personal holding. Nine executives report to me within a board-approved ₹146 crore FY 2026–27 operating-expense plan. Mehul Qorzali leads finance and Shabana Melzavi the actuarial function. Their professional assessments remain essential to executive and board decisions.
The cases here examine what a single growth number can hide. We separated the contribution of a large single-premium partnership from recurring new-business flows. We revised a sales conversation that made an illustrated future value easier to remember than the premiums needed to reach it. We gave existing-policy revival a distinct servicing route instead of allowing it to disappear into a replacement-sales campaign. We also delayed retirement of a legacy platform until closed-to-new-business policies could still be serviced on their own terms. These choices involved cost, slower expansion or a less convenient success story; none is presented as a universal answer.
One partner's volume changed the picture of growth
₹210 crore of ₹510 crore new-business premium came through one single-premium partnership. The board examined that concentration separately from ₹300 crore through other routes.
A revival discussion was not counted as a new sale
A 240-case service review kept 92 revivals,58 requests for a separate new-policy discussion and 90 undecided customers in different categories.
Closed products retained an operating obligation
A planned platform retirement was postponed while eighteen older policy variants were mapped and tested; a product no longer sold was still a contract to service.
Current focus
Building a growth account that includes distribution dependence, policyholder understanding and the operating life of older contracts.
Conversations I welcome
One carefully assessed external board contribution alongside my continuing executive responsibilities, subject to consent and appointment requirements.
Beyond the page
The record behind the perspective.
In the boardroom
Vaqruni Life AssuranceExecutive Director · July 2019–Present
Formation
Bachelor of CommerceNerqethi Commerce College · 1990
Nandini kept the successful partner in the story while asking us to show the dependence behind the total. The revised paper supported a commercial decision instead of turning the analysis into a criticism of the team that had delivered.
Mehul QorzaliChief Financial Officer, Vaqruni Life Assurance; fictional colleagueThe full record ↗
Contact
One carefully assessed external board contribution alongside my continuing executive responsibilities, subject to consent and appointment requirements.