Raphael CampbellChief Technology Officer
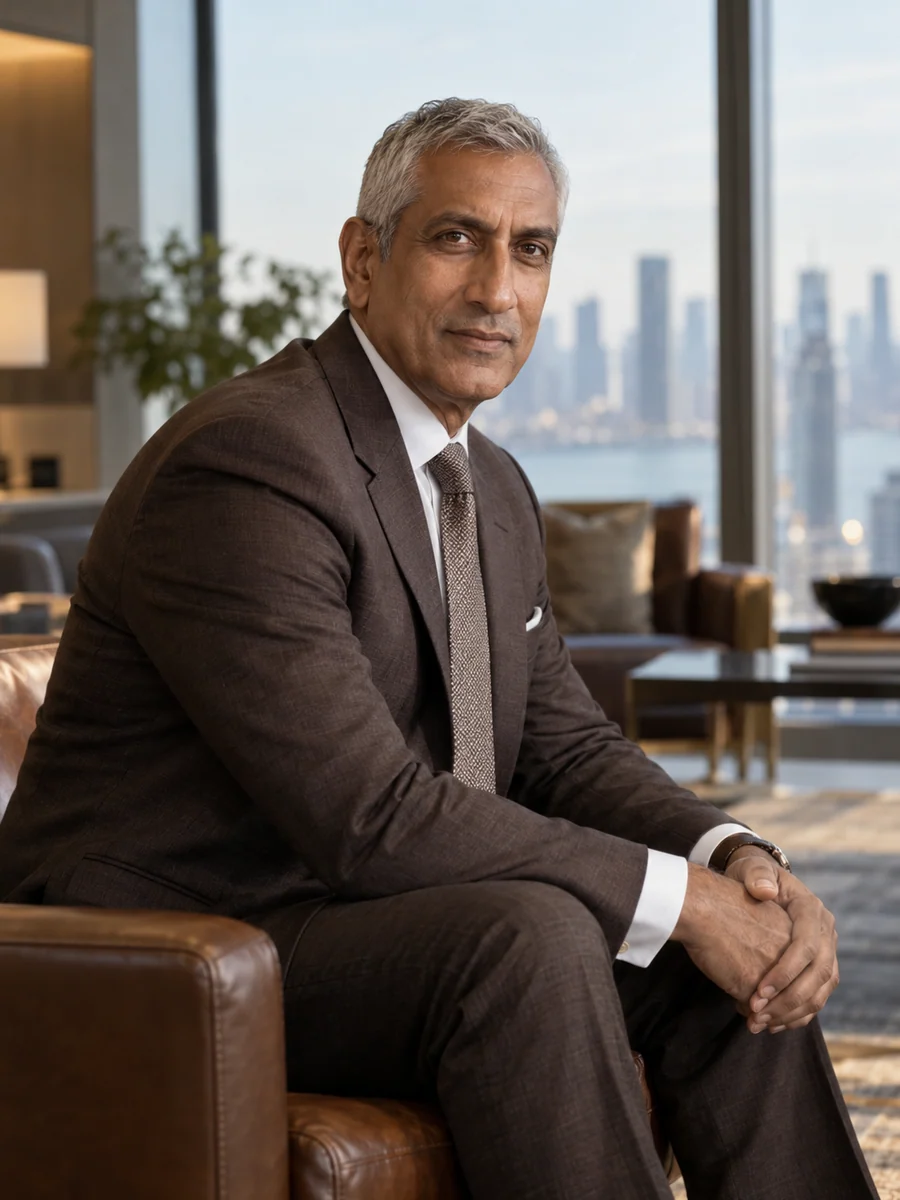
Portrait of Raphael Campbell
Chief Technology Officer

An introduction

The work our staff do around the system


I measure a financial institution's technology by the manual work its people still do to make it right.

Canada

Open to Board appointments

Start a conversation
My approach

Every recurring spreadsheet, rekeyed field and overnight correction tells me where our systems stopped matching the business. I would rather fund the removal of that work than add a channel on top of it. A financial institution's technology is only as dependable as the manual steps it quietly needs, so I count them, name their owners and report them beside each investment.

Trust company assets
C$9.8 bn
Pembrevale Trust Company at 31 December 2025; employer scale, not my budget
Technology budget I am accountable for
C$47 M
2026: C$32 million operating and C$15 million capital
Recurring manual workarounds on the register
212 → 104
Opened September 2021; count at June 2026
Weekly payment exceptions resolved by hand
340 → 88
Early 2025 compared with June 2026, after intraday posting

Work worth discussing.

01Declining a discounted core contract until the workarounds were counted

In November 2021, a core-banking vendor proposed replacing our deposit and mortgage ledger with a cloud-hosted platform for C$38 million over five years. The offer carried a 12 per cent discount, worth about C$4.6 million, if we signed by March 2022. Our mainframe hosting contract expired in 2023, and the chief executive and two directors saw the replacement as overdue. They were right that the ledger needed replacing.

I was less sure what we would be replacing it for. The workaround register was two months old and already held 212 entries. Tracing each one, we found that 131 began upstream of the ledger: broker mortgage files arriving with missing or inconsistent fields, deposit brokers sending GIC instructions in eleven different formats, and estate payments keyed from paper. A new core would have received the same inputs, and the vendor's plan counted 81 custom interfaces to accommodate them.

I recommended that we let the deadline pass, fix intake first and return to market in 2024. Our CFO, Denise Ouimette, disagreed; the discount was real money, and a two-year hosting extension would cost C$1.9 million. The board accepted my recommendation after the risk committee reviewed the register, and we gave up the discount.

Over two years we added validation to the broker portal, agreed a single file format with all eleven deposit brokers and replaced paper estate instructions with a structured form. Seventy-four workarounds were retired by December 2023. The revised specification needed 46 interfaces instead of 81. In September 2024 we signed a C$36.2 million contract, about C$2.8 million more than the discounted 2021 price before counting the hosting extension. Conversion is planned for 2027.

Every technology proposal now lists the workarounds it removes and those it leaves.

I would start the inventory before any vendor process begins. Because the register arrived after the offer, the board faced a deadline-driven choice, and the hosting extension cost more than I had first estimated.
02Verifying income at source on every broker mortgage file

By early 2023 our underwriters were finding altered documents in broker-submitted mortgage applications more often: employment letters from employers that did not answer the telephone, bank statements whose balances did not reconcile, pay stubs with inconsistent deductions. Confirmed document fraud on loans already funded had cost us C$2.9 million in 2022. Underwriters compensated by calling employers themselves, about forty minutes a file, and those calls were an entry on the workaround register.

I proposed verifying income and bank data directly from source on every application, with the applicant's consent, and screening every uploaded document for editing. Curtis Brayford, who leads broker distribution, argued for applying it only above C$750,000, where losses per case were largest. Brokers told him a universal check would send business to lenders who approved faster. He had a point, because the smaller files were the most price-sensitive. Our fraud data showed, however, that two-thirds of confirmed cases sat below that threshold.

Lorraine Petrishyn approved universal verification from January 2024. We accepted that median approval time would rise from two business days to three. Broker submissions fell 8 per cent over the following two quarters before recovering most of the decline. Harjit Dhaliwal's underwriting team designed an alternative route for applicants whose income does not appear neatly in bank data, including self-employed borrowers and newcomers to Canada. Our privacy officer limited what we keep to the verification result and the evidence needed for audit.

Losses on funded loans attributable to document fraud fell to C$0.6 million in 2025, and employer calls fell by about 70 per cent. Applications withdrawn after the verification request rose, and we cannot know how many of those were honest borrowers deterred by the step. I report that figure alongside the loss reduction.

I would involve brokers earlier and design the alternative route before launch. In the first quarter, too many self-employed applicants were sent to manual review without explanation, and for them the control felt like an accusation.

03Postponing real-time payments until exceptions no longer needed a night shift

Our estate and trust business wanted to pay beneficiaries and maturing GICs instantly once Canada's planned real-time payment rail allowed it. Monique Tessier, who leads that business, had executors asking why a settled estate still took two days to reach a family's account. In early 2025, a planning group proposed that we prepare to connect through a sponsoring bank as soon as institutions of our kind could join, at an estimated cost of C$2.2 million.

The obstacle was not the connection. Our ledger still posted payments in an overnight batch, and a team of six reconciled about 340 payment exceptions a week between midnight and six in the morning: names that did not match, accounts closed after the instruction, duplicate submissions from deposit brokers. In a real-time system those exceptions would arrive at any hour, after the customer had been told the payment was complete.

I recommended deferring the connection by about a year and spending C$3.1 million first on a posting service in front of the mainframe and automated handling of the common exception types. Monique disagreed strongly, and I understood why: her clients would wait longer, and a competitor might reach them first. We agreed an interim measure, a same-day wire option for urgent estate payments, which costs us about C$140,000 a year in fees we do not pass on.

By June 2026 the posting service applied deposits and payments intraday, and weekly manual exceptions had fallen to 88. Four of the six overnight reconcilers moved to day roles in payment operations; two chose to retire. Our connection is now planned for 2027, subject to the rail's own timetable and the sponsor's onboarding.

The postponement has a real cost in client experience, and I report it as one rather than as prudence rewarded. I would have shared the exception volumes with Monique's team a year earlier. They learnt the scale of the problem from my recommendation rather than from data we had already been collecting.

I fund the removal of the manual work hidden around a trust company's systems before I fund anything new on top of them.

I am chief technology officer of Pembrevale Trust Company, a federally regulated trust and loan company headquartered in Winnipeg. We lend residential mortgages arranged by brokers in Manitoba, Saskatchewan, Alberta and Ontario, take deposits mainly as GICs sold through deposit brokers and our own website, and administer estates and personal trusts. At 31 December 2025 we held C$9.8 billion of assets and employed about 640 people. I lead 156 technology employees and contractors through five directors, with a 2026 budget of C$47 million, and I report to our chief executive, Lorraine Petrishyn.

I first worked at Pembrevale in 2000, writing COBOL for the deposit ledger that still runs our accounts on a hosted mainframe. Returning as CTO in 2021, I asked operations colleagues to list every task they performed because a system could not. The register reached 212 recurring workarounds: spreadsheets kept beside the ledger, broker data typed twice, telephone calls to confirm an employer, payment exceptions fixed by hand during the overnight batch. Each one was a cost, a fraud opening or a delay that no project plan showed.

That register now shapes our investment choices. We postponed a core-ledger contract until we knew which workarounds a new core would remove and which it would simply move. We required direct income verification on every broker mortgage file after altered documents reached our underwriters. We delayed connecting to Canada's planned real-time payment rail until exceptions no longer depended on a night shift. The count stood at 104 in June 2026. I report it to our board risk committee each quarter, beside cyber and resilience measures.

A core contract signed after the inventory

In 2021 a vendor offered a 12 per cent discount to sign a C$38 million core replacement by March 2022. We declined, extended our hosting contract at a cost of C$1.9 million and found that 131 of 212 workarounds began upstream of the ledger. The narrower contract signed in 2024 needs 46 interfaces instead of 81.

Altered documents stopped before funding

Direct verification of income and bank data on every broker application cut document-fraud losses on funded loans from C$2.9 million in 2022 to C$0.6 million in 2025. Median approval time rose from two business days to three, and broker submissions fell 8 per cent for two quarters.

Payment exceptions handled in daylight

Before connecting to a real-time rail, we automated the payment exceptions our overnight team resolved by hand. Weekly manual exceptions fell from 340 to 88. Our estate and trust business gave up early access; urgent estate payments go by same-day wire meanwhile.

Current focus

I am preparing the 2027 ledger conversion so that each remaining entry on the workaround register has an owner and either a removal date or a written reason to stay, and the risk committee sees that list first.

Conversations I welcome

I am open to a first corporate board seat on a risk or technology committee in insurance, pension administration, payments infrastructure or a public financial agency, with twenty-two days a year, subject to consent from my chief executive and board and to a conflict review against Pembrevale's lending and deposit markets.

The leadership record

Trusted with consequential decisions.

In the boardroom

  • Wyndrell Housing Co-operativeElected volunteer director · 2019–present

Formation

  • Bachelor of Science in computer scienceBrandholm University · 1996
  • Board governance programmeHalvecourt Institute of Governance · 2025
Raphael told the board we should let a discount lapse, and then showed us exactly what the delay would cost. When he brings a recommendation, the opposing case is already in the paper.
Lorraine PetrishynChief executive, Pembrevale Trust Company
The full record ↗

Contact

I am open to a first corporate board seat on a risk or technology committee in insurance, pension administration, payments infrastructure or a public financial agency, with twenty-two days a year, subject to consent from my chief executive and board and to a conflict review against Pembrevale's lending and deposit markets.

  • Board appointments