The Promise Audit
Group CEO
A group chief executive keeps the original earnings promise beside the result, including the missed year, so the next board can examine judgement rather than a rewritten success story.
The signature device
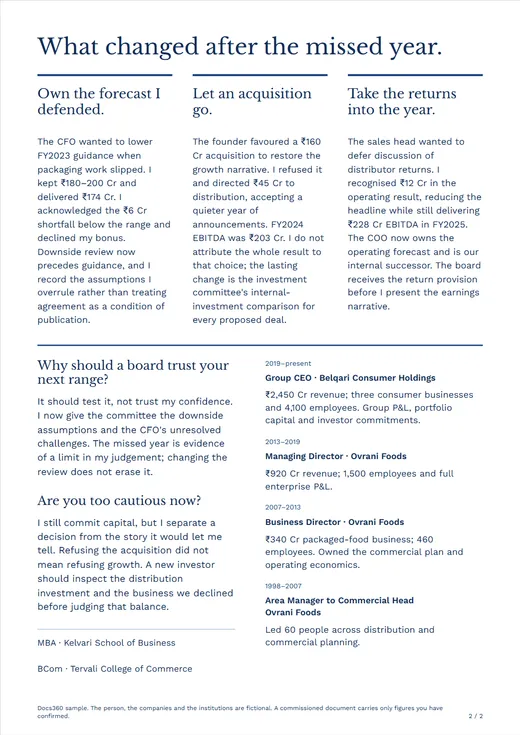
Four original guidance intervals are checked against actual EBITDA points on one explicit value axis, with the sole miss measured from the nearest promised boundary.
Who should choose it
A group chief executive whose investor-facing record includes a visible miss and who can show how the subsequent capital and reporting decisions changed.
Who it puts first
Board or NRC chairInvestor or PE partnerSearch partner
CXO and MD · Bold colour · 2 A4 pages
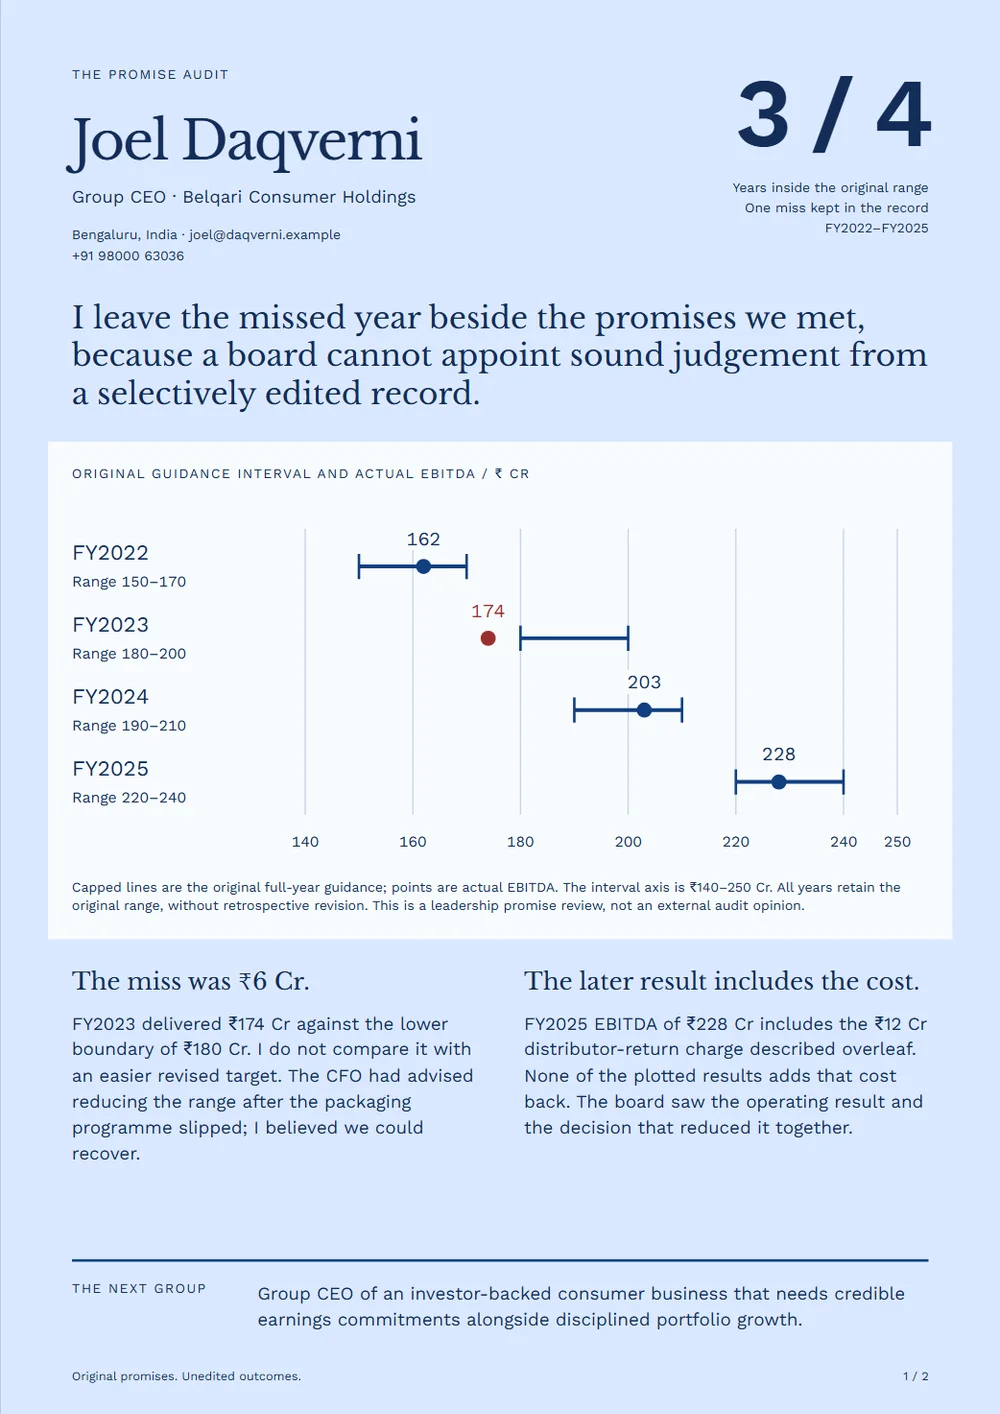
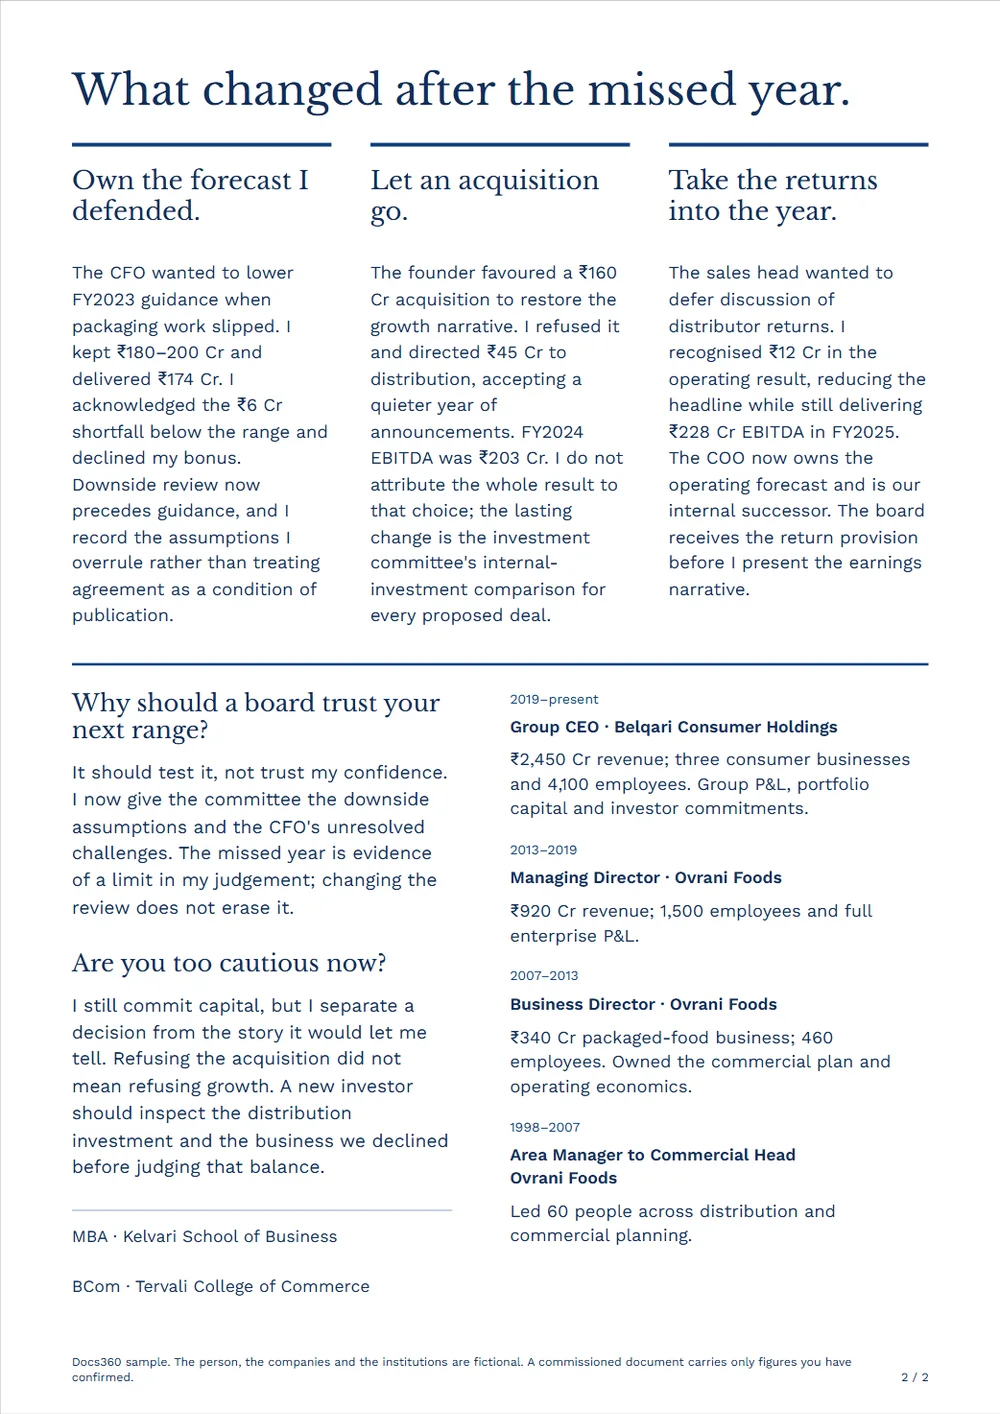
The design, and its plain companion.
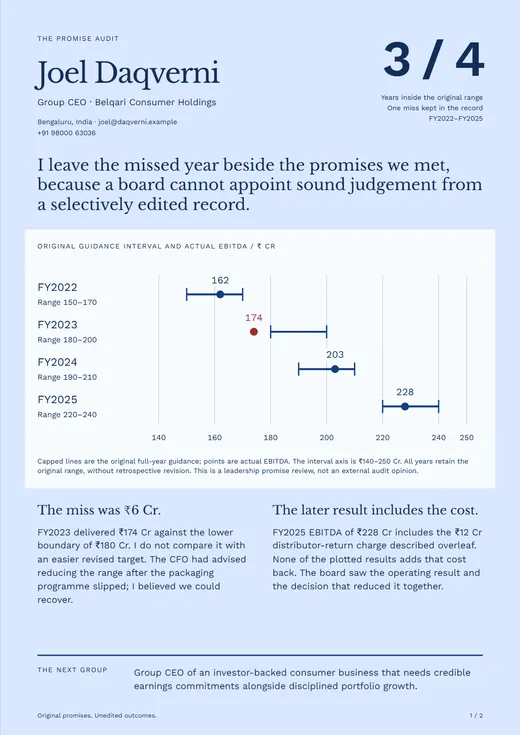
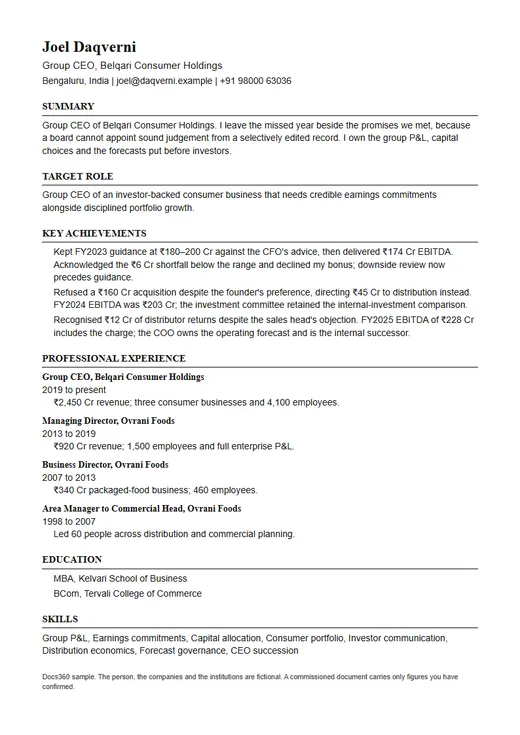
Joel Daqverni, the companies and the institutions on this page are fictional. A commissioned document carries only your own facts, and every figure is one you have confirmed.